


TL;DR: Three markets are converging on decisive levels at once: Brent crude is testing $120 resistance on Middle East supply risk, the US 10-year yield is holding near 5% as inflation and growth fears compete, and Nasdaq is barely clinging to 25,803 support on AI-financing concerns. With the Fed, GDP, PCE and Big Tech earnings all landing next week, the interaction between these three could matter more than any single move.
Why This Matters
Global markets ended a potentially decisive week with three major assets approaching important technical thresholds. Brent extended its rally to its highest futures settlement since late April, bringing the $120 region into focus, while the US 10-year Treasury yield ended the week around 5% after retreating sharply from its early-October peak. Meanwhile, Nasdaq Composite closed near 25,955, barely above support at 25,803, as concerns over AI investment returns and financing continued weighing on technology shares.
The three markets reflect competing inflation and growth risks. Rising oil prices threaten to prolong inflation pressures and complicate the interest-rate outlook, while uncertainty surrounding AI investment is undermining equity confidence and encouraging defensive demand for Treasuries. Whether yields respond more strongly to inflation concerns or weaker risk appetite could influence the next direction of both equities and borrowing costs. With the Fed decision, US GDP and PCE inflation data, and major technology earnings all scheduled next week, the convergence of these pressures is approaching an important test.
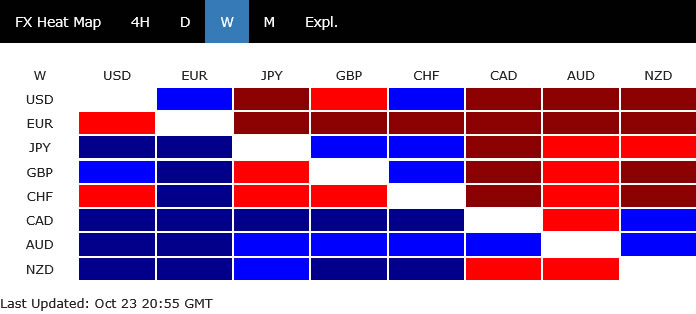
Currency performance also highlighted the uneven nature of the week’s market adjustment. Aussie led the major currencies, followed by Canadian Dollar and Kiwi, while Euro finished at the bottom of the rankings. Dollar and Swiss Franc also underperformed, suggesting that the technology-led equity retreat did not translate into a uniform shift toward traditional defensive currencies. The divergence reinforces the view that markets were responding to competing economic and geopolitical pressures rather than a single global risk-off theme.
Brent Approaches $120 as Middle East Risk Premium Builds
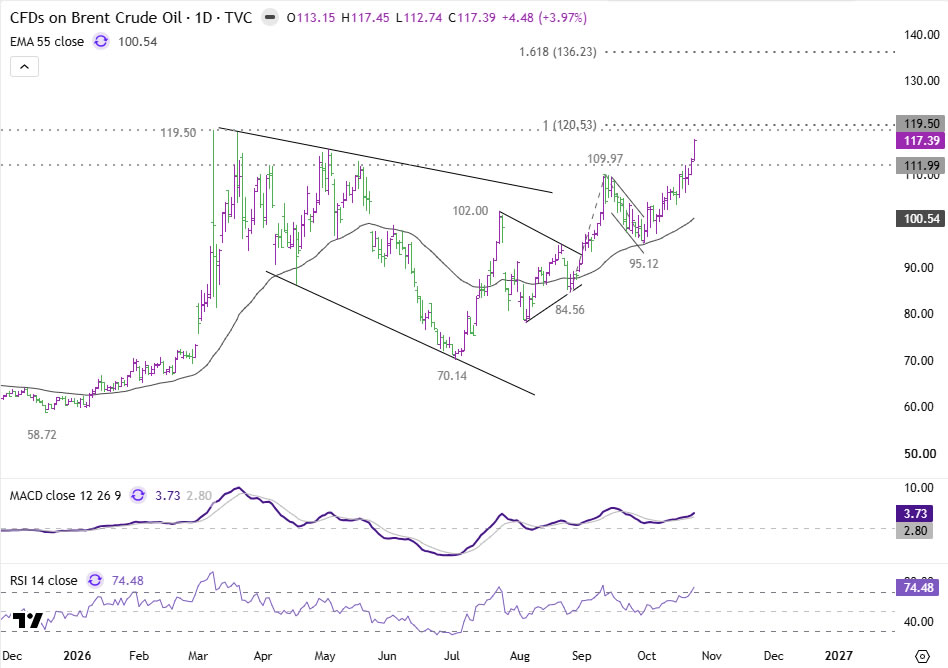
Brent crude extended its advance for a third consecutive week, with futures settling Friday at $116.72, up 3.1% on the day and approximately 6% over the week. The settlement was the highest since April 29, while the Brent CFD closed at 117.39. From its October 2 settlement at $102.77, Brent has gained approximately 13.6%, reflecting a sustained repricing of geopolitical supply risks rather than an isolated response to the latest headlines.
The rally has been driven partly by an escalating security situation in Saudi Arabia and the wider Middle East. Houthi attacks and claims involving Saudi energy installations, airports and shipping infrastructure have heightened concerns about further disruption. Aramco’s evacuation of personnel from its Dhahran headquarters added to the uncertainty, while repeated threats to regional shipping have reinforced the market’s sensitivity to the security of critical energy routes.
A separate concern is the reported preparation of US-Israeli military options for renewed strikes against Iran following the November 3 US midterm elections. The reported plans have drawn attention to the possibility that the current restraint on further US action could end after the election. However, no new military operation has been approved, and Trump’s public comments have offered mixed signals about the prospects for further escalation or an eventual resolution. The post-election period therefore represents a potential risk window, rather than a confirmed deadline for military action.
The oil market’s sensitivity is magnified by limited supply buffers:
- Global production: recovered by 2.5 million barrels per day to 102.3 million in September (IEA)
- Effective OPEC+ spare capacity: just 0.27 million barrels per day
- IEA 2026 demand forecast: a contraction of 2.6 million barrels per day
Observed inventories remained substantially below pre-war levels despite the production recovery, leaving relatively little room to absorb another significant supply disruption, while the expected demand contraction indicates that elevated prices are already weighing on consumption.
The current rally therefore reflects a geopolitical premium layered onto a market with thin supply protection, rather than evidence of another major confirmed production loss. Recovering exports and weakening demand provide counterweights, but the absence of a durable diplomatic resolution leaves prices vulnerable to further security developments.
Technically, Brent is approaching a particularly consequential resistance region. The March high at 119.50 is followed closely by the 100% projection of the rise from 84.56 to 109.97, measured from 95.12, at 120.53. A sustained break above this region would carry Brent beyond the earlier wartime spike and strengthen the case for an extension toward the 161.8% projection at 136.23.
However, daily RSI has risen to approximately 74, indicating increasingly stretched momentum. An initial rejection around $120 would therefore not be surprising. The important distinction is whether Brent can establish itself above the resistance region on a closing basis, rather than merely recording another intraday spike.
US 10-Year Yield Tests 5% as Inflation and Growth Risks Compete
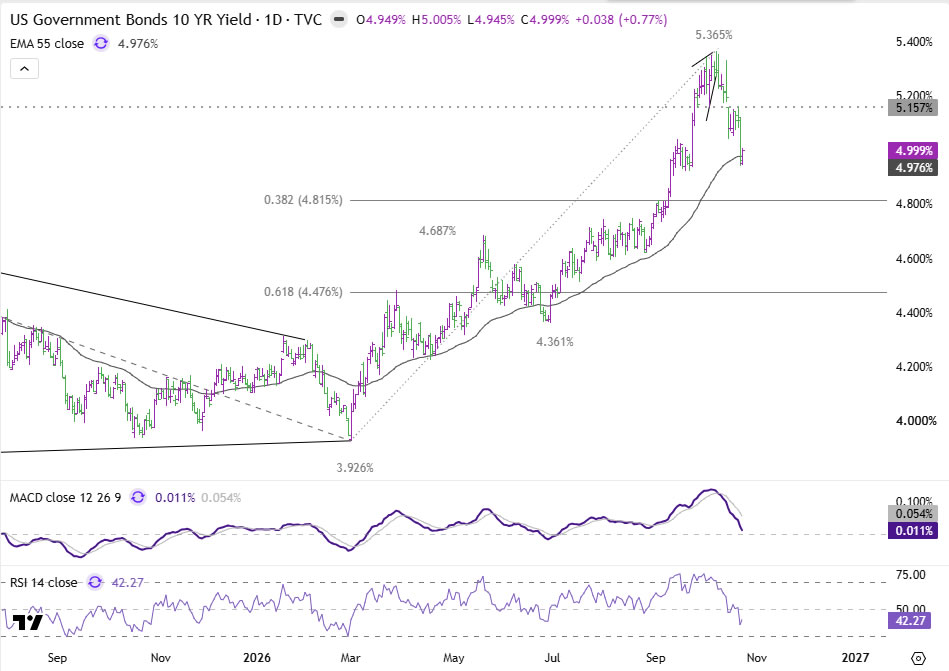
The US 10-year Treasury yield finished the week around 5%, following a volatile reversal from its early-October peak of 5.365%. The benchmark yield has declined for three consecutive weeks, reflecting a significant change in momentum after the earlier surge in borrowing costs.
Thursday provided the clearest example of the competing forces influencing the bond market. As technology shares retreated sharply, investors sought protection in Treasuries, pushing the 10-year yield down approximately 16 basis points. Inflation-adjusted yields also declined, suggesting that the move was closely associated with defensive demand and concerns about the growth and financing outlook.
Friday brought a partial reversal. Treasury yields rebounded toward 5% as oil extended its rally, even as US equities remained under pressure. The contrasting sessions illustrate how the bond market is being pulled between weaker risk appetite and renewed inflation concerns. Nevertheless, individual yield movements cannot be attributed exclusively to either factor, with policy expectations, Treasury supply and term premiums also influencing borrowing costs.
Fed futures continue to favor an unchanged policy rate at Wednesday’s meeting:
- October 28 meeting: ~90% probability of a hold, ~10% probability of a hike
- December meeting: ~76% probability of at least one increase
The distribution suggests that investors have become less convinced of an immediate move without abandoning expectations for further tightening later in the year.
From a technical perspective, the 5% threshold and the daily 55 EMA around 4.976% form the immediate decision zone. A sustained break below this area would reinforce the recent decline and bring the 38.2% retracement of the advance from 3.926% to 5.365%, at 4.815%, into focus. Further weakness would expose the 61.8% retracement at 4.476%.
Conversely, a sustained recovery above 5% would suggest that the recent Treasury rally is losing momentum. If accompanied by continued oil strength and weaker equities, such a move would raise concerns that renewed inflation or borrowing-cost pressures were becoming more influential.
The direction of yields next week will therefore be important not only for the Treasury market itself, but also for determining whether financial conditions provide relief or additional pressure for technology shares.
Nasdaq Nears Critical Support Amid AI Investment Concerns
Nasdaq Composite ended Friday at 25,955, following Thursday’s 2.6% decline, its largest daily loss since June. The index has retreated approximately 6% from its early-October record near 27,723, as investors increasingly question the financing requirements and eventual returns of large-scale AI investment.
The concern has shifted from whether AI investment is supporting corporate growth toward whether the scale and cost of that investment can be justified. Recent earnings have demonstrated continued demand for AI-related products and services, but substantial capital expenditure commitments have renewed attention on profitability, cash generation and the availability of financing. The pressure has been particularly evident among semiconductor companies and businesses closely tied to AI infrastructure development.
The financing dimension makes Treasury yields especially relevant. Higher borrowing costs could increase the burden of funding AI infrastructure, particularly for companies dependent on external capital. Conversely, lower yields could ease financial conditions, although a decline driven by deteriorating growth expectations would not necessarily provide lasting support for equity valuations.
Technically, Nasdaq’s retreat has taken it below the daily 55 EMA near 26,528, while daily RSI has fallen to around 38 and MACD has weakened. The immediate focus is 25,802.96 support, which sits only approximately 0.6% below Friday’s close.
A firm break below 25,803 would signal an extension of the current correction, but the more significant level lies around 25,036, the 38.2% retracement of the advance from 20,690 to 27,723. This level also coincides with the lower boundary of the rising channel from the April low.
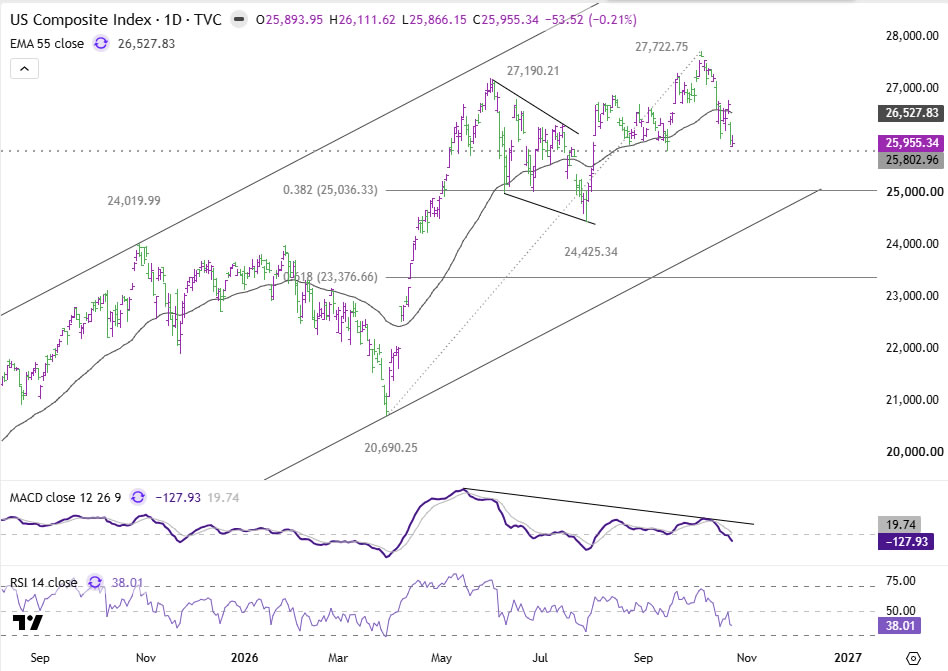
A sustained break through that support region would carry greater implications for the broader bullish structure, suggesting that the retreat is developing beyond a relatively contained correction. Further downside references would include 24,425 and the 61.8% retracement near 23,377.
On the other hand, stabilization above 25,803, followed by recovery through the daily moving average, would suggest that selling pressure is easing. Next week’s technology earnings could provide the catalyst for either outcome, particularly through guidance on capital expenditure, margins and expected AI-related returns.
Oil, Treasury Yields and Nasdaq: Three Markets, One Competing Set of Risks
The interaction between these markets could become more important than their individual movements.
Higher oil prices represent an inflation and operating-cost risk. A sustained advance beyond $120 could reinforce concerns about consumer prices, business costs and the prospect of interest rates remaining elevated. Higher borrowing costs, in turn, would be an additional challenge for technology companies already facing scrutiny over AI investment financing.
By contrast, a deeper Nasdaq correction could encourage defensive Treasury buying, pushing yields lower even if inflation concerns remain elevated. Such a decline in yields would not necessarily signal improving financial conditions if it reflected deteriorating investor confidence or concerns about future growth.
Three broad scenarios stand out:
- An inflation-dominated adjustment would feature Brent breaking sustainably above $120, Treasury yields recovering above 5%, and Nasdaq weakening further—suggesting higher energy costs and borrowing-rate pressures were compounding technology-sector concerns.
- A growth- and financing-driven adjustment would feature Nasdaq breaking below 25,803 and potentially 25,036, accompanied by Treasury yields declining toward 4.815%—consistent with stronger defensive demand and concerns about the sustainability of investment and growth.
- A stabilization scenario would involve oil consolidating or retreating, Treasury yields finding a more stable range, and Nasdaq holding its major support levels—suggesting neither the inflation shock nor technology-related financing concerns were intensifying.
These are conditional interpretations rather than definitive explanations of future market movements. Nevertheless, the relationship between Nasdaq and Treasury yields should help distinguish whether the next stage of market volatility is dominated by inflation pressures or concerns about growth and financing.
Week Ahead: Fed, GDP, PCE and Big-Tech Earnings
The coming week brings an unusually concentrated sequence of monetary-policy decisions, economic releases and corporate earnings that could test all three markets.
The Fed announces its policy decision on Wednesday, October 28. With an unchanged rate widely expected, attention will focus on how Chair Kevin Warsh assesses the conflicting signals from resilient economic activity, persistent inflation and renewed financial-market volatility. The absence of new economic projections makes the accompanying statement and press conference particularly important for interpreting the near-term outlook.
Thursday’s US third-quarter GDP and September PCE inflation releases will provide further evidence on the strength of growth and the persistence of price pressures. Strong growth combined with elevated inflation could support yields, while weaker activity would increase attention on the growth risks underlying the technology correction.
Corporate earnings will be equally important. Alphabet and Microsoft report Wednesday, followed by Amazon and Intel on Thursday. Investors will be looking beyond headline earnings toward AI capital expenditure, funding requirements, cash generation and the expected returns on infrastructure investment. Strong results may help stabilize Nasdaq, but substantial additional spending commitments could also invite further scrutiny.
Treasury auctions across the two-, five- and seven-year maturities will offer additional indications of investor demand for government debt. Elsewhere, Australian inflation data, policy decisions from BoC and ECB, and Friday’s BoJ meeting will contribute to the broader global interest-rate backdrop.
Beyond the immediate week, the November 3 US midterm elections remain an important potential geopolitical turning point for oil, particularly given reports of military contingency planning involving Iran.
Market Outlook: Three Levels to Watch
Markets enter the new week with three closely connected thresholds: Brent around $120, the US 10-year yield around 5%, and Nasdaq support at 25,803, followed by the more consequential 25,036 region.
None of these levels guarantees a breakout or breakdown. Brent’s rally is technically extended, Treasury yields are balancing competing economic forces, and Nasdaq’s correction has not yet breached the support region that would place its broader rising structure under greater pressure.
Nevertheless, the convergence is significant. Oil is testing how much geopolitical inflation risk markets can absorb, technology shares are testing confidence in the economics of AI investment, and Treasury yields are reflecting the tension between those forces.
With the Fed, GDP, PCE and major technology earnings arriving in quick succession, the coming week could provide a clearer indication of whether markets are approaching stabilization or another phase of adjustment.
Key Takeaways
- Brent has gained ~13.6% since October 2 and is testing the 119.50–120.53 resistance zone on Middle East supply risk, though stretched RSI (~74) warns of a possible initial rejection near $120.
- The US 10-year yield is holding near 5% after a three-week decline from 5.365%, caught between oil-driven inflation fears and AI-driven defensive Treasury demand.
- Fed futures assign ~90% probability to a hold on October 28, but ~76% probability of at least one hike by December—markets have pushed out the timing, not abandoned the tightening case.
- Nasdaq is clinging to 25,803 support (just 0.6% below Friday’s close) after a 6% retreat from its October record; a break exposes the more consequential 25,036 level.
- Next week’s Fed decision, US GDP/PCE data, and Alphabet/Microsoft/Amazon/Intel earnings will determine whether an inflation-dominated, growth-driven, or stabilization scenario takes hold across all three markets.





