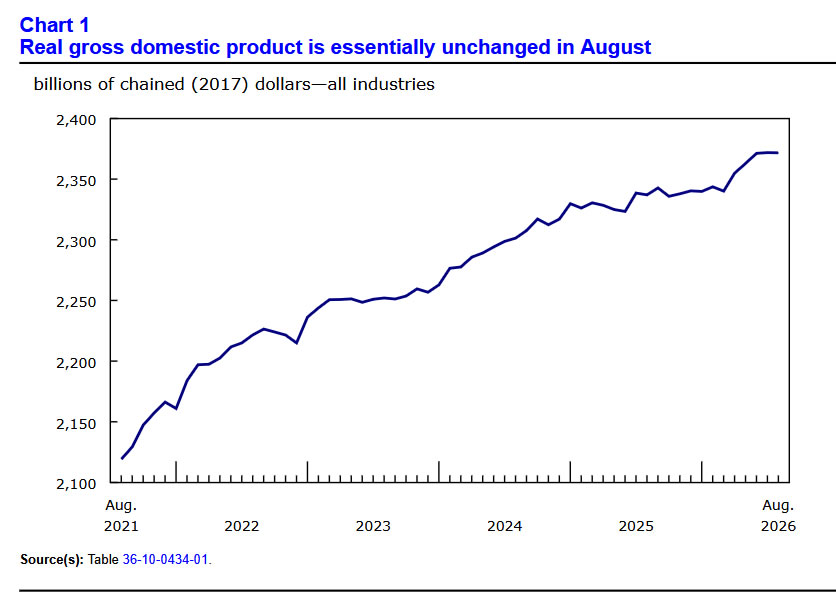
Canada’s economy stagnated for a second consecutive month in August, with real GDP essentially unchanged against market expectations of 0.2% growth. The weakness may have extended into September, as Statistics Canada’s advance estimate points to a 0.1% contraction, driven by declines in manufacturing and mining, quarrying, and oil and gas extraction. Despite the subdued monthly performance, preliminary estimates suggest GDP expanded 0.3% q/q in Q3, supported by stronger activity earlier in the quarter.
August’s sector breakdown revealed contrasting developments. Retail trade rebounded 1.2% after contracting 1.1% in July, supported by motor vehicle dealers, food retailers and general merchandise stores. Manufacturing also expanded 0.3%, helped by machinery production and petroleum refining. However, these gains were offset by a 1.4% contraction in wholesale trade, the largest drag on overall GDP, alongside weakness in public administration and oil and gas extraction. Goods-producing industries edged up 0.1%, while services-producing industries declined 0.1%, leaving aggregate output essentially flat.
The figures suggest that Canada’s economic momentum weakened considerably toward the end of Q3, despite pockets of resilience in consumer-facing industries and manufacturing. September’s estimated contraction is particularly concerning because it points to renewed manufacturing weakness following August’s modest expansion, while resource extraction continued to struggle. Although the preliminary 0.3% quarterly growth estimate indicates that the economy continued expanding over Q3 as a whole, the absence of meaningful growth in July and August, followed by an estimated September decline, suggests a fragile underlying trend. The official September and Q3 GDP figures are scheduled for release on November 30.
Data Summary
Canada GDP by Industry — August 2026
Statistics Canada, released October 30, 2026
| Indicator | Jul | Aug | Cons |
|---|---|---|---|
| Real GDP M/M | 0.0% | ~0.0% | +0.2% |
| Goods-Producing Industries M/M | +0.2% | +0.1% | — |
| Services-Producing Industries M/M | ~0.0% | -0.1% | — |
Preliminary GDP Estimates
| Indicator | Estimate | Status |
|---|---|---|
| September GDP M/M | -0.1% | Advance estimate |
| Q3 GDP Q/Q | +0.3% | Preliminary indication, not annualized |
Selected Industry Performance — July → August 2026
| Industry | July | August |
|---|---|---|
| Retail Trade | -1.1% | +1.2% |
| Manufacturing | ~0.0% | +0.3% |
| Construction | +1.4% | +0.2% |
| Transportation and Warehousing | ~0.0% | +0.5% |
| Finance and Insurance | ~0.0% | +0.2% |
| Wholesale Trade | -0.3% | -1.4% |
| Public Administration | -0.3% | -0.8% |
| Utilities | +1.4% | -0.4% |
Source: Statistics Canada, Gross Domestic Product by Industry, August 2026. September and Q3 estimates are preliminary and subject to revision. Official results are scheduled for November 30.
Key Takeaways
- Canada’s economy stalls for a second month: Real GDP was essentially unchanged in August after a flat July reading, missing market expectations for 0.2% growth.
- September estimate points to contraction: Statistics Canada projects a 0.1% monthly decline, driven by weakness in manufacturing and mining, quarrying, and oil and gas extraction.
- Q3 growth remains positive but momentum weakens: Preliminary industry data suggest GDP expanded 0.3% q/q, although the monthly pattern indicates subdued activity toward the end of the quarter.
- Retail trade rebounds strongly: Output increased 1.2% after a 1.1% decline in July, supported by motor vehicle dealers, food retailers and general merchandise stores.
- Manufacturing provides modest support: The sector expanded 0.3%, helped by machinery manufacturing (+3.8%) and petroleum refineries (+4.2%), despite weakness in motor vehicles and parts production.
- Wholesale trade is the largest drag: Output contracted 1.4%, led partly by a 4.4% decline among motor vehicle and parts wholesalers.
- Public administration weighs on activity: The sector declined 0.8%, partly reflecting the winding down of temporary Census-related operations.
- Oil and gas extraction continues to weaken: Output fell 1.2% in August, marking a third consecutive monthly decline, with maintenance activity contributing to lower oil sands production.
- Growth remains uneven across industries: Goods-producing industries increased 0.1%, but services-producing industries declined 0.1%, leaving aggregate GDP essentially flat.
- September’s official release becomes important: The November 30 data will determine whether the estimated contraction and subdued Q3 growth are confirmed.