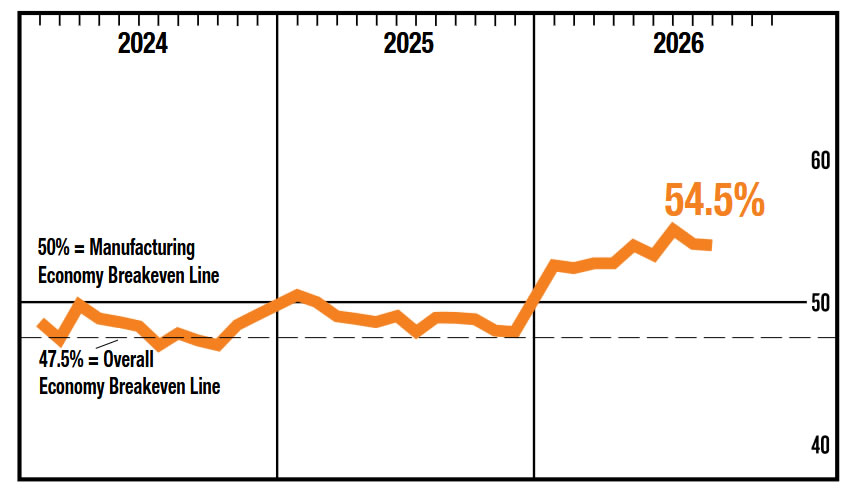
US ISM Manufacturing PMI edged from 54.6 to 54.5 in September, missing the 55.0 consensus but remaining firmly in expansion. The headline softness masked stronger demand indicators: New Orders rose from 53.7 to 55.3, while the Employment Index increased from 51.2 to 52.7. Production remained strong but slowed from 58.3 to 56.7, leaving the report more consistent with moderating output growth than a broader loss of manufacturing momentum.
Other internals reinforced the resilient demand picture. The Backlog of Orders Index jumped from 51.8 to 56.4, while customers’ inventories fell from 42.8 to 41.6, remaining in “too low” territory. New Export Orders stayed expansionary at 50.9 despite easing from 53.2, while manufacturers’ own inventories dropped from 50.6 to 48.6. Taken together, stronger orders, rising backlogs and low customer inventories suggest the slight decline in the headline PMI was not driven by a broad deterioration in demand.
The standout was inflation. Prices Paid surged from 71.1 to 77.9, far above the 72.0 consensus and close to March’s 78.3 reading. ISM said raw-material prices increased for a 24th consecutive month, with 58.6% of respondents reporting higher prices compared with 46.2% in August. Steel, aluminum, petroleum-related products and tariff-affected imports were among the sources of pressure. The September report therefore delivered a mixed headline but a distinctly firmer underlying message: demand and employment strengthened while factory input-cost inflation accelerated sharply.
Data Summary
| Indicator | Previous | Current | Expected |
|---|---|---|---|
| ISM Manufacturing PMI | 54.6 | 54.5 | 55.0 |
| Prices Paid | 71.1 | 77.9 | 72.0 |
| New Orders | 53.7 | 55.3 | — |
| Production | 58.3 | 56.7 | — |
| Employment | 51.2 | 52.7 | — |
| Supplier Deliveries | 59.3 | 59.0 | — |
| Inventories | 50.6 | 48.6 | — |
| Customers’ Inventories | 42.8 | 41.6 | — |
| Backlog of Orders | 51.8 | 56.4 | — |
| New Export Orders | 53.2 | 50.9 | — |
| Imports | 52.5 | 51.0 | — |
The headline PMI edged lower, but orders, employment and backlogs strengthened, while Prices Paid surged sharply.
Key Takeaways
- ISM Manufacturing slipped from 54.6 to 54.5, slightly below the 55.0 consensus, but remained comfortably in expansion.
- New Orders rose from 53.7 to 55.3, showing firmer incoming demand despite the small headline miss.
- Employment improved from 51.2 to 52.7, adding to the picture of continued labor-market resilience.
- Production slowed from 58.3 to 56.7, indicating softer output growth rather than outright weakness.
- Backlog of Orders jumped from 51.8 to 56.4, while Customers’ Inventories fell further to 41.6, suggesting the demand pipeline remained supportive.
- Manufacturers’ inventories fell from 50.6 to 48.6, moving back into contraction.
- The main surprise was Prices Paid surging from 71.1 to 77.9, far above the 72.0 consensus.
- ISM said raw-material prices increased for a 24th consecutive month, with 58.6% of respondents reporting higher prices versus 46.2% in August.
- Overall, the report was firmer underneath than the headline suggested, with resilient demand and hiring but sharply stronger inflation pressure.