- The Fed may not hike in 2027.
- Falling Treasury yields are weakening the US dollar.
The US dollar continues to slide from its peak alongside Treasury bond yields. The stabilisation of the Treasury market after yields touched their highest levels since 2002 is fuelling buying appetite among some investors. At the same time, the likelihood of aggressive monetary tightening by the Fed is diminishing. John Williams, President of the New York Fed, said he considers a single rate rise later this year to be sufficient and would prefer not to raise rates further in 2027. This stands in striking contrast to current expectations, where the central scenario for the end of next year envisages three rises from the current level and a 40% probability of four or more rises.
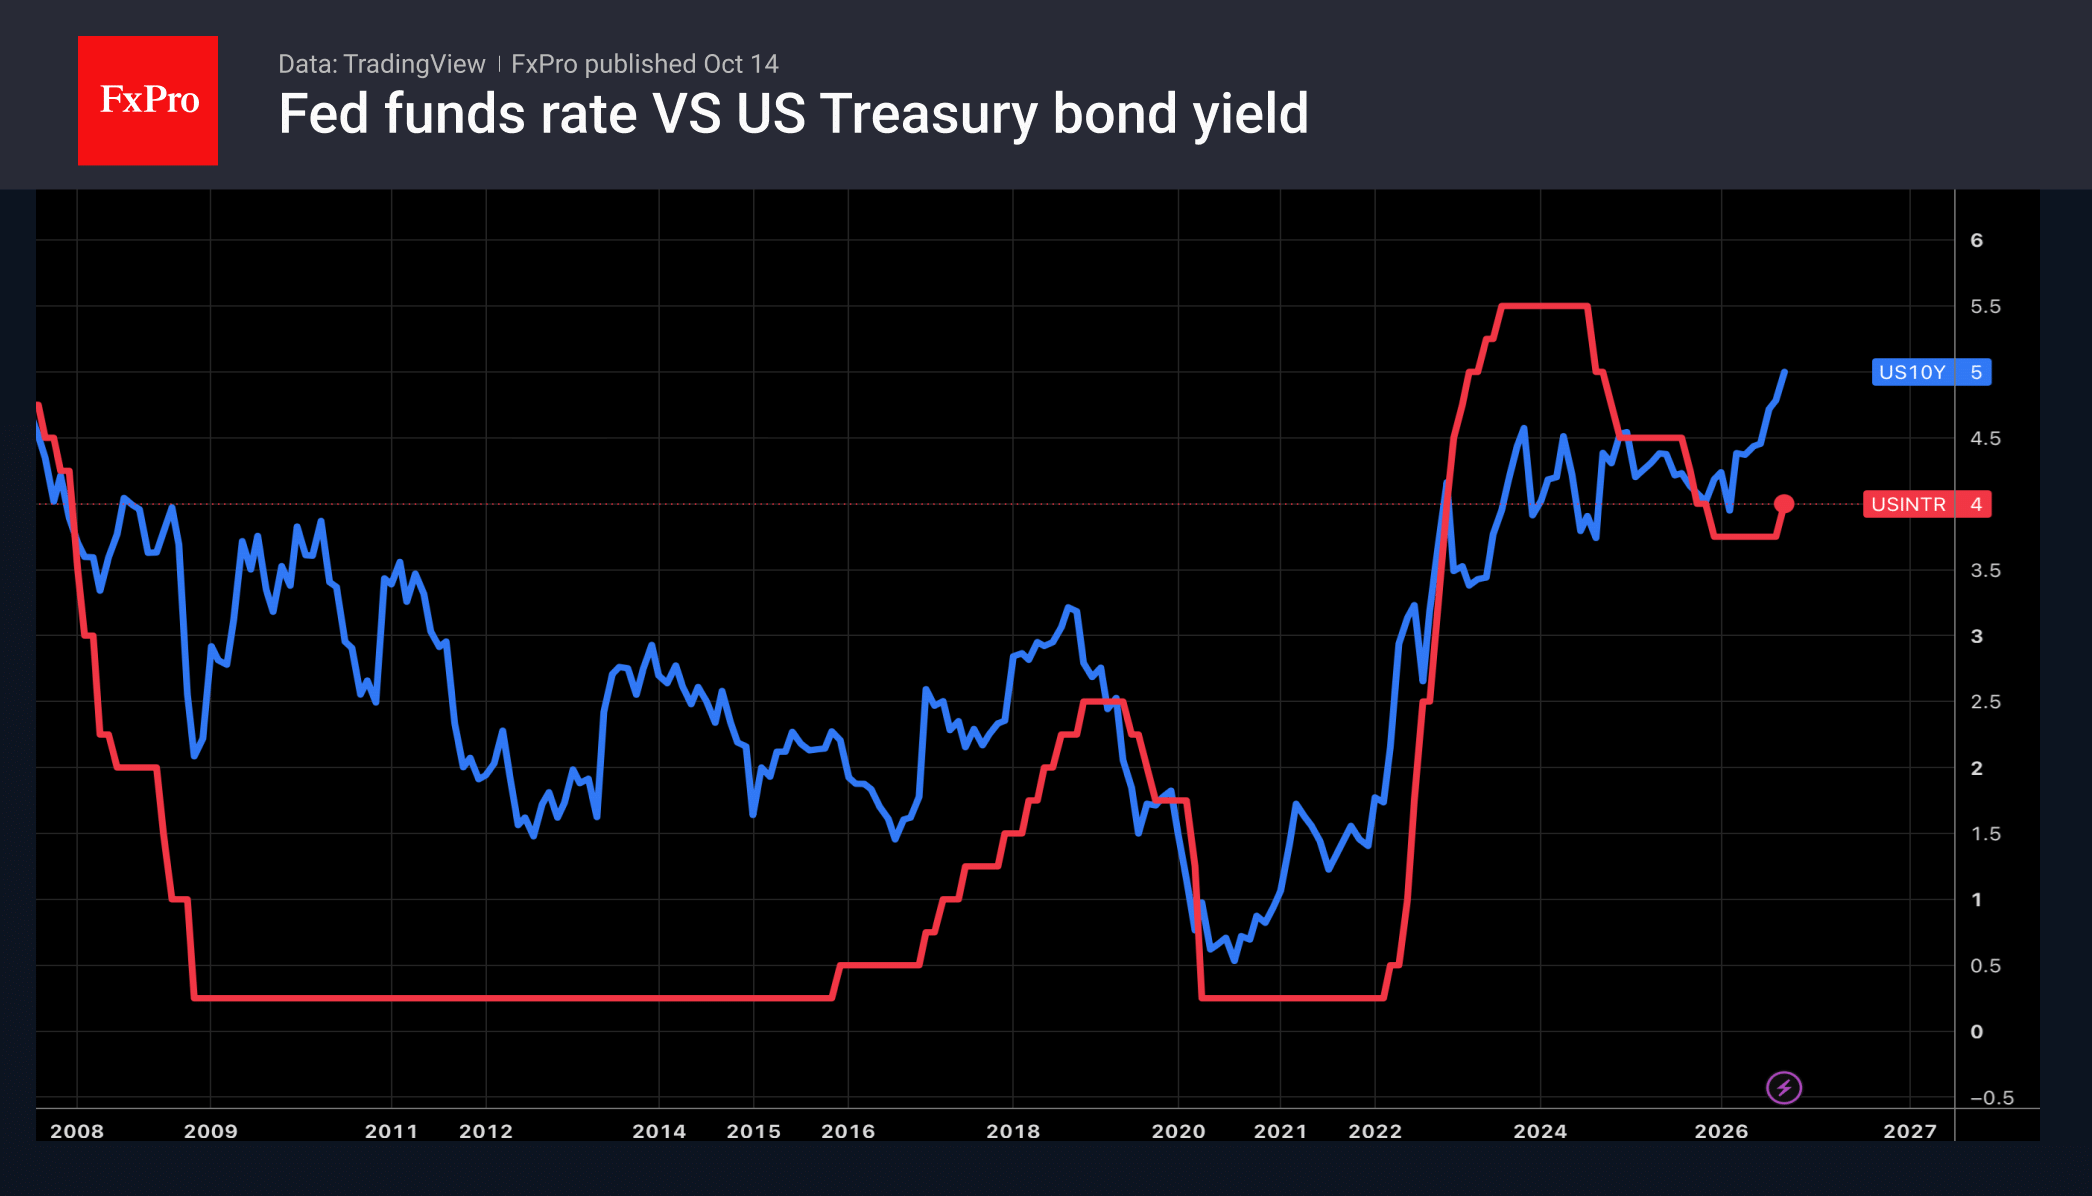
However, the FOMC’s doves are reluctant to raise rates aggressively, as core inflation shows no sign of accelerating alongside consumer prices, while the postponed IPOs of Australian AI infrastructure companies AirTrunk and Firmus Grid are casting a shadow over semiconductor manufacturers.
High interest rates, stretched valuations and doubts about the ability to generate profits that justify the colossal investments are fuelling caution and a desire to take profits in big tech. According to Broadcom’s CEO, Hock Tan, investors have no idea what they are investing in, and betting on the sector is akin to gambling in a casino.
If competition from technology companies for resources eases, Treasury yields will fall even further, dampening the appetite for the dollar. That said, should this be followed by a slump in the S&P 500, it would drive up demand for safe-haven assets and provide support for the greenback. The difference will be determined by the intensity of these processes: a gradual weakening of the dollar is considered the best-case scenario for global equity markets, but this ideal balance is rarely sustained to the end. Far more often, we see a sharp strengthening of the dollar triggering a fall in share prices or, conversely, a sell-off in shares reviving the notion of short-term Treasuries as a safe haven, thereby fuelling the dollar’s rise.
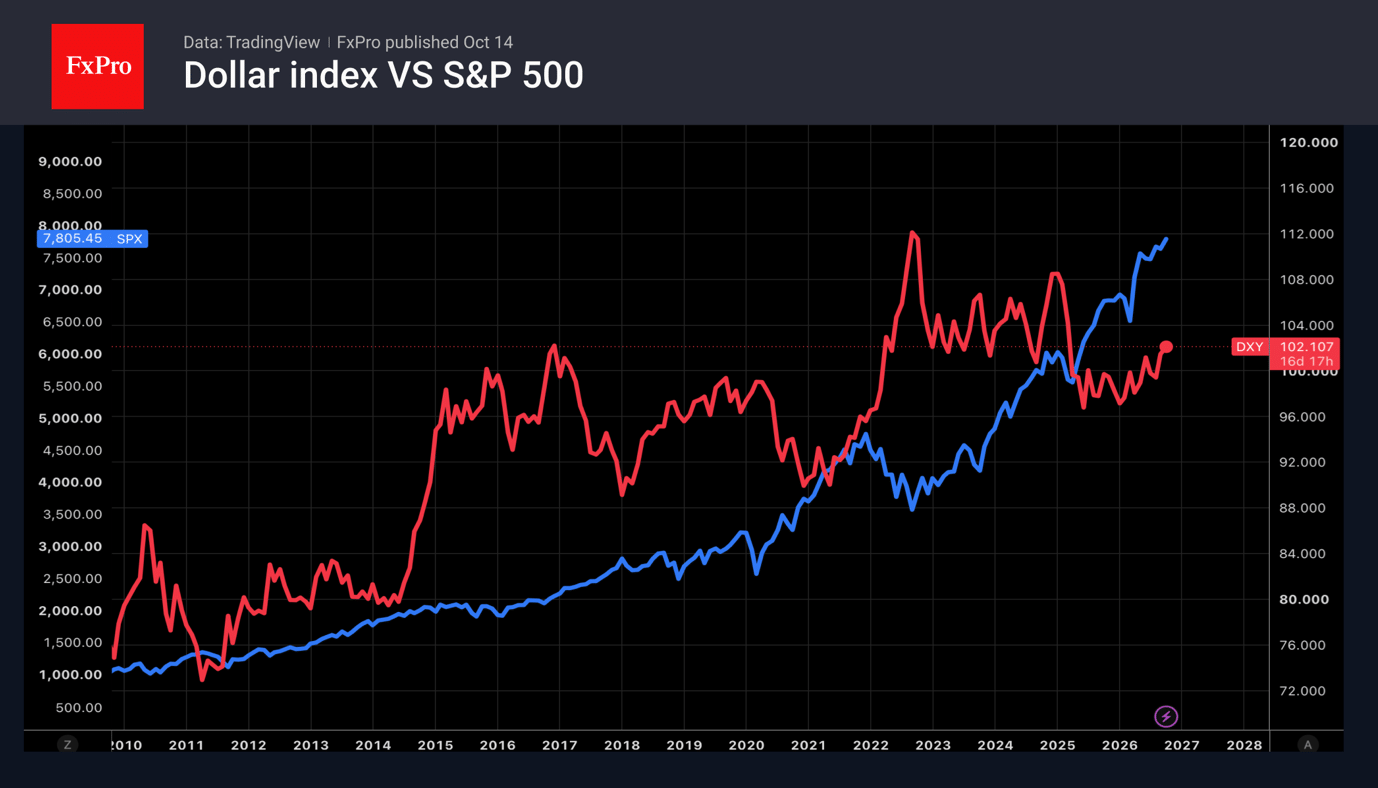
The yen has not yet been able to capitalise on the dollar’s pullback. According to a Bloomberg insider, Bank of Japan officials are not keen to raise rates at two consecutive meetings, as they see no signs of inflation spiralling out of control. The futures market puts the probability of the BoJ tightening monetary policy in October at 10%, and in December at 88%.
Traders are eagerly awaiting US inflation data. So far, forecasts of accelerating inflation have not led to speculative buying of the US dollar. If this is the case, only significant deviations in the CPI from expectations will trigger sharp movements in the USD index.
The FxPro Analyst Team