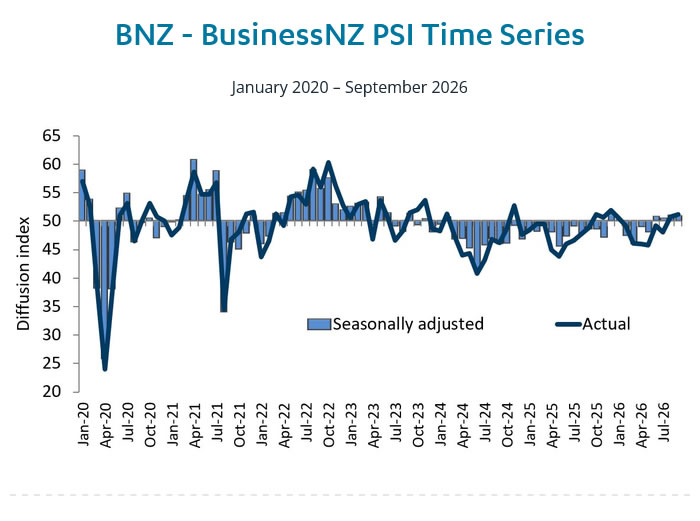
New Zealand’s BNZ–BusinessNZ PMI Services edged down from a revised 51.0 in August to 50.9 in September, remaining marginally above the 50-point expansion threshold. The reading suggests that the services sector is continuing to stabilize, although the pace of growth is weak. The modest expansion also contrasts with the much stronger manufacturing performance, where PMI Manufacturing rose from 53.3 to 56.5 in September.
The underlying components revealed a mixed picture. New Orders/Business stood at 52.6, suggesting a firmer pipeline of demand, while Activity/Sales barely remained in expansion at 50.2. Stocks/Inventories registered 52.3, but Employment stayed in contraction at 49.8, alongside Supplier Deliveries at 49.4. BNZ highlighted elevated fuel prices and constrained household spending as significant pressures, particularly in retail, which recorded the weakest industry reading at 47.4. The divergence between new orders and current activity suggests that demand has yet to translate into a more convincing improvement in services output.
Despite the subdued services performance, the combined manufacturing and services composite index rose to 51.6 in September, providing support for expectations of moderate economic growth toward year-end. However, the contrast between stronger manufacturing activity and sluggish services conditions underscores the uneven nature of the improvement. A more convincing recovery would require stronger activity and a sustained return to employment growth, rather than expansion driven primarily by new business.
Data Summary
Headline Indicators
| Indicator | Aug | Sep |
|---|---|---|
| PMI Services | 51.0 | 50.9 |
| PMI Manufacturing | 53.3 | 56.5 |
PSI Components and Composite
| Indicator | Sep |
|---|---|
| Activity/Sales | 50.2 |
| New Orders/Business | 52.6 |
| Stocks/Inventories | 52.3 |
| Employment | 49.8 |
| Supplier Deliveries | 49.4 |
| Composite PCI | 51.6 |
Source: BNZ–BusinessNZ September 2026 PSI.
Key Takeaways
- Services expansion remains fragile: PMI Services eased from a revised 51.0 to 50.9, only marginally above the 50-point threshold separating expansion from contraction.
- New orders offer encouragement, but activity lags: New Orders/Business at 52.6 was the strongest subindex reading since June, while Activity/Sales barely expanded at 50.2. Improving demand has yet to translate into stronger services activity.
- Employment continues to constrain the recovery: Employment at 49.8 remained below 50. BNZ also identified elevated fuel prices and constrained household spending as pressures on the sector, with retail particularly weak at 47.4.
- Manufacturing is substantially stronger than services: PMI Manufacturing climbed to 56.5, while the combined composite index reached 51.6. This supports a picture of moderate economic growth, although the divergence between sectors highlights an uneven recovery.