


Eurozone private-sector growth moderated in October, with PMI Composite falling from 53.1 to 51.9, its lowest level in four months. PMI Manufacturing eased from 52.9 to 52.4, while PMI Services declined from 53.0 to 51.7, both missing expectations. France was the principal source of weakness, with PMI Composite plunging from 51.1 to 48.4 as both manufacturing and services returned to contraction. Germany remained in expansion, although PMI Composite also slowed from 53.8 to 52.8. German PMI Manufacturing improved from 53.9 to 54.2, but PMI Services weakened from 52.9 to 51.7.
Underlying demand conditions also softened, with new orders increasing at their slowest pace in the current four-month expansion and employment virtually stalling. Services hiring slowed to a five-month low, while manufacturing employment declined slightly. Business confidence fell to its lowest since May, with political uncertainty and disruptions from strikes and unrest contributing to particularly weak conditions in France. S&P Global noted that French business confidence had deteriorated to its lowest since 2012, excluding the pandemic period. The contrast with continued growth in Germany highlights the increasingly uneven nature of Eurozone economic activity.
Meanwhile, manufacturing input cost inflation accelerated to its fastest pace since May, driven partly by higher energy, fuel and transportation costs. Supplier delivery times lengthened at their fastest rate in four months, while manufacturers increased purchasing activity and accumulated input inventories. However, selling-price inflation moderated across the Eurozone, indicating that stronger upstream cost pressures were not translating into faster increases in final charges overall. The combination of slower output growth, subdued hiring and rising industrial costs presents a less favorable outlook for the start of Q4, although continued expansion suggests that the broader Eurozone economy remains resilient despite France’s renewed downturn.
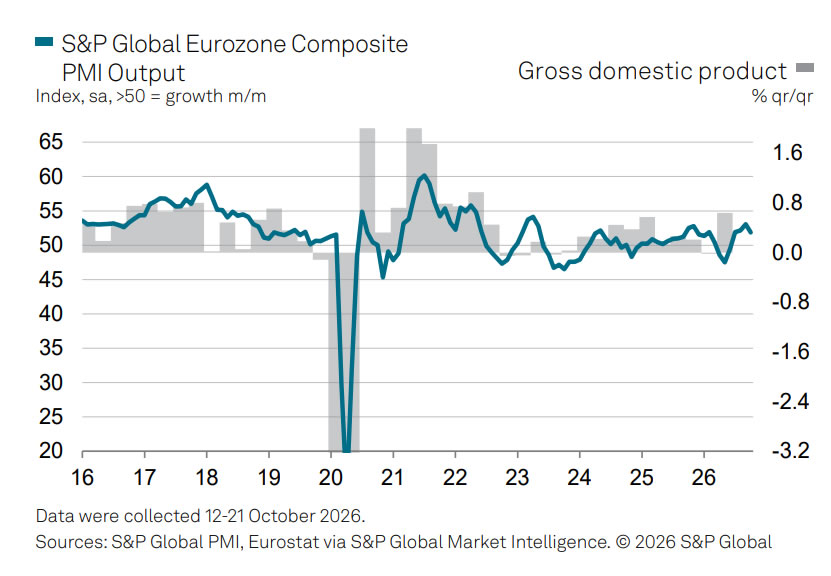
Data Summary
Eurozone Flash PMI
| Indicator | Previous | Expected | Current |
|---|---|---|---|
| PMI Composite | 53.1 | — | 51.9 |
| PMI Manufacturing | 52.9 | 52.7 | 52.4 |
| PMI Services | 53.0 | 52.6 | 51.7 |
| Manufacturing Output | 53.6 | — | 52.4 |
Germany Flash PMI
| Indicator | Previous | Expected | Current |
|---|---|---|---|
| PMI Composite | 53.8 | — | 52.8 |
| PMI Manufacturing | 53.9 | 53.5 | 54.2 |
| PMI Services | 52.9 | 52.5 | 51.7 |
| Manufacturing Output | 56.0 | — | 55.1 |
France Flash PMI
| Indicator | Previous | Expected | Current |
|---|---|---|---|
| PMI Composite | 51.1 | — | 48.4 |
| PMI Manufacturing | 50.6 | 50.5 | 49.3 |
| PMI Services | 51.2 | 50.7 | 48.4 |
| Manufacturing Output | 50.3 | — | 48.5 |
Readings above 50 indicate expansion, while readings below 50 indicate contraction. Survey responses were collected October 12–21.
Additional Survey Details
| Indicator | October Development |
|---|---|
| Eurozone Private-Sector Output | Fourth consecutive expansion, slowest in four months |
| New Orders | Slowest growth in four months |
| New Export Orders | Third consecutive increase, but slower growth |
| Overall Employment | Broadly unchanged |
| Services Employment | Slowest hiring growth in five months |
| Manufacturing Employment | Slight decline |
| Backlogs of Work | Little changed |
| Manufacturing Input Costs | Fastest inflation since May |
| Supplier Delivery Times | Largest deterioration in four months |
| Manufacturing Input Purchases | Joint-fastest growth in almost four and a half years |
| Manufacturing Stocks of Purchases | First increase in almost four years |
| Selling Price Inflation | Slowed overall |
| Eurozone Business Confidence | Lowest in five months |
| France Business Confidence | Lowest since 2012, excluding the pandemic period, according to S&P Global |
Key Takeaways
- Eurozone growth slows to a four-month low: PMI Composite declined from 53.1 to 51.9 as PMI Manufacturing eased from 52.9 to 52.4 and PMI Services from 53.0 to 51.7. Both sectoral headline indices missed expectations, indicating weaker momentum at the start of Q4.
- France returns to contraction: France’s PMI Composite fell sharply from 51.1 to 48.4, reversing September’s brief expansion. Both PMI Manufacturing and PMI Services dropped below 50, highlighting weakness across the private sector.
- Germany remains relatively resilient: PMI Composite moderated from 53.8 to 52.8, while PMI Manufacturing improved from 53.9 to 54.2. However, PMI Services weakened to 51.7, and manufacturing output growth also slowed, indicating that German expansion was not uniformly strengthening.
- France’s political uncertainty weighs on confidence: S&P Global identified strikes and unrest as potential disruptions to activity, while political instability contributed to exceptionally weak business confidence. France’s deterioration was a major source of the Eurozone slowdown.
- Demand and employment momentum weaken: Eurozone new orders increased at their slowest pace in four months, while employment was virtually unchanged. Services hiring slowed to a five-month low, and manufacturing employment declined slightly.
- Manufacturing inflation pressures intensify: Input costs rose at their fastest pace since May, driven partly by higher energy, fuel and transportation costs. Supplier delivery times deteriorated further, while businesses increased purchases and accumulated input inventories.
- Selling price inflation moves in the opposite direction: Despite stronger manufacturing input inflation, overall selling-price inflation slowed. This suggests that rising production costs were not translating into faster price increases charged to customers across the Eurozone.
- Growth outlook becomes more uneven: The Eurozone continues expanding, but France’s renewed contraction, slower demand growth and near-stagnant employment point to increasing vulnerabilities. Persistent industrial cost pressures add another complication, even as selling-price inflation moderates.





