- The Federal Reserve is on the cusp of beginning a cycle of rate rises.
- The USD index rally will continue if the central bank surprises markets.
The US dollar has paused its rise following four consecutive sessions of gains ahead of the FOMC meeting’s outcome. The futures market now puts the probability of a federal funds rate hike at 92%, up from 61% a week earlier, and this reassessment of expectations for the upcoming meeting and several subsequent ones has been the main driver behind the US currency’s rise. The probability of at least two rate rises in 2026 is 78%, and of three is 28%. For the dollar index to continue its rally, the Fed must push these expectations even higher by surprising investors. This could happen either in the Committee’s updated forecasts or during Kevin Warsh’s press conference.
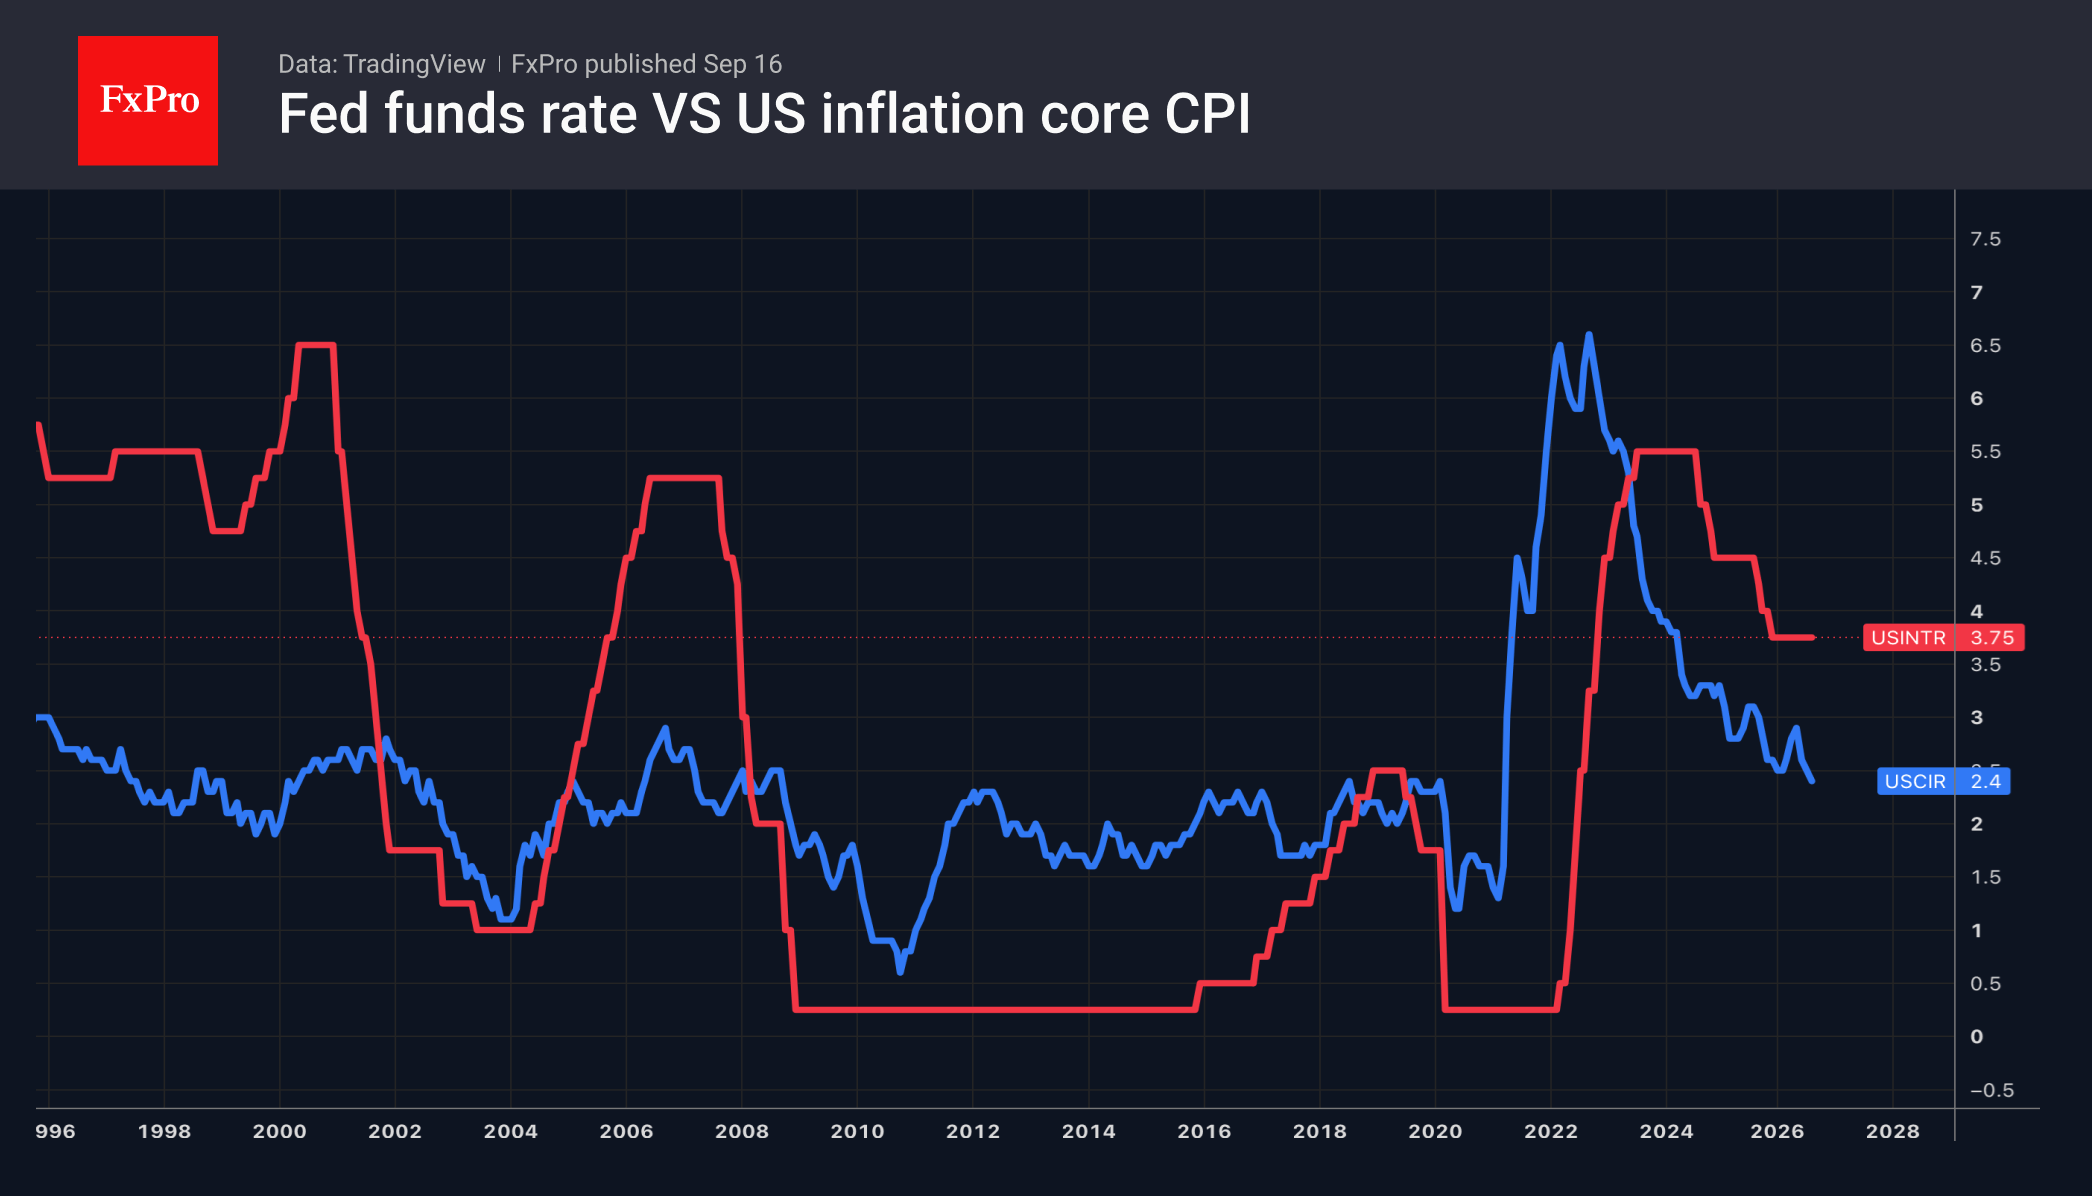
The White House is urging the central bank not to raise rates, pointing to the lowest core inflation figures since 2021. However, the rapid rally in energy prices, a strong labour market, and a robust economy are increasing upside price risks and pushing the Fed towards tightening monetary policy. A single federal funds rate hike will do little to slow inflation. Monetary tightening takes effect with a time lag; moreover, many FOMC officials describe current policy settings as insufficiently restrictive.
Most likely, the focus will be on the start of a rate-hiking cycle, so the market is naturally asking: how far is the Fed prepared to go to bring inflation back to its 2% target? Currently, the market’s central scenario is for a 100-basis-point hike over the coming months, with a probability of a bit over 56%. Any deviation from this outlook will fuel volatility. The only question is the direction. Investors will look for clues to answer this in the updated rate forecasts and in Kevin Warsh’s comments.
Keeping the federal funds rate at its current level of 3.75% or raising it to 4%, with no signals of a continuation of the tightening cycle, will weaken the US dollar. We consider the current valuations justified, but see potential for the dollar to weaken as the likelihood of tightening by more than a full percentage point diminishes. Furthermore, Warsh may well warn that rate cuts could follow more swiftly than the Fed has done in the past.
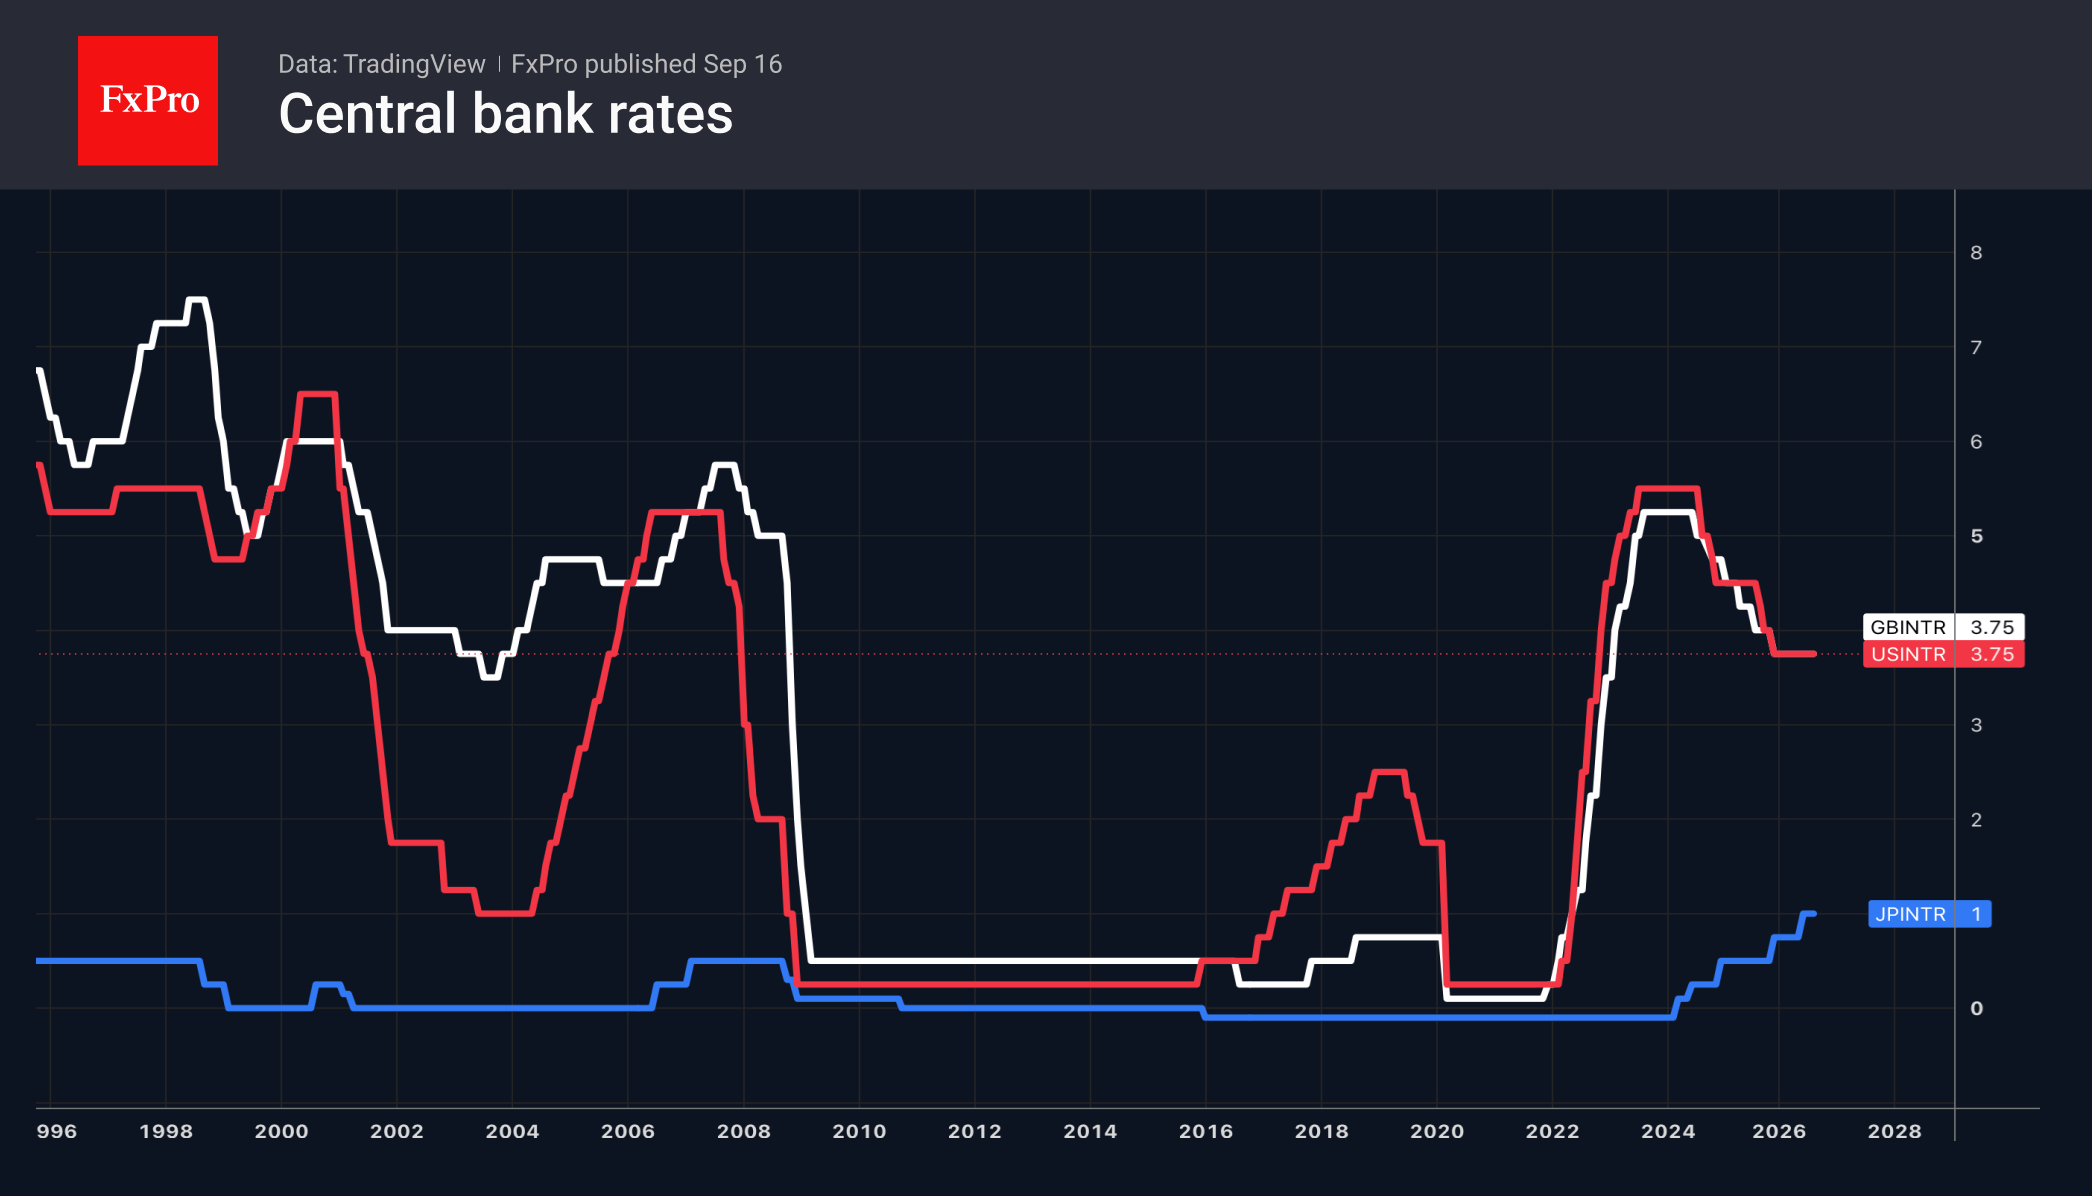
Following the Fed, the Bank of England and the Bank of Japan will announce their interest rate decisions. Investors do not expect a rise in the repo rate. Still, they do forecast the BoE to deliver the most aggressive monetary-tightening cycle over the next 12 months compared with other central banks. If Andrew Bailey abandons his ‘hawkish’ rhetoric, it will be a blow to the pound.
The yen has moved cautiously as the BoJ shows willingness to continue its cycle of monetary tightening. An overnight rate hike would be the third in the last 10 months. It has not risen this rapidly since 1990, when Japan was seen as a rival to US global economic dominance.
The FxPro Analyst Team