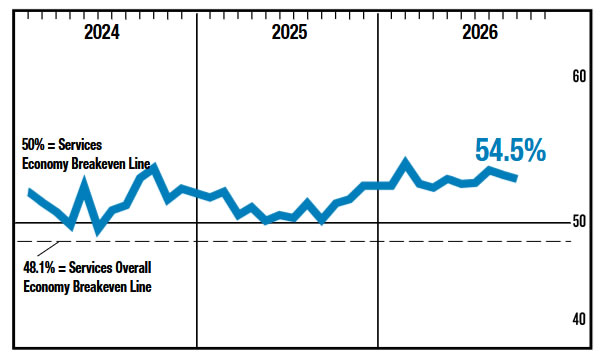
US services sector growth moderated in October, with ISM Services PMI declining from 54.9 to 54.5, below market expectations of 54.8. Nevertheless, the index remained in expansion territory for the 28th consecutive month. The underlying demand indicators showed a more pronounced slowdown than the headline reading suggested. Business Activity fell from 56.5 to 53.8, while New Orders dropped from 59.8 to 55.9, indicating that both output and incoming demand continued expanding but at a considerably slower pace. The decline in new orders was particularly notable, pointing to weaker demand momentum despite the sector’s continued expansion.
Employment provided a more encouraging signal, with the Employment Index rising from 50.1 to 51.4, marking a second consecutive month of expansion. However, only six services industries reported employment growth, suggesting that the improvement remained relatively limited. Other demand-related indicators were mixed. New Export Orders rebounded sharply from 46.9 to 55.2, returning to expansion, while Backlog of Orders increased from 56.6 to 58.0. Meanwhile, Supplier Deliveries rose from 53.2 to 56.7, indicating more widespread delivery delays. As this component contributes positively to the headline PMI, its increase helped offset the sharper declines in business activity and new orders, leaving the overall index relatively resilient despite weaker underlying demand momentum.
Price pressures eased slightly but remained elevated, with the Prices Paid Index declining from 74.0 to 73.0. The index nevertheless stayed above 70 for the seventh time in eight months, with 17 services industries reporting higher input prices. ISM identified continued increases in fuel-related products, metals, insurance, labour and software costs, while no commodities were reported as falling in price. Overall, the October survey suggests that US services activity continues expanding, supported by modest employment growth and improving export orders, but domestic demand momentum has weakened while input cost pressures remain persistent. The combination points to a still-growing services economy without clear evidence of accelerating underlying activity.
Data Summary
US ISM Services — October 2026
| Indicator | September | October |
|---|---|---|
| ISM Services PMI | 54.9 | 54.5 |
| Market Consensus | — | 54.8 |
ISM Services PMI remained in expansion territory for the 28th consecutive month, despite falling below market expectations.
ISM Services — Key Components
| Component | September | October |
|---|---|---|
| Business Activity | 56.5 | 53.8 |
| New Orders | 59.8 | 55.9 |
| Employment | 50.1 | 51.4 |
| Prices Paid | 74.0 | 73.0 |
| Supplier Deliveries | 53.2 | 56.7 |
| Backlog of Orders | 56.6 | 58.0 |
| New Export Orders | 46.9 | 55.2 |
| Imports | 52.9 | 54.2 |
| Inventories | 57.8 | 55.4 |
Component Trends
| Component | October Trend |
|---|---|
| Business Activity | Expansion slowed |
| New Orders | Expansion slowed sharply |
| Employment | Expansion strengthened |
| Prices Paid | Cost increases moderated slightly |
| Supplier Deliveries | Deliveries slowed more widely |
| Backlog of Orders | Growth accelerated |
| New Export Orders | Returned to expansion |
| Imports | Growth accelerated |
| Inventories | Growth moderated |
Key Takeaways
- Services growth slowed more than expected: ISM Services PMI declined from 54.9 to 54.5, missing the 54.8 consensus. The sector nevertheless continued expanding for a 28th consecutive month.
- Underlying demand weakened considerably: Business Activity fell from 56.5 to 53.8, while New Orders dropped from 59.8 to 55.9. Both remained above 50, but their declines suggest a more pronounced moderation than the headline PMI indicates.
- Employment improved for a second month: The Employment Index rose from 50.1 to 51.4, indicating slightly stronger hiring conditions. However, only six services industries reported employment growth, limiting the breadth of the improvement.
- Export orders rebounded sharply: New Export Orders jumped from 46.9 to 55.2, returning to expansion. Backlog of Orders also increased from 56.6 to 58.0, providing some offset to weaker overall new order growth.
- Supplier delays supported the headline PMI: Supplier Deliveries rose from 53.2 to 56.7, indicating more widespread delivery delays. Because this component contributes positively to the overall ISM Services PMI, its increase partly offset the sharp declines in business activity and new orders.
- Input price pressures remained elevated: Prices Paid eased from 74.0 to 73.0 but exceeded 70 for the seventh time in eight months. Seventeen services industries reported rising prices, suggesting that cost pressures remained widespread despite the modest moderation.
- The overall picture remains mixed: Services activity continues expanding, supported by improving employment and export demand. However, slower business activity and new orders indicate weakening underlying demand momentum, while elevated input costs remain a concern.