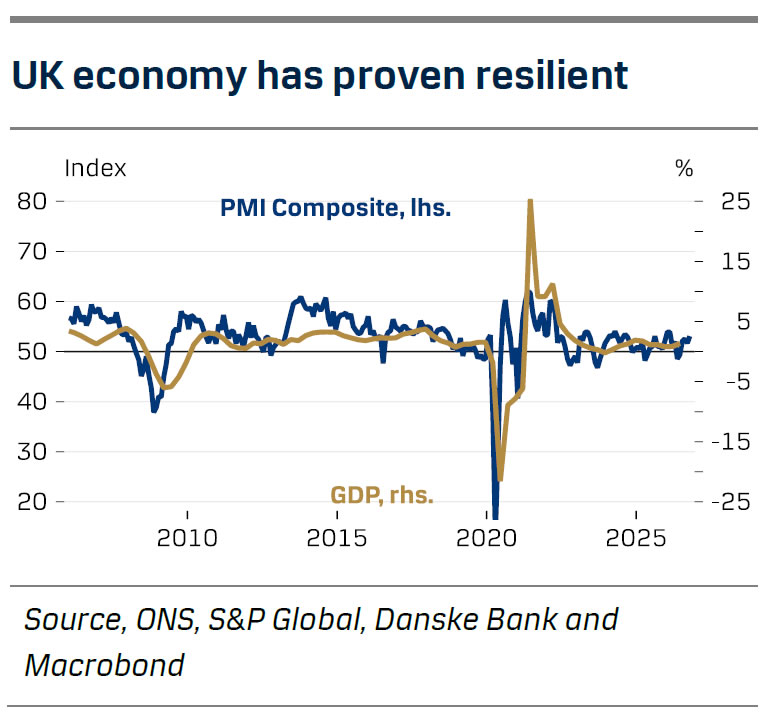
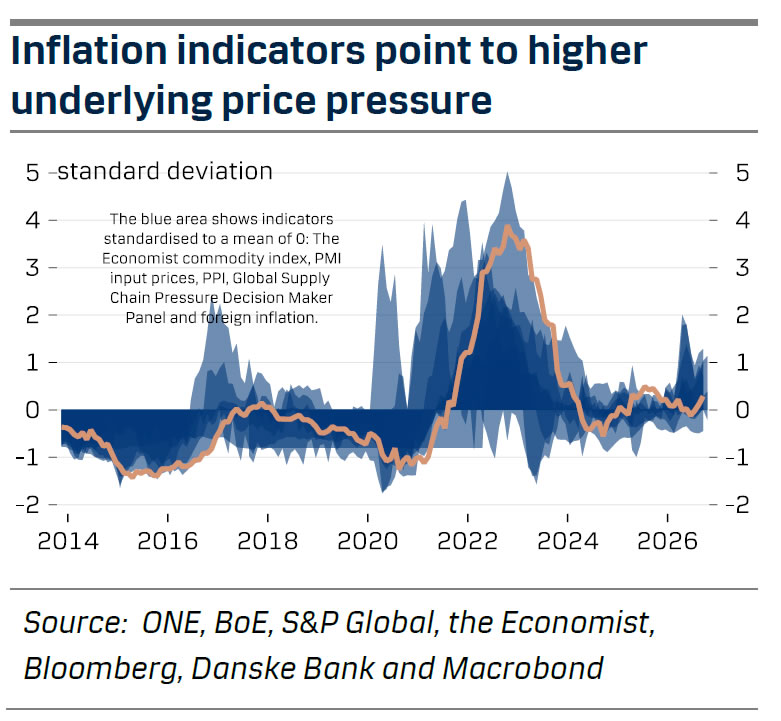
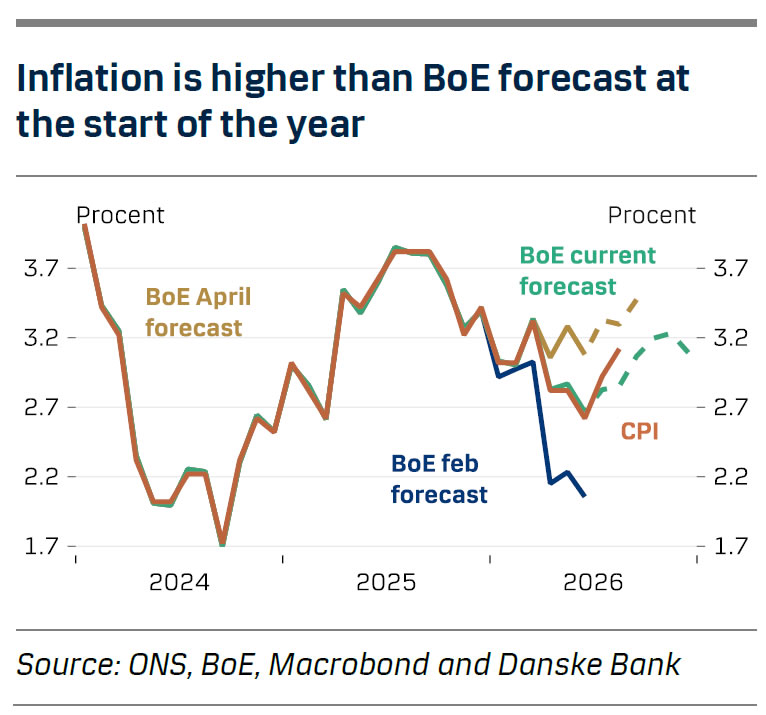
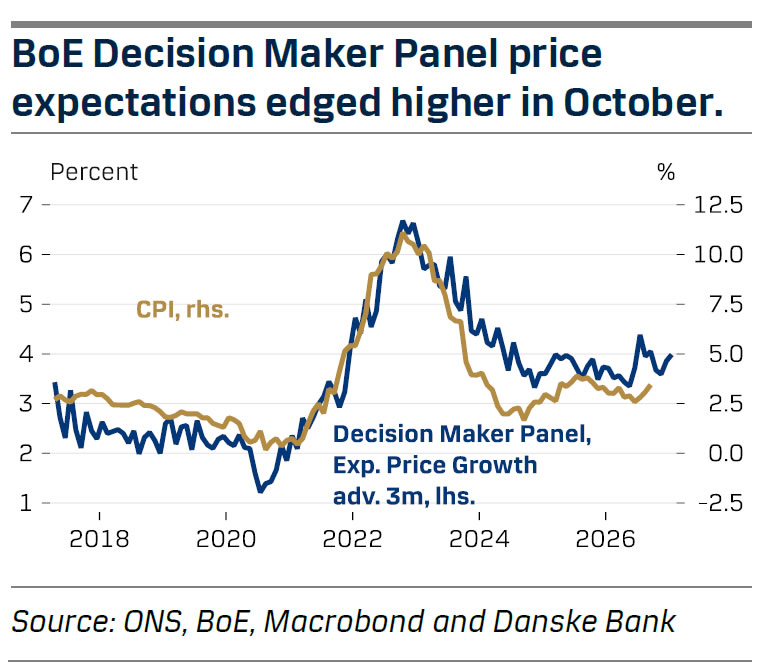
Growth has surprised to the upside, and official forecasters have raised their growth forecasts for this year while pencilling in a gloomier outlook for next year, as higher energy prices hit consumers and businesses. Despite significant domestic energy production, the UK remains a net importer, so higher energy prices pose a stagflation risk. Domestic production nevertheless reduces import dependence and provides a cushion when prices are high. At the beginning of the year, inflation was expected to fall back towards target, but it has since risen again, mainly because of higher energy prices following the war in the Middle East. Rate expectations have, like in other countries, shifted towards a new hiking cycle, which the BoE would enter from an already restrictive starting point, with the neutral rate estimated at around 3%.
Government borrowing costs have risen sharply, with 10-year gilt yields trading above 5%. The autumn budget was cautious and broadly in line with expectations, adding modestly to near-term borrowing without unsettling markets, while providing some support to businesses and households.
BoE call. The longer period that high energy prices persist, the greater the risk of second-round effects, and we expect the Bank of England to deliver a 25bp rate hike to 4.0% at the November meeting to contain inflation risks. Recent communication from MPC members has been hawkish and we expect a solid majority to vote for hike. Additional hikes cannot be ruled out, but market expectations shift rapidly, and the 100bp of tightening now priced in over the coming year is likely excessive. The BoE still has a lot working in its favour, with muted domestic wage pressure and anchored inflation expectations.
Market reaction. Given market pricing, the balance of risk is tilted towards a less hawkish stance which would leave some upside risk for EUR/GBP.