

Live Comments
US Jobless Claims Drop to 196k as Labor Market Resilience Continues
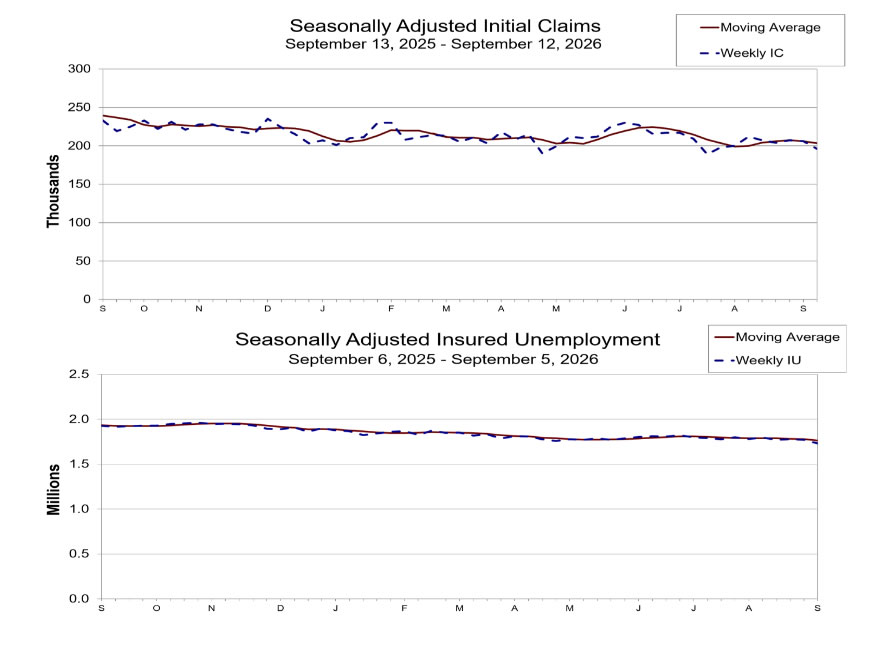
US initial jobless claims fell from 206k to 196k in the week ending September 12, substantially below the 209k expectation. The four-week moving average declined from 206k to 203.25k, indicating that the improvement was not limited to the latest weekly reading. Unadjusted claims dropped 13.9%, compared with the 9.3% decline anticipated by seasonal factors.
Continuing claims also fell sharply, from a downwardly revised 1.769m to 1.730m in the week ending September 5. The previous figure was initially reported at 1.774m. The four-week average of continuing claims declined from 1.778m to 1.761m, while the insured unemployment rate fell from 1.2% to 1.1%. Compared with a year earlier, initial claims were down from 233k and continuing claims from 1.925m.
The report points to limited new layoffs and a declining stock of workers receiving unemployment benefits. Weekly claims remain volatile, but the simultaneous improvement in initial claims, continuing claims and their moving averages provides a consistent signal of labor-market resilience. Coming one day after the Fed raised rates, the data offer policymakers little employment-based reason to abandon further tightening while inflation remains elevated.
Data summary
Headline data
| Indicator | Actual | Expected | Previous |
|---|---|---|---|
| Initial jobless claims | 196k | 209k | 206k |
Supporting claims data
| Indicator | Current | Previous | Change |
|---|---|---|---|
| Initial claims, four-week average | 203.25k | 206.00k | -2.75k |
| Continuing claims | 1.730m | 1.769m | -39k |
| Continuing claims, four-week average | 1.761m | 1.778m | -16.5k |
| Insured unemployment rate | 1.1% | 1.2% | -0.1pp |
| Unadjusted initial claims | 152.29k | 176.92k | -24.63k |
The previous continuing-claims reading was revised from 1.774m to 1.769m.
Key takeaways
- Initial claims fell from 206k to 196k, undershooting the 209k expectation by 13k.
- The four-week average declined to 203.25k, confirming that the improvement was not confined to one volatile weekly reading.
- Continuing claims dropped by 39k to 1.730m, while the insured unemployment rate declined from 1.2% to 1.1%.
- Unadjusted claims fell 13.9%, compared with the 9.3% decline anticipated by normal seasonal patterns.
- Initial claims were 233k in the comparable week of 2025, while continuing claims stood at 1.925m, indicating considerably lower benefit use than a year earlier.
- The simultaneous decline in new and continuing claims points to a resilient labor market and offers the Fed little employment-based reason to halt tightening after one hike.
- Weekly claims can be volatile, but the consistency across the headline, moving averages and insured unemployment strengthens the signal.
BoE Held Rates on 6-3 Vote, but Four More Policymakers are Moving Toward a Hike
The Bank of England left Bank Rate unchanged at 3.75% by a 6–3 vote, but the decision was less comfortable than the headline majority suggests. External MPC members Megan Greene and Catherine Mann, together with Chief Economist Huw Pill, again voted for an immediate 25bp increase to 4.00%. Within the hold camp, Bank of England Governor Andrew Bailey, Deputy Governor Sarah Breeden, Deputy Governor Clare Lombardelli and Deputy Governor Dave Ramsden all indicated that persistent energy pressure or growing second-round inflation risks could strengthen the case for tightening. That leaves the committee with a substantially broader hawkish tilt than the formal split alone implies.
The change in the inflation outlook was substantial. Since the July Monetary Policy Report, Brent crude and UK wholesale gas prices have risen 36% and 78%, respectively. The BoE now expects CPI inflation to reach around 3.75% in Q4, compared with 3.2% previously, before moving slightly above 4% in Q1 2027. There has been little evidence so far that the shock is spreading materially into wages and non-energy prices. However, the MPC warned that pass-through may have been delayed by corporate hedging, reserve drawdowns and margin compression rather than permanently avoided.
The six-member majority judged that existing restraint provided time to assess those second-round effects. UK financial conditions have already tightened sharply, with two-year fixed mortgage rates around 95bp higher than before the conflict and the OIS curve peaking near 4.9% by end-2027. Wage growth has moderated and the labour market retains some slack, but the protection provided by weak demand is becoming less certain. Q2 GDP grew 0.4%, July output rose another 0.4%, and the BoE raised its Q3 growth estimate from 0.1% to 0.4%. Bank of England Governor Andrew Bailey said persistent conflict and rising second-round risks would likely require policy to tighten, while other members of the hold majority also described the case for action as building.
The MPC separately voted unanimously to reduce its monetary-policy gilt portfolio to zero by September 2034. After setting aside GBP 120bn of gilts to back banknote issuance, the remaining GBP 368bn will be unwound at an average annual pace of GBP 46bn, including GBP 20bn of yearly active sales alongside maturities. For Bank Rate, the September decision represents a conditional hold rather than a neutral pause. The key question before the November 5 meeting is whether the projected rise above 4% begins affecting wage settlements, services prices and inflation expectations strongly enough to move additional members into the hike camp.
MPC member views in one line
Voted to hold Bank Rate at 3.75%
- Governor Andrew Bailey: Limited pass-through and soft employment justify waiting, but prolonged conflict and rising second-round risks would likely require tightening.
- Deputy Governor Sarah Breeden: Restrictive financial conditions provide time, but a larger and longer energy shock makes an eventual rate response increasingly likely.
- External MPC Member Swati Dhingra: Weak demand, economic slack and limited pass-through argue for waiting for clear evidence rather than tightening pre-emptively.
- Deputy Governor Clare Lombardelli: Financial conditions still restrain inflation, but delayed energy pass-through means the case for a hike is building as the conflict persists.
- Deputy Governor Dave Ramsden: Domestic inflation is currently benign, but resilient activity and accumulating external pressures could create a case for higher rates.
- External MPC Member Alan Taylor: Bank Rate and market rates are already restrictive, so policy should respond to demonstrated propagation rather than volatile headline energy prices.
Voted to raise Bank Rate to 4.00%
- External MPC Member Megan Greene: Economic slack may have peaked, and waiting for definitive second-round effects risks leaving policy behind the curve.
- External MPC Member Catherine Mann: Inflation above 4% during wage negotiations demands a preventive hike because financial conditions may not be restrictive enough.
- Chief Economist Huw Pill: An immediate hike would reinforce the inflation mandate and prevent energy, fiscal and global supply pressures from becoming embedded.
Practical committee map
- Immediate hikers: Greene, Mann and Pill.
- Conditional holders leaning toward action: Bailey, Breeden, Lombardelli and Ramsden.
- Evidence-first holders: Dhingra and Taylor.
This makes the committee look considerably more hawkish than a simple 6–3 hold. Another two members moving from the conditional group would produce a five-vote majority for a hike.
Key takeaways
- The BoE held Bank Rate at 3.75% by 6–3, with three members already supporting an immediate increase to 4.00%.
- Four of the six holders explicitly indicated that persistent energy pressure or emerging second-round effects could strengthen the case for tightening.
- The majority’s decision to wait rests on restrictive market rates, economic slack and the limited pass-through of energy costs into wages and broader prices.
- That protection may be weakening. The BoE upgraded Q3 growth from 0.1% to 0.4%, while employment indicators suggest that the expansion in slack may be stabilising.
- Inflation is expected to rise to approximately 3.75% in Q4 and slightly above 4% in Q1 2027, largely because of energy.
- The key divide is whether policymakers should act before second-round effects become visible. The three dissenters favour preventive risk management; Dhingra and Taylor want clearer evidence.
- The November 5 decision will depend less on headline CPI itself than on wages, services inflation, expectations and evidence of corporate cost pass-through.
- The unanimous QT decision will reduce the monetary-policy gilt portfolio by an average GBP 46bn annually, with completion planned for September 2034.
Eurozone CPI Finalized at 3.2%, but Services and Core Pressures Ease
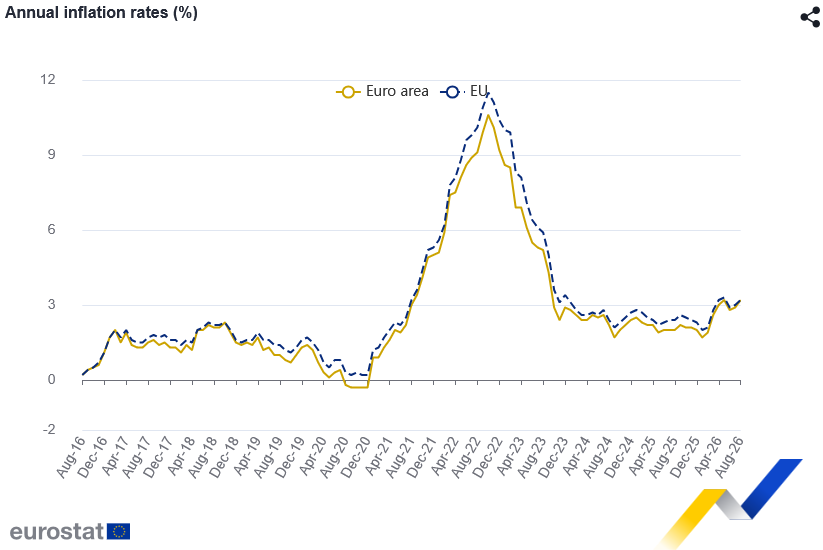
Eurozone annual CPI accelerated from 2.9% to 3.2% in August, while prices rose 0.4% m/m, according to Eurostat’s final estimate. The annual reading was revised below the preliminary estimate of 3.3%, while core inflation excluding energy, food, alcohol and tobacco eased from 2.5% to 2.4%. EU inflation also rose, from 3.0% to 3.2%.
The headline acceleration was overwhelmingly energy-driven. Energy inflation jumped from 10.3% to 14.3%, lifting its contribution to the headline rate from 0.94 to 1.29 percentage points. In contrast, services inflation slowed from 3.3% to 3.0%, and food, alcohol and tobacco inflation edged down from 1.2% to 1.1%. Non-energy industrial goods inflation increased from 0.9% to 1.2%, but contributed only 0.30 points. Inflation nevertheless became more geographically widespread, rising in 20 EU members, including increases from 2.8% to 2.9% in Germany, from 2.4% to 2.6% in France, from 2.9% to 3.2% in Italy and from 3.9% to 4.6% in Spain.
For the ECB, the composition argues against interpreting the rise above 3% as evidence of a broad resurgence in underlying inflation. Easing core and services rates suggest domestic pressure is moderating, while the headline increase reflects an external energy shock. However, the scale of the energy rise and its spread across member states increase the risk of second-round effects through wages, pricing decisions and inflation expectations. The policy significance will therefore depend less on the current headline rate than on whether higher energy costs begin reversing the improvement in services and core inflation.
Data summary
Headline readings
| Indicator | Actual | Expected / Flash | Previous |
|---|---|---|---|
| Eurozone HICP y/y | 3.2% | 3.3% | 2.9% |
| Eurozone core HICP y/y | 2.4% | 2.4% | 2.5% |
Additional readings
| Indicator | August | July |
|---|---|---|
| Eurozone HICP m/m | 0.4% | — |
| EU HICP y/y | 3.2% | 3.0% |
| Eurozone HICP excluding energy | 2.1% | 2.2% |
| Eurozone HICP excluding energy and unprocessed food | 2.1% | 2.2% |
Eurozone inflation components
| Component | August rate | July rate | August contribution |
|---|---|---|---|
| Energy | 14.3% | 10.3% | 1.29pp |
| Services | 3.0% | 3.3% | 1.43pp |
| Food, alcohol and tobacco | 1.1% | 1.2% | 0.22pp |
| Non-energy industrial goods | 1.2% | 0.9% | 0.30pp |
Selected national inflation rates
| Country | August | July |
|---|---|---|
| Germany | 2.9% | 2.8% |
| France | 2.6% | 2.4% |
| Italy | 3.2% | 2.9% |
| Spain | 4.6% | 3.9% |
Key takeaways
- Eurozone headline inflation accelerated from 2.9% to 3.2%, but was revised below the 3.3% flash estimate.
- Core inflation eased from 2.5% to 2.4%, matching expectations and pointing to softer underlying pressure.
- Energy drove the headline increase. Its annual rate jumped from 10.3% to 14.3%, contributing 1.29 percentage points to overall inflation.
- Services inflation slowed from 3.3% to 3.0%, an important counterweight to the energy shock.
- Inflation rose in 20 EU members, suggesting that the headline pressure was becoming geographically broader even as Eurozone core inflation eased.
- The data do not yet show a generalized second-round inflation cycle. For the ECB, the key question is whether higher energy costs begin feeding into services, wages and expectations.