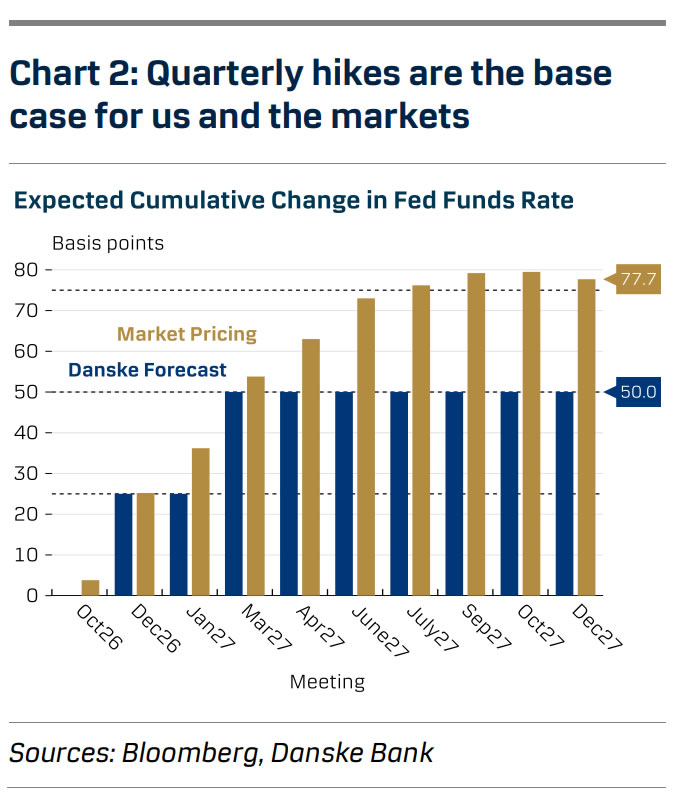
- We expect the Federal Reserve to keep policy rates unchanged at the October meeting, in line with consensus. Markets price in a 15-25% probability of a hike.
- Most central FOMC members have signalled they can wait until December before hiking again, though a few see more urgency. We expect 2-3 votes for a hike.
- We expect the FOMC to hike rates gradually, with 25bp in December 2026 and March 2027, and risks skewed towards more hikes. EUR/USD could tick modestly higher, and UST curve could steepen on Wednesday evening, but in 6-12M horizon, we forecast EUR/USD declining to 1.10
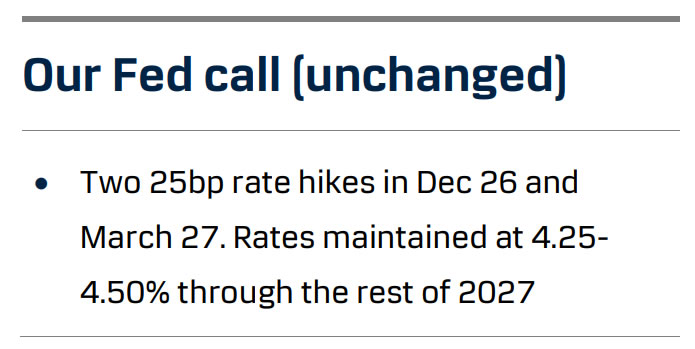
The Fed began its hiking cycle with a 25bp hike at the September meeting, but we expect rates to stay unchanged next week and hikes to resume in December. The September dots showed most participants favouring only one more hike in 2026.
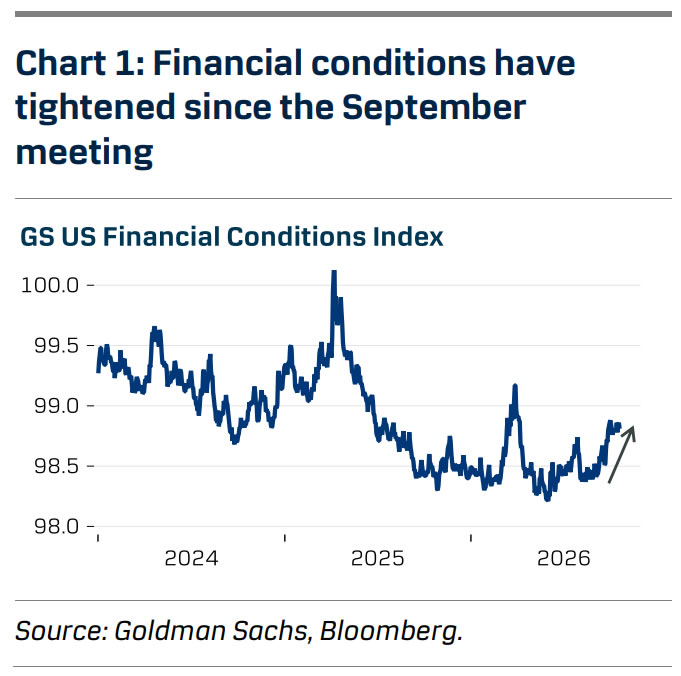
Although Chair Warsh has offered limited guidance, Vice-Chairs Williams, Jefferson and Bowman all have signalled they want more data before hiking again. In our view, their key argument is that financial conditions have tightened notably since September. If Warsh agrees, only a few more voters need to back no change for rates to stay unchanged. Waller sees more hikes ahead but is flexible on timing, while Kashkari said only one more hike is needed in 2026, though said before latest CPI release.
We think further tightening will be needed. Therefore, we stick with our call for two more hikes later, in December and March. Recent upside inflation surprises have mainly reflected higher energy prices, which the Fed should look through, but core inflation has edged up slightly. Downside risks to the labour market are limited and the growth outlook is strong. Atlanta Fed’s nowcast points to Q3 GDP growth of 3.5% q/q SAAR, supported by strong consumption and investment growth. These components are seen by the Fed as a better gauge of underlying growth momentum than real GDP itself.
A few voting members, especially Hammack and Logan, have called for more urgency in monetary tightening. We think they could dissent and vote for a hike, as they did in July. The remaining voters, Barr, Cook and Paulson, have taken a more neutral stance and have not discussed the timing of hikes. Powell has not communicated since stepping down as chair.
If the Fed keeps rates unchanged, and Warsh sticks with his limited guidance approach, UST yields could come marginally lower, and the curve could re-steepen. Holding rates steady now would strengthen the case for only quarterly hikes going forward. This is already largely reflected in current pricing but would reduce the perceived likelihood of a hike also in January. EUR/USD could shift modestly higher, but as long as Warsh underscores the commitment to price stability, we would view any uptick as temporary. We forecast EUR/USD heading towards 1.10 in 6-12M horizon.