Germany’s economic outlook showed a marked divergence in September between improving current conditions and largely unchanged expectations. The ZEW Indicator of Economic Sentiment edged from 34.2 to 34.7, falling well short of the 42.5 market forecast. By contrast, the Current Situation Index jumped from -61.1 to -47.1, beating expectations of -53.0. The 14-point improvement suggests that present conditions are becoming less negative, but the modest rise in expectations shows that confidence in a sustained recovery has not strengthened alongside them.
ZEW President Professor Achim Wambach, PhD said Germany’s recovery continued to be supported by fiscal measures and export momentum. However, persistently high energy prices linked to the continuing war in Iran and uncertainty surrounding hybrid attacks were weighing on the outlook. The sector breakdown was similarly uneven. The insurance indicator rose 12.1 points to 46.4, while banking sentiment increased 8.2 points to 52.9, reflecting benefits from higher interest rates. In contrast, steel and metal manufacturing stayed at -16.7, and the automotive sector remained particularly weak at -22.6.
The Eurozone delivered an even clearer warning on forward confidence. Its Current Situation Index improved from -21.5 to -13.9, but Economic Sentiment fell from 31.4 to 25.8, compared with expectations for an increase to 39.5. The combined picture points to near-term stabilization without a convincing improvement in the outlook: current conditions are recovering from deeply negative levels, but energy costs, geopolitical risks and persistent weakness in major industrial sectors are preventing that improvement from developing into broader confidence.
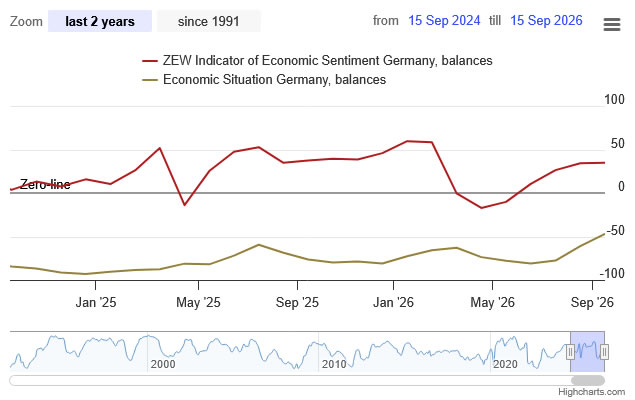
Data Summary
| Indicator | September | Expected | August |
|---|---|---|---|
| Germany Economic Sentiment | 34.7 | 42.5 | 34.2 |
| Germany Current Situation | -47.1 | -53.0 | -61.1 |
| Eurozone Economic Sentiment | 25.8 | 39.5 | 31.4 |
Additional Eurozone Indicator
| Indicator | September | August |
|---|---|---|
| Eurozone Current Situation | -13.9 | -21.5 |
Key Takeaways
- Germany’s Current Situation Index jumped 14 points from -61.1 to -47.1, beating expectations and showing that present conditions were becoming less negative.
- Germany’s Economic Sentiment Index increased only marginally from 34.2 to 34.7, substantially undershooting the 42.5 forecast.
- Eurozone expectations moved in the opposite direction, falling from 31.4 to 25.8 instead of rising as forecast.
- The Eurozone’s Current Situation Index nevertheless improved by 7.6 points to -13.9, reinforcing the divergence between better present conditions and weaker forward confidence.
- ZEW attributed Germany’s support to fiscal measures and export momentum, while high energy prices and geopolitical uncertainty continued to constrain the outlook.
- Higher interest rates benefited financial industries: banking sentiment rose to 52.9, while insurance reached 46.4.
- Germany’s industrial sector remained weak, with steel and metal manufacturing at -16.7 and automotive sentiment at -22.6.
- The overall picture points to near-term stabilization rather than a convincing economic recovery.