New Zealand’s BNZ–BusinessNZ Performance of Services Index (PSI) rose from 50.9 in September to 51.7 in October, reaching its highest level since 2023 and signaling a further strengthening in services activity. The improvement was driven primarily by Activity/Sales, which climbed from 50.4 to 52.6, while New Orders/Business increased from 52.5 to 53.0. The stronger activity reading suggests that earlier gains in new orders are beginning to translate into actual business activity, providing encouraging evidence that the services expansion is gaining traction following a prolonged period of weakness.
However, the improvement has yet to translate into meaningful employment growth. The Employment subindex edged up from 49.8 to 49.9, remaining just below the 50 expansion threshold and pointing to broadly stagnant hiring. Weakness also persisted in discretionary consumer services, with cultural, recreational and personal activities under pressure, while retail trade remained subdued despite October’s school holidays. These divergences suggest that the recovery in services demand is still uneven, with businesses experiencing stronger activity without a corresponding improvement in staffing or consumer-facing sectors.
The broader economic picture was also more constructive. The GDP-weighted BNZ–BusinessNZ Performance of Composite Index (PCI), combining manufacturing and services, rose from 51.5 to 52.2, while the free-weighted measure edged up from 53.3 to 53.4. Both manufacturing and services components remained in expansion territory, indicating that improving services activity is contributing to a wider pickup in business conditions. Nevertheless, the contrast between stronger activity and stagnant employment suggests that the expansion is not yet translating into broad-based economic momentum.
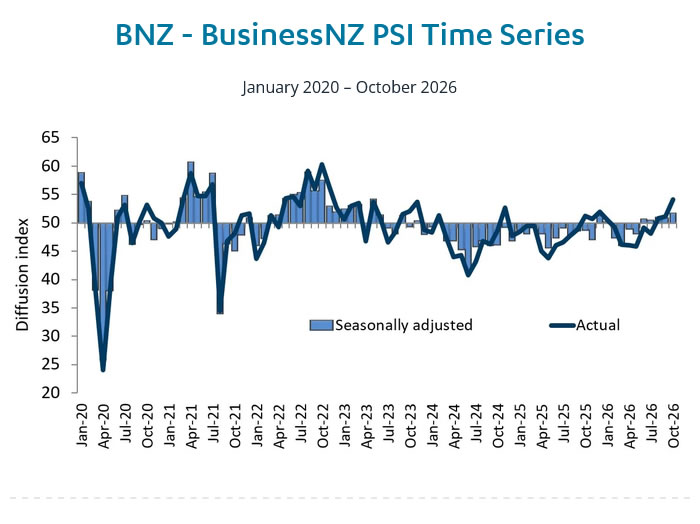
Data Summary — NZ PSI (October 2026)
| Indicator | Oct | Sep |
|---|---|---|
| PSI Headline | 51.7 | 50.9 |
| Activity/Sales | 52.6 | 50.4 |
| New Orders/Business | 53.0 | 52.5 |
| Employment | 49.9 | 49.8 |
| Stocks/Inventories | 50.1 | 52.1 |
| Supplier Deliveries | 52.1 | 49.5 |
Performance of Composite Index (PCI)
| Indicator | Oct | Sep |
|---|---|---|
| GDP-weighted PCI | 52.2 | 51.5 |
| Free-weighted PCI | 53.4 | 53.3 |
Key Takeaways
- Services expansion strengthens: PSI rose to 51.7, its highest since 2023, as stronger activity and new orders signaled improving business momentum.
- Employment and consumer demand lag: Hiring remained marginally in contraction, while discretionary services and retail activity continued to show weakness.
- Broader economy improves: The GDP-weighted composite index climbed to 52.2, indicating expanding manufacturing and services activity despite uneven recovery.