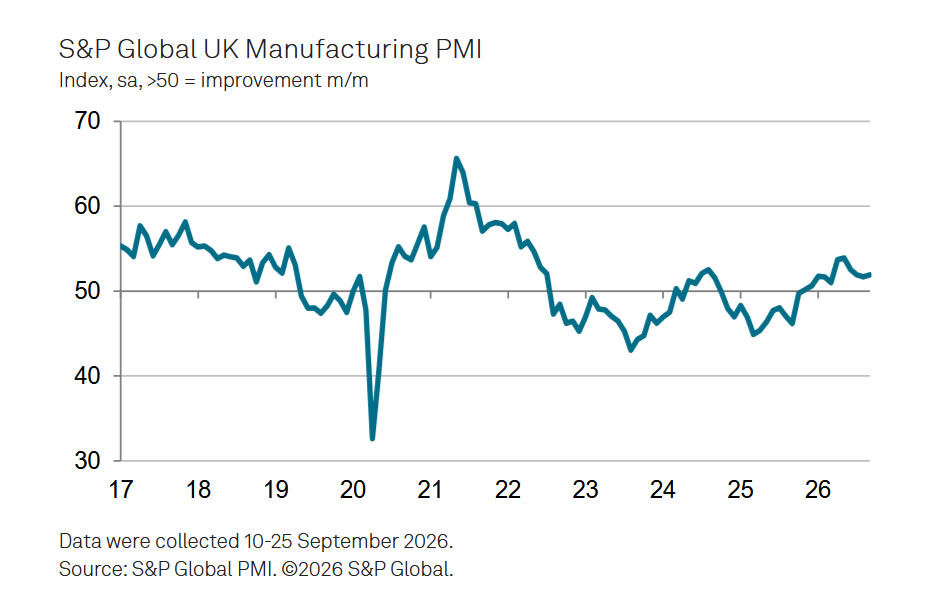
UK PMI Manufacturing rose from 51.7 to 51.9 in September, extending the sector’s expansion to an eleventh consecutive month. New orders increased for a tenth month and at a faster pace than in August, supported by both domestic and export demand, while employment rose for a sixth straight month and remained close to August’s two-year high. However, production growth slowed for a second consecutive month and was the weakest in the current six-month expansion sequence.
The recovery also remained uneven across industries and company sizes. Output growth was concentrated in investment goods, where production expanded at the fastest pace since the end of 2017, while consumer and intermediate goods both contracted. Small manufacturers also reported sharp declines in output and new business, contrasting with continued expansion among medium- and large-sized producers. Business sentiment remained positive, with 49% of firms expecting output to rise over the coming year, although confidence slipped from August’s six-month high.
The main shift came from inflation. Input-cost inflation accelerated for the first time in four months, driven by higher chemicals, electronics, energy and food costs, alongside increased transport expenses linked partly to diesel prices. Manufacturers passed more of those costs on, with selling-price inflation also strengthening. S&P Global said this marked a move from easing inflation pressure to a “renewed uplift”, leaving UK manufacturing with a mixed profile of firmer orders and hiring, slower output growth and rebuilding cost pressure.
Data Summary
| Indicator | Current month | Previous month | Trend |
|---|---|---|---|
| PMI Manufacturing | 51.9 | 51.7 | Expansion for 11th consecutive month |
UK PMI Manufacturing edged higher from 51.7 to 51.9 in September, while remaining above the 50.0 no-change level for an eleventh straight month.
Components
| Component | Trend |
|---|---|
| Output | Expanded at the weakest pace in six months |
| New Orders | Rose for a 10th month, faster than in August |
| Export Orders | Increased across several overseas markets |
| Employment | Rose for a sixth month, near August’s two-year high |
| Backlogs | Increased for the second time in three months |
| Investment Goods Output | Fastest growth since late 2017 |
| Consumer Goods Output | Contracted |
| Intermediate Goods Output | Contracted |
| Supplier Delivery Times | Lengthened markedly |
| Input Prices | Inflation accelerated for the first time in four months |
| Output Prices | Inflation strengthened |
| Business Confidence | Positive, but below August’s six-month high |
The survey showed firmer orders and employment alongside weaker production momentum, while cost and selling-price inflation turned higher again.
Key Takeaways
- PMI Manufacturing rose from 51.7 to 51.9, extending the expansion to an eleventh consecutive month.
- New orders increased for a 10th straight month and at a faster pace than in August.
- Employment rose for a sixth consecutive month, with hiring remaining close to August’s two-year high.
- Output growth nevertheless slowed for a second month and was the weakest in the current six-month expansion sequence.
- The recovery remained uneven: investment-goods production grew at the fastest pace since late 2017, while consumer and intermediate goods contracted.
- Small manufacturers reported sharp declines in output and new business, contrasting with growth among medium and large firms.
- Supply-chain pressure remained visible as delivery times lengthened sharply amid port congestion, shipping delays and raw-material shortages.
- Input-cost inflation accelerated for the first time in four months, driven by chemicals, electronics, energy, food and transport costs.
- Selling-price inflation also strengthened as manufacturers passed through some of those higher costs.
- Overall, the report points to continued expansion, but with softer output momentum and renewed inflation pressure.