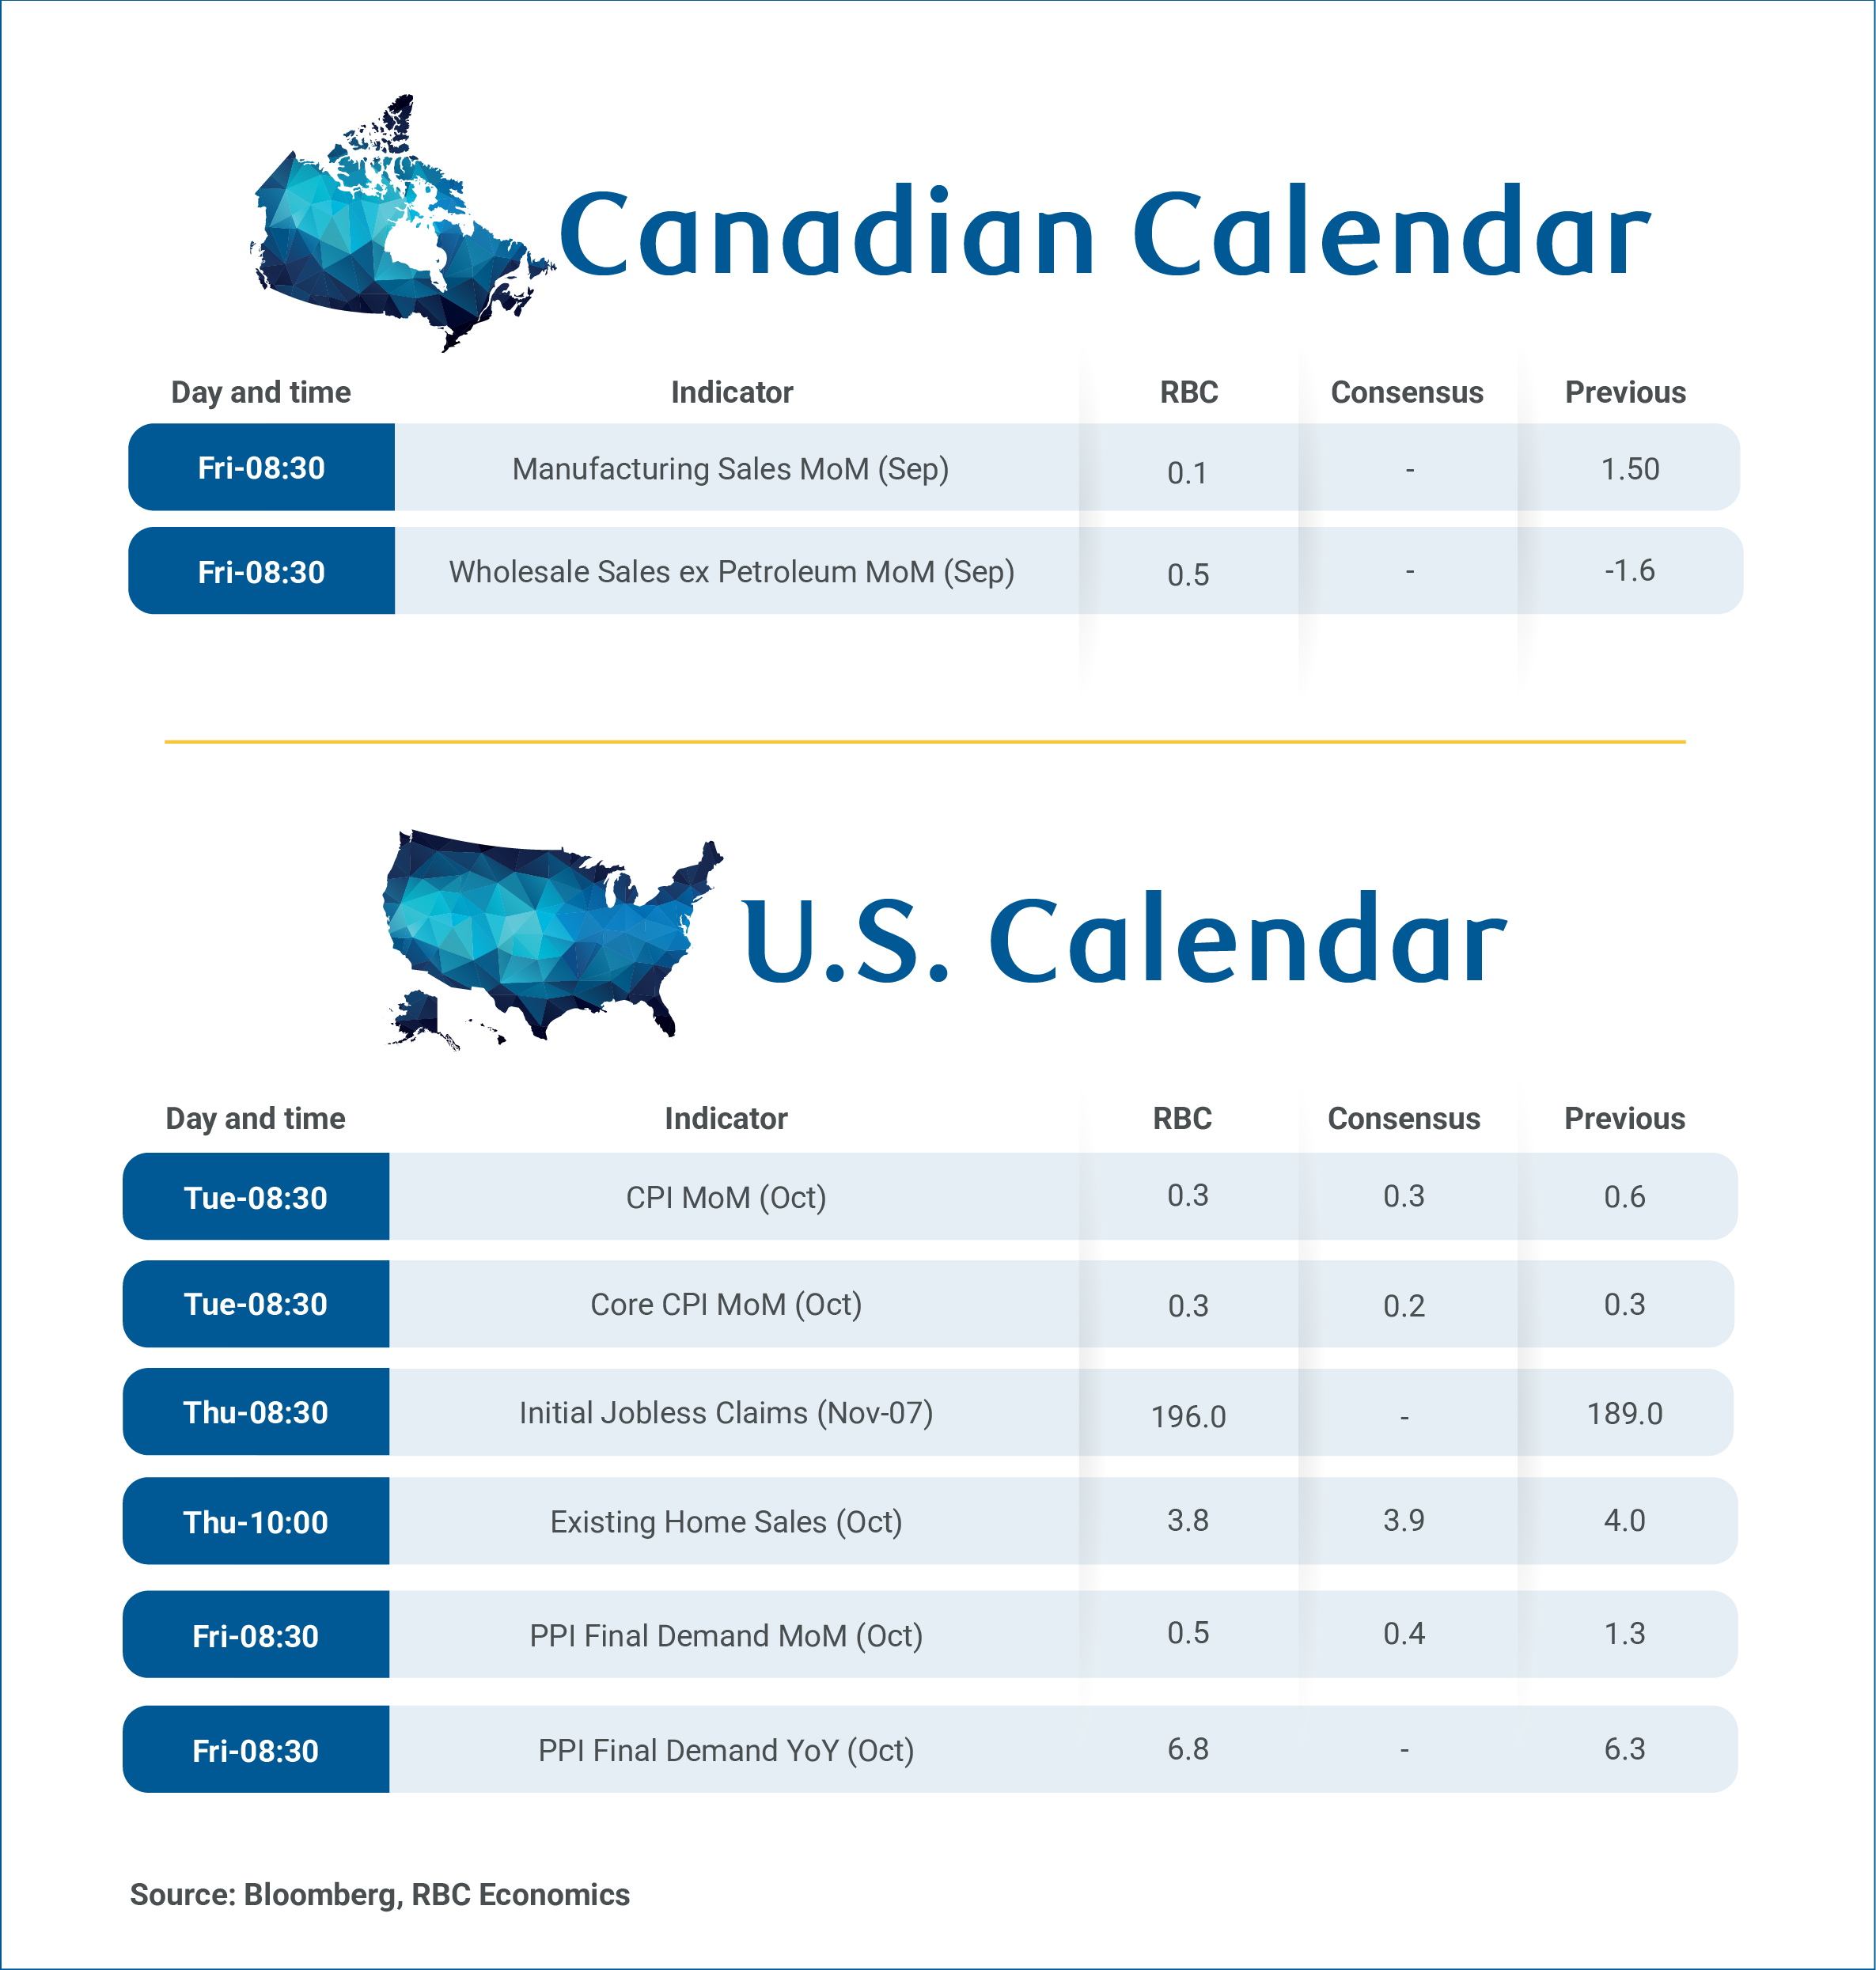
Canada’s manufacturing and wholesale sales reports for September next Friday should add to evidence that the economy grew less than expected in Q3.
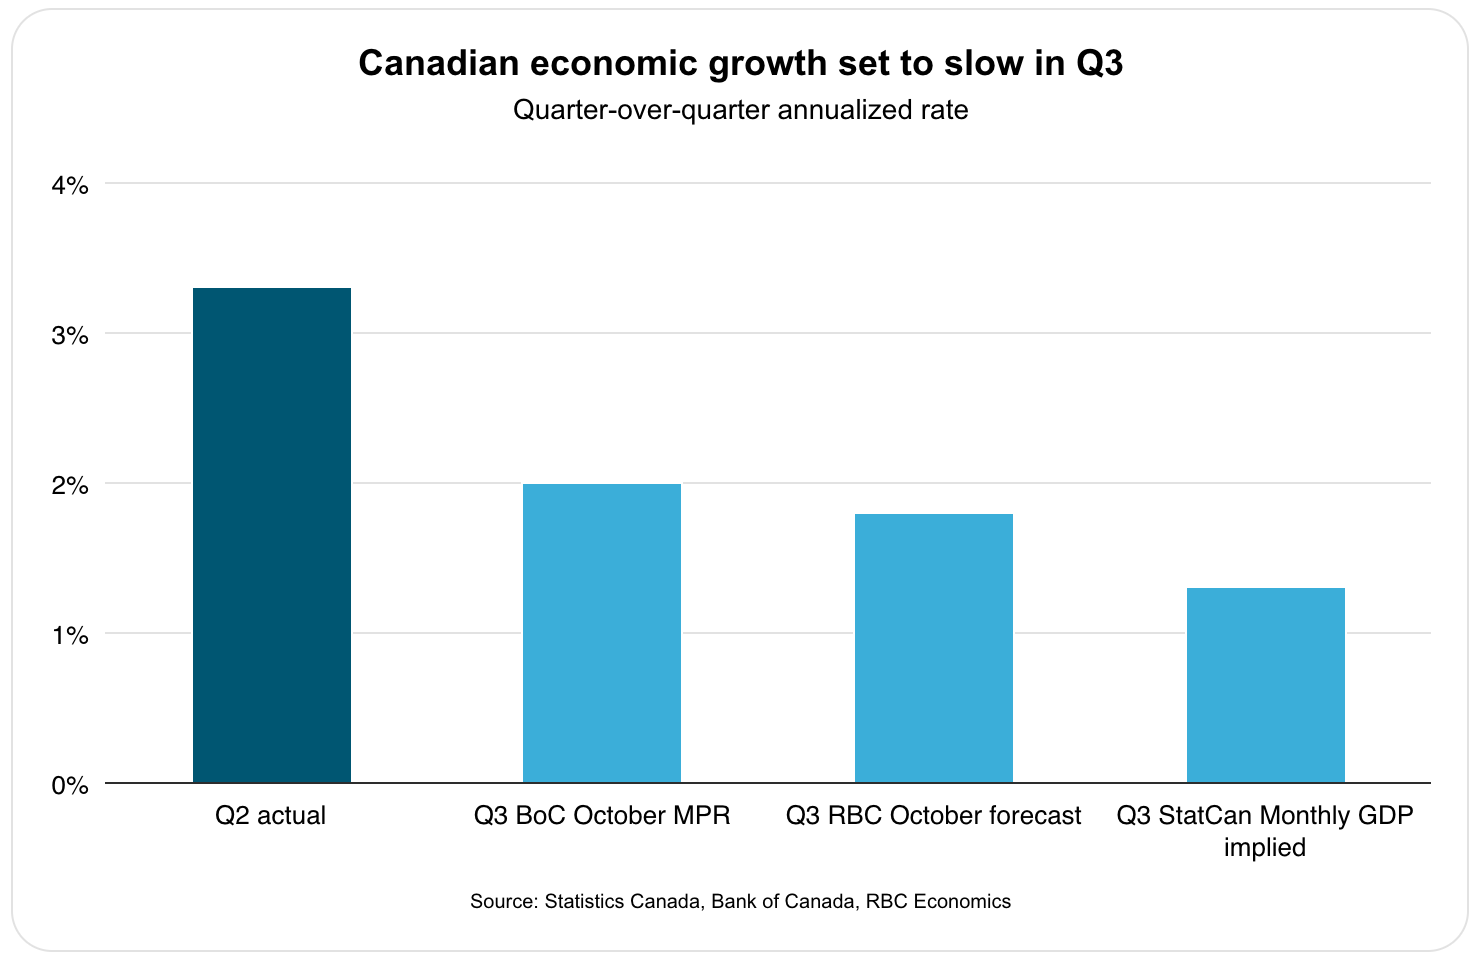
Gross domestic product growth has already flatlined in July and August, and likely contracted by 0.1% in September, according to Statistics Canada’s preliminary estimate. Preliminary GDP estimates have been highly prone to revision and need to be taken with a large grain of salt. Taking the September estimate as is would put annualized GDP growth in Q3 at around 1.3%.
The pace of growth is weaker than both our 1.8% base case forecast and the Bank of Canada’s estimate of 2% in its October Monetary Policy Report. It’s also significantly slower than the 3.3% expansion in Q2, although the slowdown was expected given that part of the Q2 strength reflected a one-time rebound in auto production and exports that won’t be repeated.
We expect the September manufacturing and wholesale reports will align with a mild contraction in real GDP. The advance estimate suggests nominal manufacturing sales rose 0.1%, which translates to 2% decline in volume once a 2.2% month-over-month increase in manufacturing producer prices is factored in (driven by a 16% increase in petroleum refinery prices).
Part of the pullback may also be related to unplanned production stoppages at U.S. auto plants that led to a sharp decline in cross-border auto trade in September.
Offsetting some of that weakness is an expected 0.5% increase in September’s wholesale sales (advance estimate ex-petroleum), reflecting strength in machinery, equipment, and supplies consistent with stronger imports in recent months.
Headline U.S. Consumer Price Index likely rose 0.3% in October from September, supported by another increase in core ex-food and energy components that extends the hotter readings seen in August and September. Gasoline prices changed little in the month but remain well above year-ago levels. Overall, persistent underlying inflation and broadening price pressures support our base case that expects another rate hike from the Fed at their December meeting, following a hike in September and a pause in October.