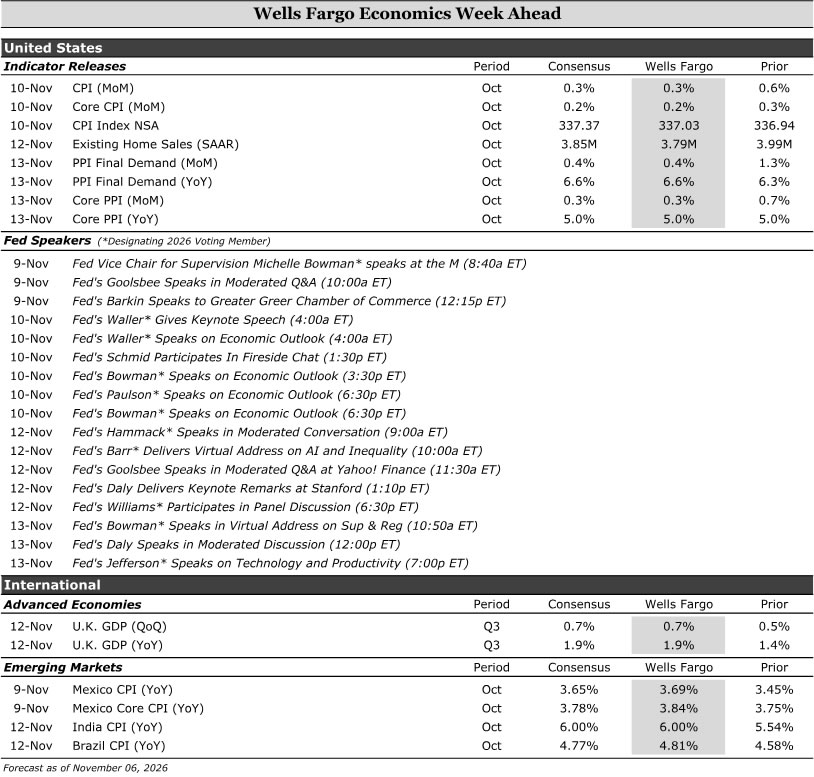
Next week, attention turns to Tuesday’s CPI report, with no year-over-year readings available because of last October’s shutdown-related data gap. We expect headline and core inflation to clock 0.28% and 0.21% month-over-month, respectively. Softer core inflation would offer some relief after September’s upside surprise but should still leave our call for a December rate hike intact. Housing remains under pressure, with existing home sales expected to fall 5.0% in October.
Abroad, UK Q3 GDP should post another firm reading, supported by business investment and AI-related spending. Inflation takes center stage in emerging markets, with prices expected to accelerate in Mexico, Brazil, and India. Persistent pressures should favor holds from Banxico and Brazil, while we have brought forward our expected Reserve Bank of India hike to December.
United States:
- CPI (Tue.), Existing Home Sales (Thu.)
Advanced Economies:
- U.K. GDP (Thu.)
Emerging Markets:
- Mexico CPI (Mon.), Brazil CPI (Thu.), India CPI (Thu.)
U.S. Week Ahead
CPI • Tuesday
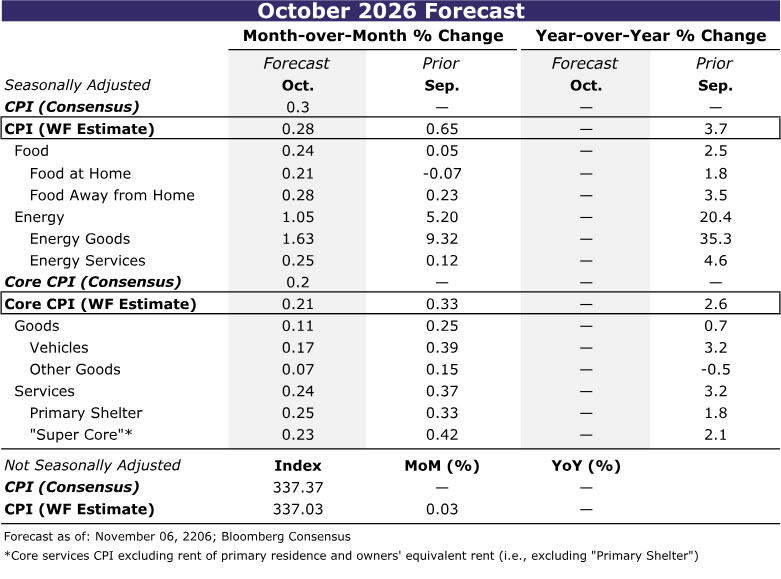
This month’s CPI report will be unique. Since the BLS did not collect price data in October 2025 amid the government shutdown, it will not publish year-over-year inflation rates this month, which will put an even bigger spotlight on the month-over-month changes. We estimate the headline CPI rose 0.28% in October. Gasoline inflation slowed following September’s sharp increase, while food inflation likely picked up as higher commodity and transportation costs gradually make their way into the grocery store.
We expect the core CPI to have risen 0.21%. Some of September’s more pronounced goods price increases, including in apparel and toys, are unlikely to have been repeated in October. This should drive a cooling in core goods inflation from 0.25% in September to 0.11% in October, the latter being roughly in line with its average monthly pace this year.
Within services, we look for primary shelter inflation to return to trend following September’s strong increase. Medical care services inflation should hold steady at last month’s pace, but we will be watching the health insurance line carefully since October is one of the semiannual periods in which the underlying source data is updated. Elsewhere, the recent strength in travel-related services is likely to fade after sharp increases in airfares and hotel prices in recent months. All told, we expect core services inflation to moderate to 0.24% in October.
A softer core reading would be welcome after September’s upside surprise, but it would do little to alter the broader picture of 2026 being a lost year for bringing core inflation back to 2%. We expect the report to reinforce the slow and uneven nature of the disinflationary process, underpinning our expectation for the FOMC to hike once more in December.
Existing Home Sales • Thursday
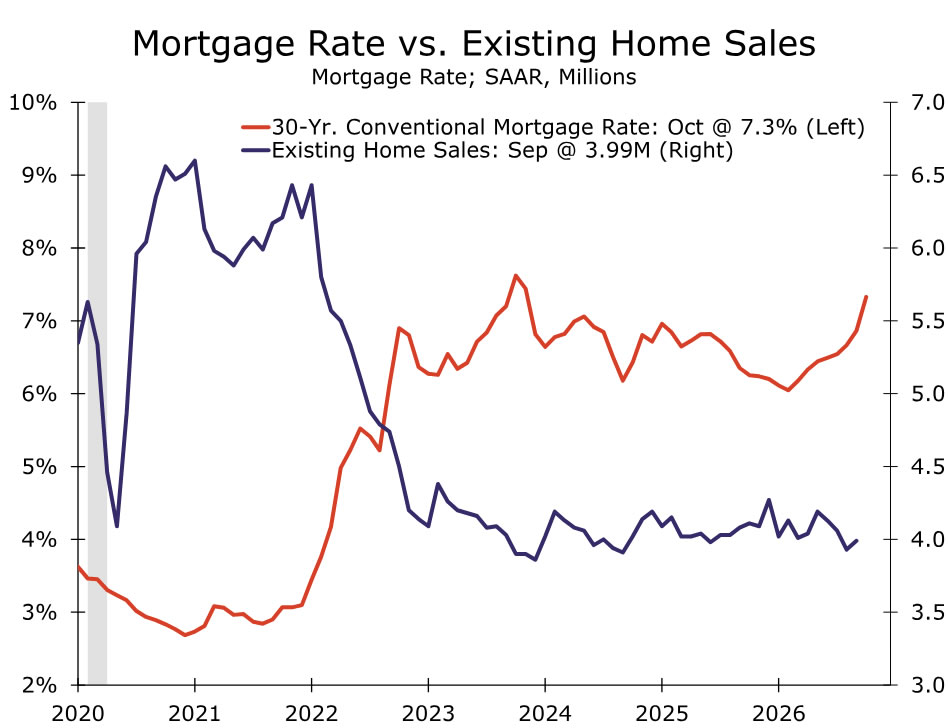
Affordability remains a formidable headwind for the housing market. Existing home sales rose modestly in September but remained weak at a 3.99 million annualized rate. We estimate that resales fell by 5.0% in October, pulling the pace down to 3.79 million. The average 30-year fixed mortgage rate reached 7.0% by the end of September, causing pending home sales to fall to the lowest level over the past 25 years. Supply growth has simultaneously slowed, spurring ongoing price increases on top of a cumulative 57% price hike since the pandemic.
Looking ahead, slightly lower economic growth expectations should put some downward pressure on mortgage rates, but the housing market is unlikely to break out of its anemic state any time soon.
Advanced Economies Week Ahead
U.K. GDP • Thursday
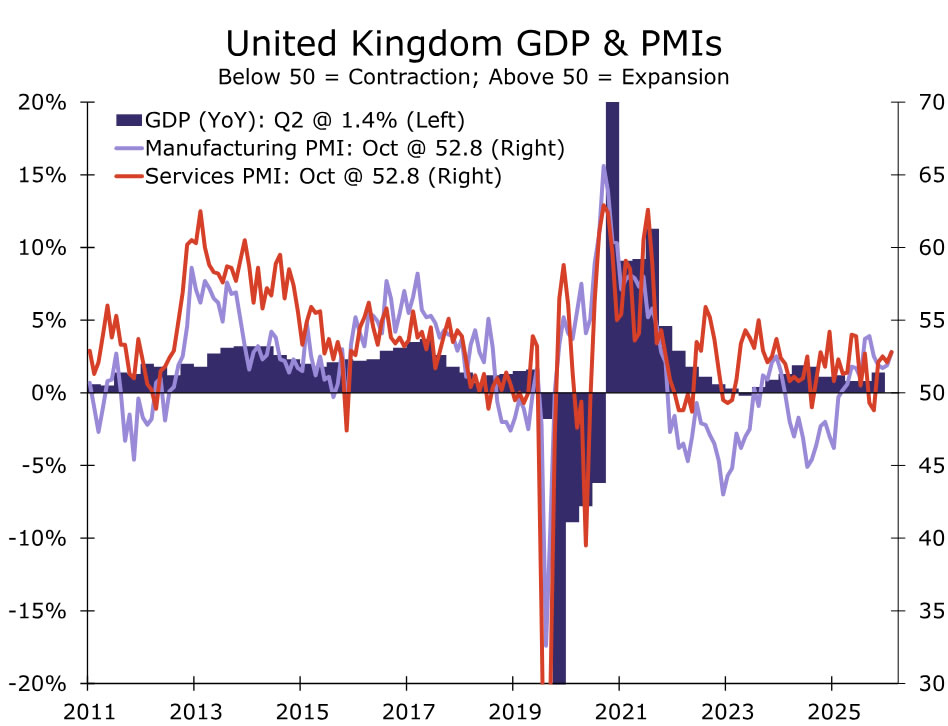
The UK economy looks set for another firm quarter despite higher energy costs and tighter financial conditions. Next week’s Q3 GDP release should show growth of 0.7% quarter-over-quarter and 1.9% year-over-year, with business services and investment spending providing much of the support. The breakdown and September’s monthly figures should offer a clearer picture of momentum heading into Q4. Survey data point to continued expansion through Q3, though momentum softened in September. Technology services and AI-related investment supported growth, while higher energy bills and mortgage rates weighed on consumption and consumer-facing services.
Resilient activity leaves policymakers less room to wait as inflation risks build. The BoE raised Bank Rate to 4.00% this week despite limited evidence of second-round effects, and now projects inflation to reach around 5% by mid-2027 as energy costs feed through. We continue to expect another hike in Q1 2027 to bring Bank Rate to 4.25%.
EM Week Ahead
Mexico CPI • Monday
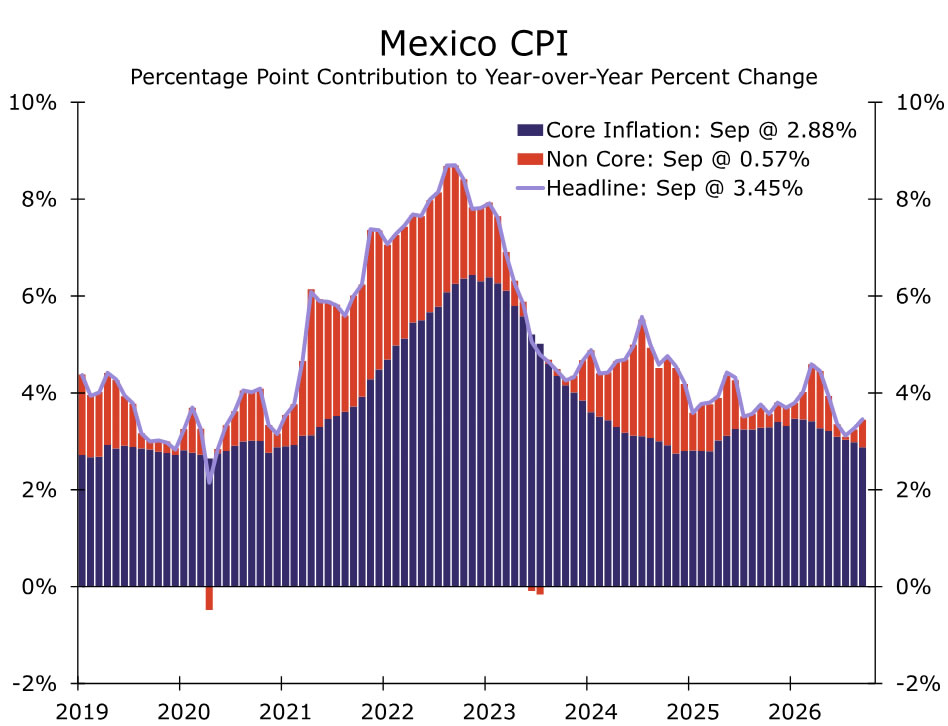
Mexico’s inflation looks set to edge higher again in October. We expect headline CPI to rise 3.69% year-over-year, with core inflation up 3.84%. Both annual rates would exceed their first-half readings of 3.62% and 3.78%, respectively. The expiration of summer electricity subsidies should drive much of the non-core increase. Electricity prices jumped 18.51% month-over-month in the first half of October as subsidies ended in 18 cities. Within core, services should provide the largest contribution, with higher airfares and late-October tourism demand likely adding pressure.
The renewed pickup in inflation should limit Banxico’s room to ease after yesterday’s 25 bps cut to 6.25%. We expect rates to remain unchanged through the rest of 2026 and 2027. While the board could become more dovish after Jonathan Heath’s term ends in December, inflation pressures persisting into next year could keep further cuts off the table.
Brazil CPI • Thursday
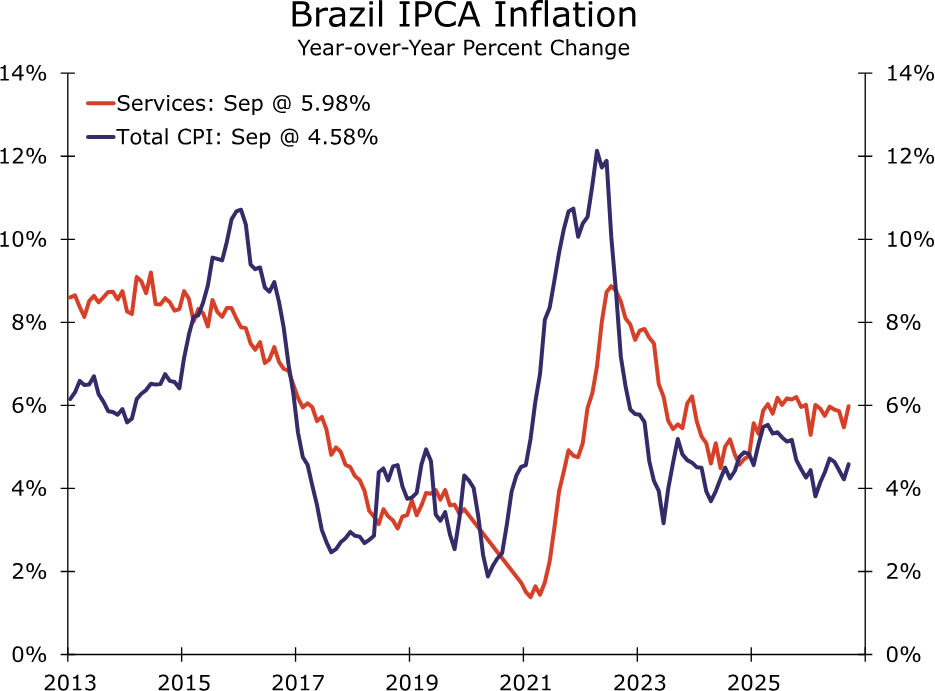
We expect Brazil’s October headline inflation to rise to 4.81% year-over-year, with food prices outweighing some relief from electricity tariffs. The extended IPCA reading through mid-October showed that September’s electricity-driven pressures had faded as the tariff flag shifted from yellow to green, removing surcharges from electricity bills. Food consumed at home still pushed inflation higher, largely due to supply pressures. More broadly, prices rose across eight of nine major CPI groups.
Even with inflation picking up, the Brazilian Central Bank (BCB) still has room to cut from a Selic Rate of 13.75%. Restrictive policy is weighing on activity, though uncertainty over the Lula administration’s fiscal plans favors patience for now. We expect rates to remain unchanged through year-end before cuts resume in Q1 2027. Higher inflation could slow the pace of easing, but we still see room for the cycle to continue.
India CPI • Thursday
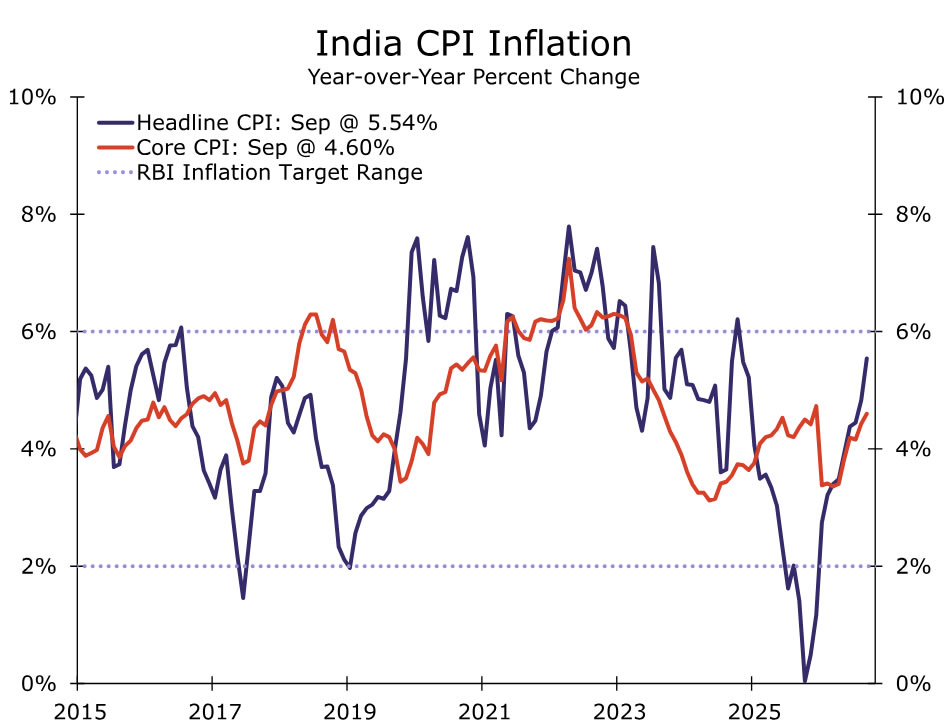
We expect India’s October headline inflation to rise to around 6% year-over-year, at the top of the Reserve Bank of India’s (RBI) target range. High vegetable prices should drive much of the increase, while base effects could lift the annual rate to that level even if monthly inflation slows to ~0.4% from September’s 0.69%. Food pressures remain a concern. Weak rainfall and El Niño threaten agricultural output, while higher energy and transport costs could limit relief from government measures. September wholesale price growth of 11.39% year-over-year also points to broader price pressures. Meanwhile, high-frequency indicators suggest growth remains firm, which gives the RBI less reason to delay tightening.
We have brought forward our expected hike from Q1 2027 to December, which would take the policy rate to 5.75% by year-end. Resilient growth and inflation near the upper band strengthen the case for an earlier move. Beyond December, we expect a more data-dependent approach. Further hikes in 2027 remain an upside risk rather than our base case.