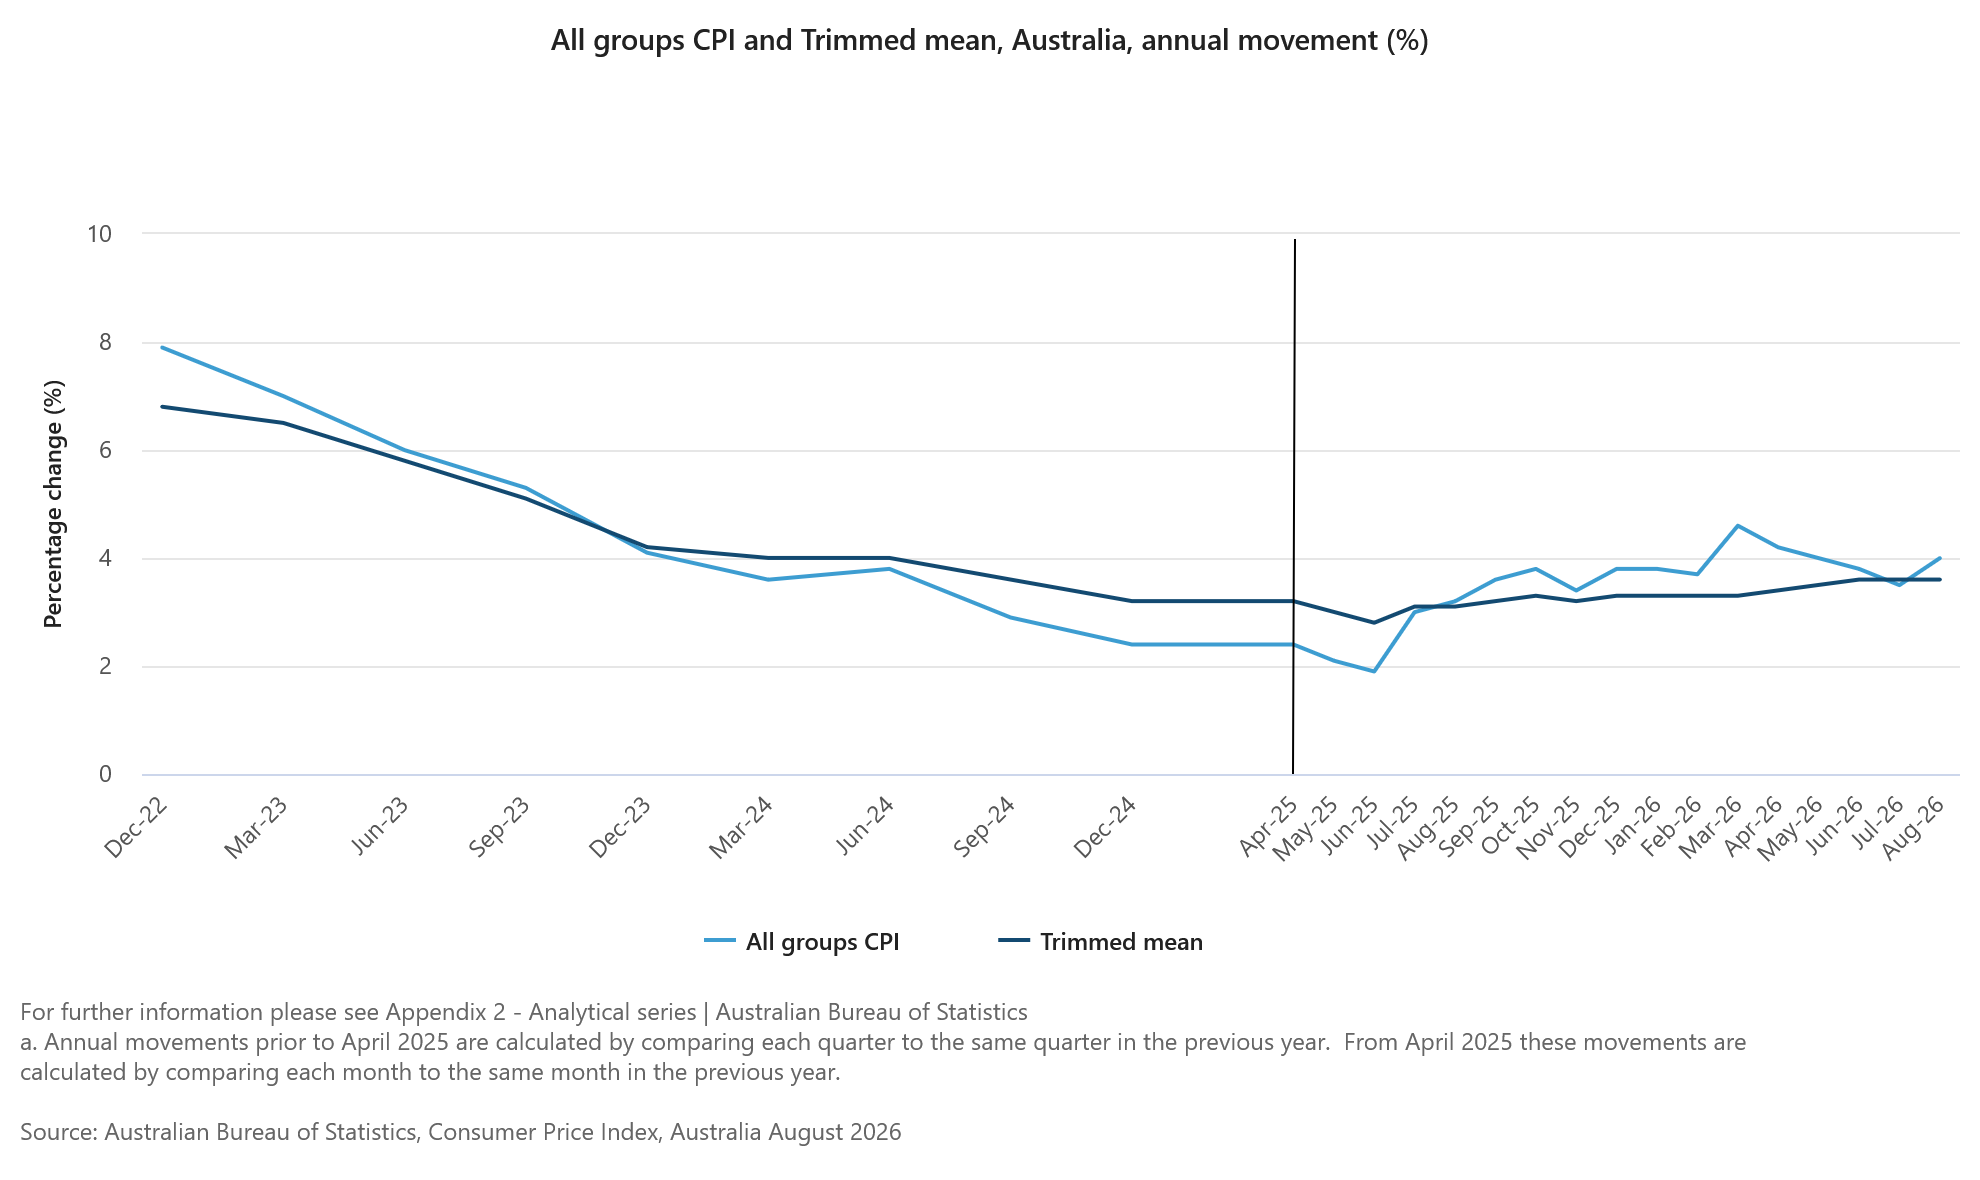
Australia’s headline inflation accelerated sharply in August, with CPI rising 3.5% → 4.0% y/y, matching expectations. Monthly CPI slowed 1.0% → 0.4%, also in line with consensus. The acceleration was concentrated in several large categories, with Housing up 5.7% y/y and Transport up 5.6%, alongside increases of 4.8% in alcohol and tobacco and 4.7% in education.
The more important surprise came from underlying inflation. Trimmed mean CPI slowed 0.5% → 0.2% m/m, undershooting expectations for 0.3%, while the annual rate held 3.6% → 3.6% for a third consecutive month. The ABS said the widening gap between headline and trimmed mean inflation was largely driven by automotive fuel and electricity, both of which were excluded from the trimmed mean in August. Automotive fuel prices surged 14.8% m/m, after a 7.5% increase in July, reflecting higher world oil prices and the remaining unwind of federal fuel-excise relief.
The result therefore confirms that Australia is facing renewed headline inflation pressure without a fresh acceleration in underlying inflation. Goods inflation stood at 4.2% y/y and non-tradables at 4.5%, showing domestic price pressure remains elevated, but the softer monthly trimmed mean argues against reading the 4.0% headline as evidence that inflation broadened further in August. For the near-term inflation picture, the distinction is significant: energy and housing are lifting the aggregate rate, while underlying momentum was softer than expected.
Data Summary
| Indicator | Previous | Current | Expected |
|---|---|---|---|
| CPI, m/m | 1.0% | 0.4% | 0.4% |
| CPI, y/y | 3.5% | 4.0% | 4.0% |
| Trimmed Mean CPI, m/m | 0.5% | 0.2% | 0.3% |
| Trimmed Mean CPI, y/y | 3.6% | 3.6% | 3.6% |
Headline inflation matched expectations, while the monthly trimmed mean was softer than forecast. Annual trimmed mean inflation remained unchanged at 3.6%.
Inflation Components
| Component | Monthly | Annual |
|---|---|---|
| Housing | 0.2% | 5.7% |
| Transport | 4.2% | 5.6% |
| Alcohol & tobacco | -0.5% | 4.8% |
| Education | 0.1% | 4.7% |
| Insurance & financial services | 0.2% | 3.5% |
| Food & non-alcoholic beverages | -0.1% | 3.0% |
| Goods | 1.0% | 4.2% |
| Services | -0.2% | 3.7% |
| Tradables | 1.3% | 2.9% |
| Non-tradables | 0.0% | 4.5% |
The ABS identified automotive fuel and electricity as key contributors to the gap between headline and trimmed mean inflation. Automotive fuel prices jumped 14.8% m/m in August after rising 7.5% in July.
Key Takeaways
- Headline CPI accelerated 3.5% → 4.0% y/y, exactly matching expectations, while monthly inflation slowed 1.0% → 0.4%, also in line with consensus.
- The main surprise came from trimmed mean inflation, which slowed 0.5% → 0.2% m/m, below the 0.3% forecast.
- Annual trimmed mean inflation remained 3.6% → 3.6%, marking a third consecutive month at that rate.
- The gap between headline and underlying inflation was heavily influenced by fuel and electricity, rather than a broad-based acceleration across the inflation basket.
- Transport inflation reached 5.6% y/y, while Housing inflation stood at 5.7%, keeping headline price pressure elevated.
- Domestic inflation remains firm, with non-tradables at 4.5% y/y, but the softer monthly trimmed mean shows underlying momentum did not accelerate further in August.
- Overall, the release is mixed rather than uniformly hot: headline CPI confirms renewed inflation pressure, while the trimmed mean undershoot points to softer underlying momentum.