


TL;DR: RBA Deputy Governor Andrew Hauser’s warning that Australia’s inflation outlook has “materially worsened” pushed November hike odds from ~27% to the 40–45% range. AUD/USD has broken above 0.7012 resistance and now faces a critical test at 0.7024–0.7035, with October 28’s Q3 CPI report set to decide whether the repricing becomes a durable Aussie rally.
Why This Matters
Australian Dollar is outperforming its major counterparts after RBA Deputy Governor Andrew Hauser warned that the inflation outlook has deteriorated materially, reviving expectations for another rate hike in November. Market-implied tightening probabilities have climbed into the 40–45% range, although a hold is still marginally favored. The repricing has given AUD a fresh boost, but the next policy decision remains open ahead of October 28’s Q3 CPI report.
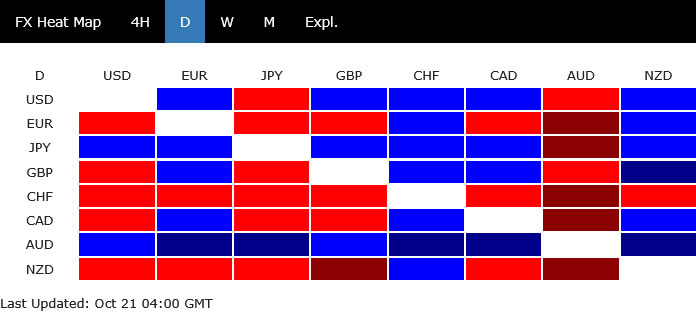
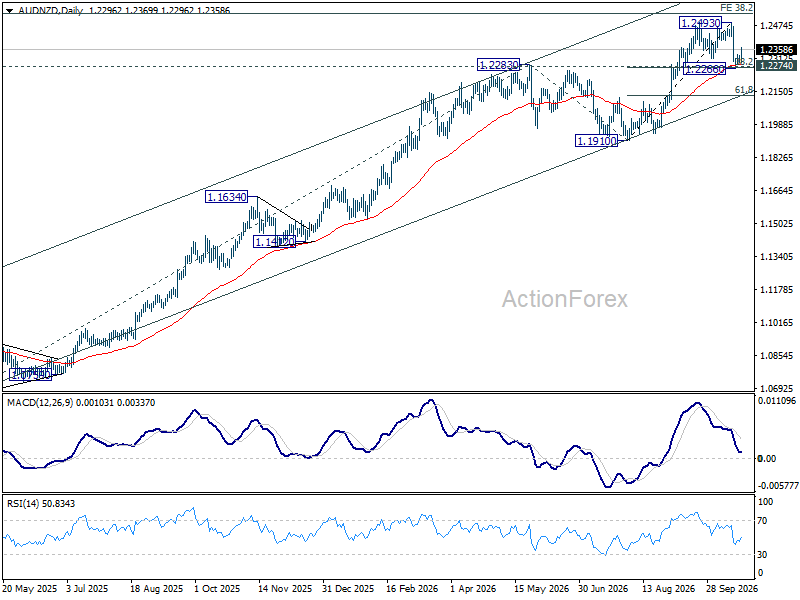
The technical picture is becoming more constructive without yet confirming a broader reversal. AUD/USD has broken above 0.7012 resistance and is approaching a critical test around 0.7024–0.7035, while AUD/NZD is rebounding after holding support near 1.2266. Sustained gains through these technical barriers would strengthen the case that Australian Dollar is entering a more durable rally.
Hauser Reopens November RBA Hike Debate
Speaking at the Citi Investment Conference in Sydney, Hauser said Australia’s inflation outlook had become “materially worse” than the RBA projected in August. Oil prices are approximately one-third higher than previously assumed, while resilient demand in major Asian trading partners and AI-related investment are adding to price pressures. These developments have complicated the outlook despite four rate increases this year, which have taken the cash rate to 4.60%.
More concerning is the possibility that inflation expectations are becoming less firmly anchored. Hauser noted signs that some businesses increasingly regard inflation around 3–3.5% as normal, raising the risk that energy-driven price increases could feed into broader and more persistent inflation. The RBA cannot reverse an external oil shock through domestic interest rates, but it must prevent second-round effects from undermining its 2–3% inflation target.
However, Hauser also acknowledged that previous tightening is working. Consumption growth is subdued, while September unemployment reached a five-year high of 4.7%, somewhat weaker than expected. Although he emphasized that unemployment remains low by historical and international standards, further tightening would risk additional deterioration. The RBA must therefore weigh the danger of entrenched inflation against the economic cost of another increase, rather than treating higher inflation forecasts as an automatic trigger for action.
November Hike Odds Jump, but Remain Below 50%
Financial markets responded by substantially increasing expectations for a November 3 rate hike:
- Before Hauser’s remarks: ~27–30% probability
- After Hauser’s remarks: ~41–45% probability
- Tuesday evening OIS snapshot: 23.2% probability
- A hike would lift the cash rate to 4.85%—the fifth increase this year
The repricing is significant because weaker employment data had previously reduced expectations of immediate tightening. Hauser’s comments have reversed part of that adjustment by emphasizing the deterioration in inflation prospects and the risk of expectations becoming entrenched. Nevertheless, November tightening is now a meaningful possibility, not yet the market’s favored outcome.
The distinction also matters for AUD. A more hawkish inflation assessment can support the currency by raising expectations for future interest rates, but additional appreciation may require stronger evidence that November tightening is becoming likely. With the decision still open, the latest repricing provides support without removing the risk of disappointment.
Aussie Outperforms Broadly, but AUD/USD Reaction Is Measured
Australian Dollar’s strength extends well beyond its performance against Dollar. In the early October 21 market snapshot, AUD was outperforming all seven major counterparts:
- AUD/NZD: +0.37%
- AUD/CAD: +0.27%
- EUR/AUD: −0.34%
- GBP/AUD: −0.28%
The breadth of the move points to an Australian Dollar-specific response to changing RBA expectations.
AUD/USD, however, was trading only modestly higher around 0.7016–0.7019. The pair had already recovered substantially from its October 15 low near 0.6893, supported partly by earlier Dollar weakness and China’s stronger-than-expected third-quarter GDP. Hauser’s remarks have reinforced an existing recovery rather than initiating the entire advance.
This distinction makes the crosses useful indicators of the RBA repricing. AUD/NZD, in particular, provides a clearer view of relative Australian Dollar strength without the direct influence of US Dollar movements. However, the cross also reflects New Zealand’s own inflation and monetary-policy outlook, making the upcoming New Zealand CPI release an additional factor to monitor.
Q3 CPI Could Decide Whether November Moves From Possible to Probable
Attention now turns to Australia’s Q3 CPI report on October 28, just ahead of the RBA’s November 2–3 meeting. The critical issue will be whether underlying inflation confirms the deterioration in the outlook sufficiently to justify another increase despite weakening employment.
The RBA’s August forecasts envisaged quarterly trimmed mean inflation of approximately 0.8% for Q3, while market estimates cited ahead of the release are closer to 0.9–1.0%. An outcome around 1.0% would exceed the RBA’s earlier projection but might not represent a significant surprise against current market expectations. The distinction is important because Hauser’s warning has already encouraged investors to anticipate stronger price pressures.
A larger upside surprise, particularly in underlying inflation, would strengthen the case for immediate tightening and could push November hike expectations above 50%. Conversely, softer trimmed mean inflation, combined with unemployment at 4.7%, would provide a stronger argument for allowing previous increases more time to work. For AUD, the release could determine whether the current recovery gains another policy-driven catalyst or loses part of its recent support.
ActionForex’s Technical View: AUD/USD, 0.7035 as the Critical Reversal Test
AUD/USD’s break above 0.7012 resistance suggests that a short-term bottom has formed at 0.6893. The recovery is supported by bullish divergence in the four-hour MACD, indicating improving momentum following the decline from 0.7237. A further rise is favored while 0.6968 minor support holds, although the initial resistance break is still marginal and the four-hour RSI is approaching overbought territory.
The decisive resistance zone lies between the 38.2% retracement of 0.7237 to 0.6893 at 0.7024 and the daily 55 EMA around 0.7035. Sustained trading above this area would strengthen the case that the entire decline from 0.7237 has completed, opening the way toward the 61.8% retracement at 0.7106.
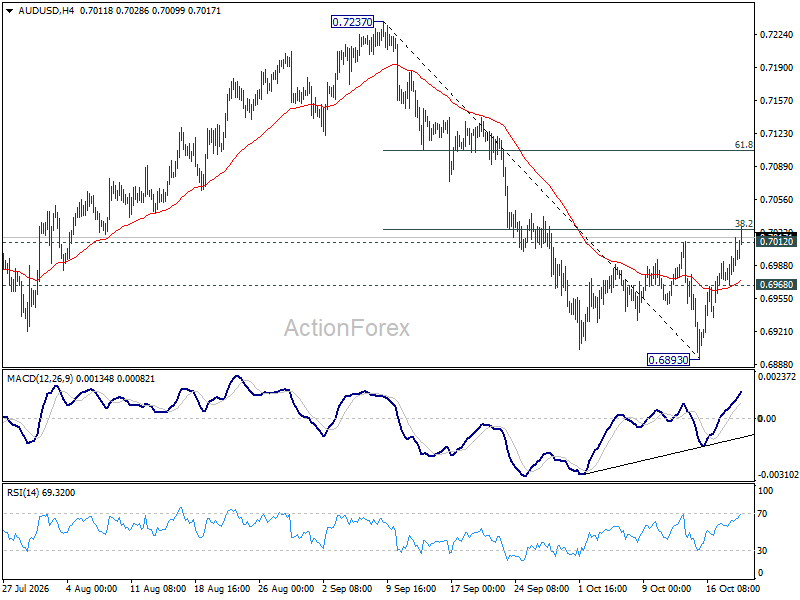
Such a development would also raise the possibility that the broader consolidation from 0.7277 has completed with three waves to 0.6893. However, that larger bullish interpretation would still require further confirmation through sustained upside momentum and subsequent resistance breaks.
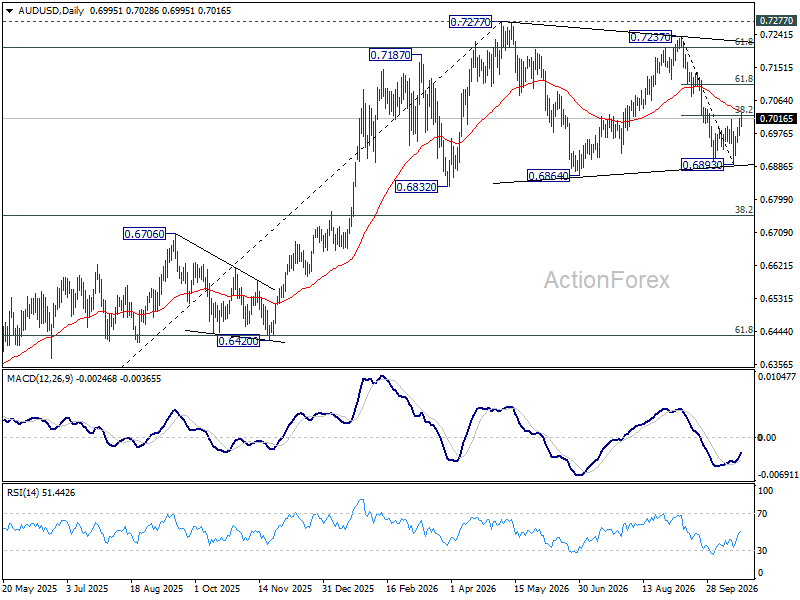
On the downside, a break below 0.6968 would weaken the immediate recovery and shift attention back toward 0.6893. A further break of that low would revive the decline from 0.7237 and undermine the developing bullish scenario.
The 0.7024–0.7035 zone is therefore the first important technical test of whether renewed RBA tightening expectations can translate into a broader AUD/USD advance.
ActionForex’s Technical View: AUD/NZD, 1.2266 Support Keeps Uptrend Intact
AUD/NZD is showing a potentially more constructive medium-term setup. The rebound from 1.2266 suggests that the pullback from 1.2493 could have ended after finding support around several converging technical levels.
These include the 38.2% retracement of 1.1910 to 1.2493 at 1.2270, the daily 55 EMA near 1.2286, and former resistance around 1.2283. The defense of this support cluster keeps the medium-term uptrend intact, despite the sharp retreat from September’s high.
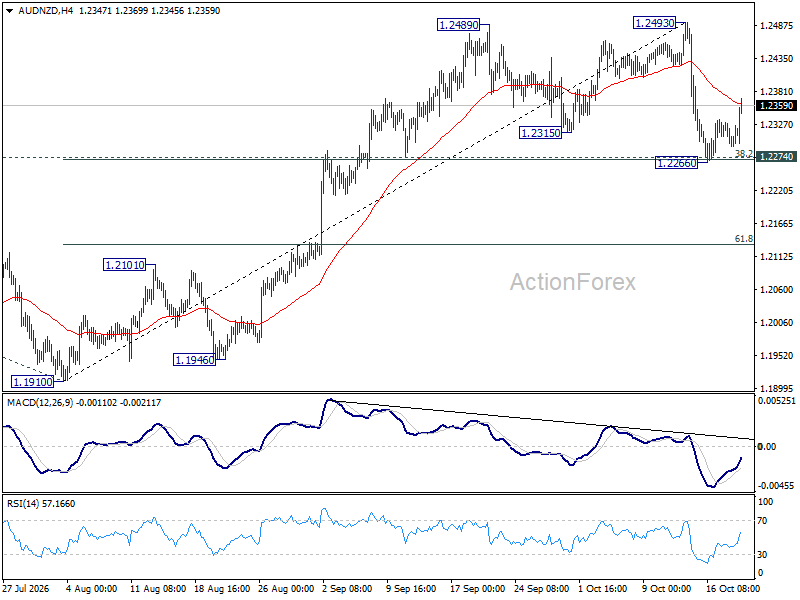
A further recovery toward 1.2493 is favored while 1.2266 holds. Nevertheless, the rebound has yet to clear the four-hour 55 EMA, so confirmation that the corrective decline has ended is still incomplete. Strong resistance could also emerge around 1.2493, potentially producing another corrective leg before the broader advance resumes.
A firm break below 1.2266 would invalidate the immediate bullish interpretation and expose the 61.8% retracement around 1.2133. For now, the combination of renewed RBA hike expectations and resilient technical support favors further AUD/NZD recovery, although New Zealand inflation data introduce a separate source of uncertainty.
The broader AUD outlook is therefore improving, but still conditional. Hauser has brought November tightening back into contention, while AUD/USD and AUD/NZD are approaching important technical confirmation points. Q3 CPI will be the critical test of whether the policy repricing can develop into a more sustained Australian Dollar advance.
Key Takeaways
- Hauser’s “materially worse” inflation warning pushed November RBA hike odds from ~27–30% to 41–45%, though a hold remains marginally favored and a Tuesday OIS snapshot still showed just 23.2%.
- AUD is outperforming broadly (AUD/NZD +0.37%, AUD/CAD +0.27%), but AUD/USD’s own move has been measured—Hauser reinforced an existing recovery from 0.6893 rather than starting it.
- October 28’s Q3 CPI is the decisive test: trimmed mean inflation near 1.0% (vs. the RBA’s 0.8% August forecast) could push hike odds above 50%, while a softer print alongside 4.7% unemployment would favor patience.
- AUD/USD’s key resistance is 0.7024–0.7035; a sustained break opens 0.7106, while a drop below 0.6968 and then 0.6893 would revive the decline from 0.7237.
- AUD/NZD’s 1.2266 support cluster is keeping its medium-term uptrend intact, with 1.2493 the next test and 1.2133 the risk on a firm break lower.





