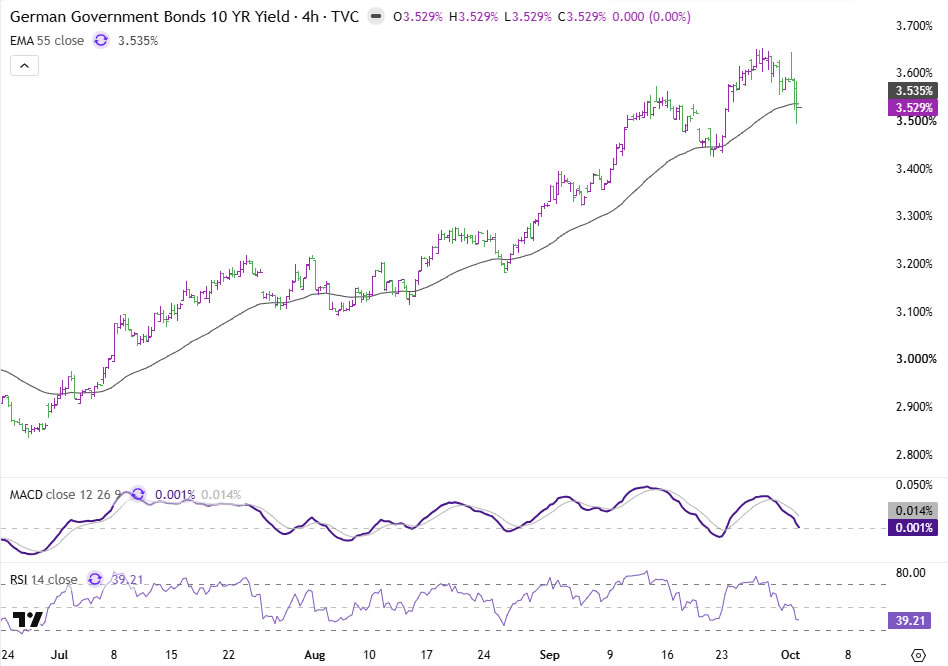
TL;DR: The OAT-Bund spread widened past 140.6bp, its widest since the 2012 eurozone debt crisis, as French 10-year yields surged to 4.935% while German Bund yields fell to 3.529%—a divergence pointing to a France-specific sovereign risk premium that EUR/CHF is now starting to transmit into FX.
Why This Matters
Europe’s bond selloff has stopped being one trade. Investors are now separating France from Germany—and EUR/CHF is starting to reflect the same divide. When two countries share a currency and a central bank but their bond yields move in opposite directions, that is not a generic rates story; it is markets pricing one government’s fiscal credibility differently from another’s. For traders, that makes the spread itself, not the outright yield level, the cleanest signal of how far this repricing could run, and it gives EUR/CHF a specific technical path to watch for confirmation.
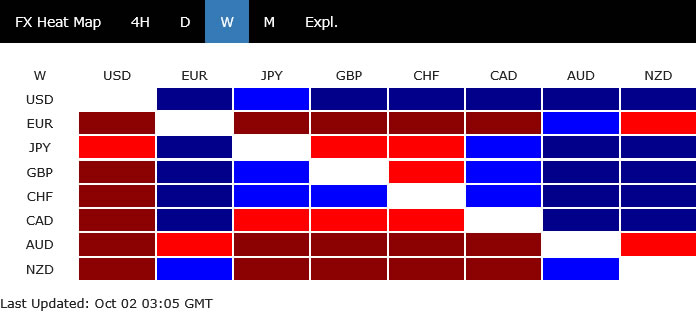
France Is Being Asked to Pay More for Fiscal Risk
The immediate backdrop is France’s 2027 budget. Prime Minister Sebastien Lecornu’s government has presented a package targeting around EUR 54bn of savings, seeking to reduce the deficit from 5.4% of GDP in 2026 toward 5% next year. Measures include spending restraint and targeted tax changes, but the legislation now faces a difficult parliamentary process in a divided legislature and is likely to be amended substantially.
The bond-market mechanism is straightforward. When investors become less confident that a government can stabilise its deficit and debt trajectory, they demand a larger yield premium to hold that government’s debt. In France’s case, that premium is visible against Germany, whose Bund market serves as the Eurozone’s core benchmark.
That distinction matters because France and Germany share the same currency and the same ECB policy rate. A global rates shock can push both yields higher together. It does not easily explain French yields accelerating toward 5% while German yields fall. That is why the spread, rather than the outright OAT yield, is becoming the cleanest gauge of whether markets are escalating their concerns about France.
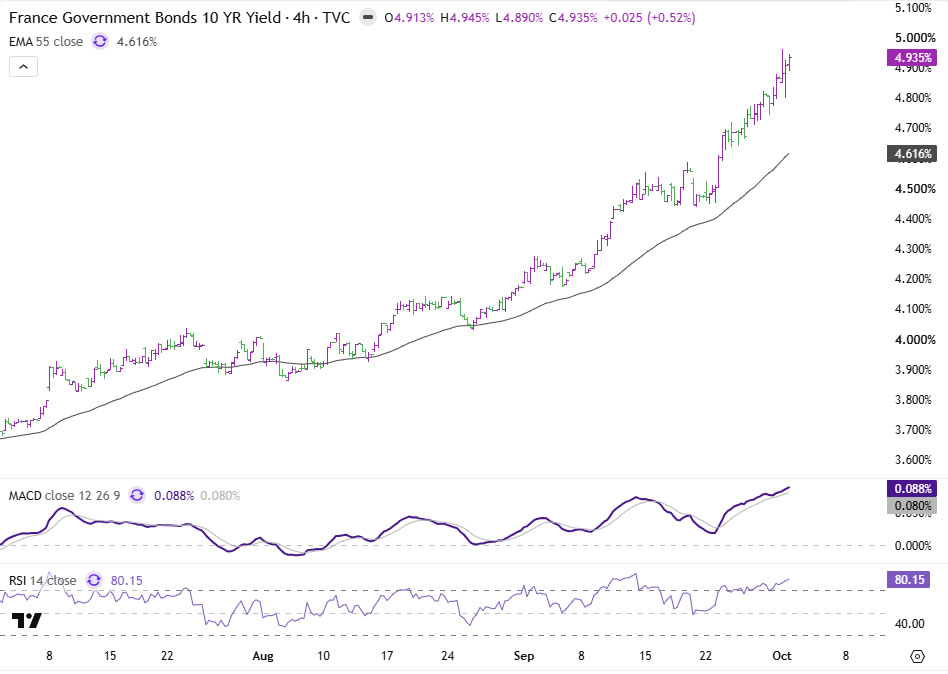
The French 10-year chart reinforces the severity of the move. Yield is well above the 4H 55 EMA near 4.616%, with RSI above 80 and MACD still positive. German yields, by contrast, have fallen back toward their 55 EMA near 3.535%, while RSI has slipped below 40 and momentum has rolled over. The technical picture is therefore telling the same story as the spread: French risk is accelerating while demand for German duration is returning.
Inflation Makes the Backdrop Harder, but Does Not Explain the Divergence
Europe’s inflation backdrop is adding pressure, but it cannot by itself explain the France-Germany split. French national CPI accelerated from 2.4% to 3.0% y/y in September, while the comparable harmonised measure rose from 2.6% to 3.4%. Germany’s harmonised inflation also accelerated to 3.3%, with energy inflation reaching 14.9%. In France, energy inflation was even stronger at 21.2%.
That helps explain why European yields remain structurally elevated. Renewed energy pressure and the Middle East conflict have revived concerns about how quickly inflation can return sustainably toward target. But the common inflation shock actually makes the OAT-Bund divergence more informative: if inflation alone were driving Thursday’s bond move, French and German yields should be responding more similarly. Instead, Bunds rallied while OATs sold off.
Inflation is therefore an amplifier of France’s problem, not a complete explanation for it. The widening spread reflects the interaction of higher inflation risk, higher term premia and French fiscal uncertainty, a combination also highlighted by market strategists as the premium on French debt widened.
European Equities Add Context, but the Spread Carries the Cleaner Signal
European equities sold off alongside the bond-market stress, with CAC 40, DAX and FTSE all under pressure. Yet the equity move is a noisier measure of French-specific risk. German and British shares are exposed to the same higher-energy, higher-yield environment even without France’s fiscal problem, which makes a broad European equity decline compatible with several different macro explanations.
Wall Street, meanwhile, managed to close modestly higher after the US 10-year Treasury yield retreated from its 5.34% intraday peak, with company-specific technology developments also providing support. The more useful hierarchy is therefore clear: OAT-Bund spread first. EUR/CHF second. Equities third. The first strips away much of the global-rates noise. The second shows whether FX traders are transmitting the same European risk discrimination into the Swiss franc.
140bp Is Now the Key Sovereign-Risk Test
The spread itself is the most direct test of whether this develops into something more persistent. At around 140.6bp, investors are already demanding substantially more compensation to own French debt than German Bunds. Reuters had recorded the spread at 132.86bp on October 1, already its widest since the 2012 eurozone debt crisis. The subsequent move beyond 140bp therefore represents another meaningful extension.
From here, continued widening would strengthen the case that markets are making a structural adjustment to France’s risk premium, rather than simply reacting to a single difficult session. A stabilization around current levels would suggest investors are waiting for more clarity from the budget process. A meaningful reversal toward the 90–95bp area seen before the latest acceleration would weaken the argument that a durable repricing is underway.
That makes France’s parliamentary budget process the next hard domestic catalyst. The government has laid out the fiscal arithmetic; markets now need to judge how much of it can actually survive the legislative process.
ActionForex’s Technical View: EUR/CHF Is Starting to Transmit the Same Message
FX is beginning to reflect the bond-market divergence. EUR/CHF has reversed sharply from 0.94850 to around 0.9340, falling back below its daily 55 EMA near 0.9371. Momentum has deteriorated with RSI below 40 and MACD rolling lower.
Franc strength has not been confined to Euro either—USD/CHF and GBP/CHF have also fallen, showing broader CHF demand. But EUR/CHF remains the more useful instrument for the French-risk thesis because it directly pits the common currency against Europe’s traditional low-risk funding currency.
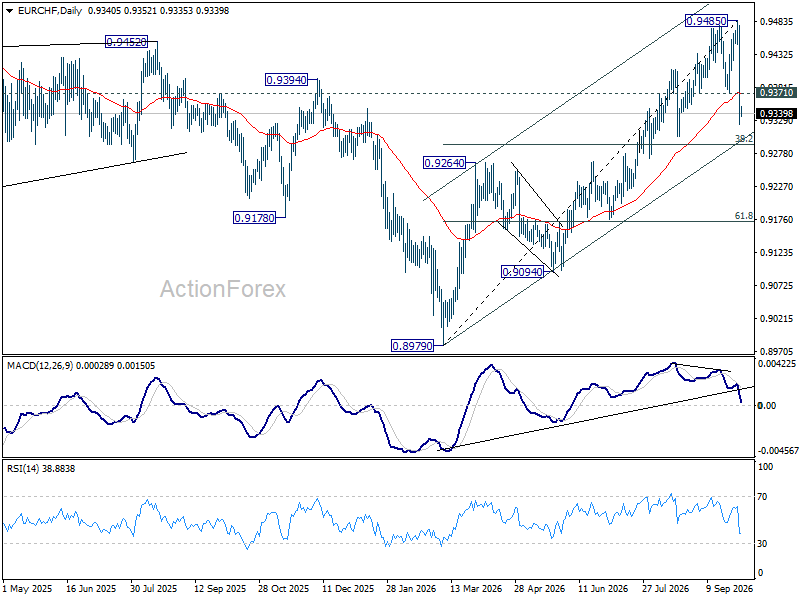
Technically, however, the move remains at an early stage. The rise from 0.89790 to 0.94850 puts the 38.2% Fibonacci retracement at around 0.92917 and the 61.8% retracement at 0.91723. EUR/CHF has not yet reached the first level. That gives a useful hierarchy:
- A hold above 0.92917, followed by a recovery, would keep the decline consistent with a relatively shallow correction within the broader advance from 0.89790.
- A sustained break below 0.92917 would strengthen the bearish case.
- A move toward 0.91723 would suggest a substantially deeper repricing and put the broader recovery from 0.89790 into question.
But the bond spread must remain part of the confirmation. A EUR/CHF break below 0.92917 alongside another widening in OAT-Bund would provide a much cleaner signal that French fiscal risk is spreading through European assets. The same EUR/CHF break occurring while OAT-Bund stabilizes or narrows would be less convincing—it could instead reflect generic Euro weakness, broader CHF demand or positioning around US data.
NFP Can Blur the Signal Before France Gives the Next Answer
Today’s US nonfarm payrolls release, with consensus around 90K, adds a major external complication. A large payroll surprise could dominate global rates, Dollar and risk sentiment, potentially obscuring the France-specific signal for several hours. That makes relative moves more useful than outright FX moves after the release.
The most informative configuration would be continued OAT-Bund widening accompanied by renewed EUR/CHF downside. That would suggest French risk is still driving the move even through the US data noise. If USD/CHF moves sharply after NFP while EUR/CHF remains relatively stable, the Dollar channel would be doing more of the work. If EUR/CHF continues falling while USD/CHF does not, the European risk signal becomes cleaner.
But NFP is ultimately an external interruption. France’s budget process remains the harder test. The market has already pushed the OAT-Bund spread beyond 140bp. EUR/CHF has begun to respond, but it has not yet broken its first major retracement level.
France and Germany still share a currency and a central bank. For now, their bond markets are increasingly pricing them as very different risks.
Key Takeaways
- The OAT-Bund spread has widened past 140.6bp, its widest since the 2012 eurozone debt crisis, as French yields rise and German yields fall simultaneously.
- The divergence points to a France-specific fiscal risk premium tied to Prime Minister Lecornu’s 2027 budget, not a generic eurozone rates move—inflation is running hot in both countries but cannot explain the split.
- EUR/CHF has reversed from 0.94850 to around 0.9340 but has not yet broken its first key retracement at 0.92917; a break there alongside continued spread-widening would be the cleanest confirmation signal.
- The recommended watch order is OAT-Bund spread first, EUR/CHF second, European equities third, since equities are a noisier read on French-specific risk.
- Today’s NFP release could temporarily obscure the France signal; watch whether EUR/CHF moves independently of USD/CHF to judge whether European risk, not the Dollar, is driving price action.
Related Reading
- Sterling Broadens Gains as BoE Repricing Builds and GDP Confirms Resilience
- Dollar Index Completes Double Bottom, Targets 100.59 as Markets Look Beyond Fed’s 4.1% 2027 Median
- Gold Holds 4,113 Support, but 4,235 and 4,335 Still Block the Bull Case
Stay ahead of Europe’s sovereign-risk divergence—subscribe to ActionForex’s daily market commentary for real-time technical and fundamental analysis.