TL;DR: The Australian Dollar is the week’s worst-performing major currency even with a September RBA hike to 4.60% essentially fully priced—the weakness reflects position lightening ahead of uncertain vote composition and guidance, not doubt about the hike itself, with AUD/USD now testing 0.7006 support.
Aussie Underperformance Goes Beyond Risk Aversion
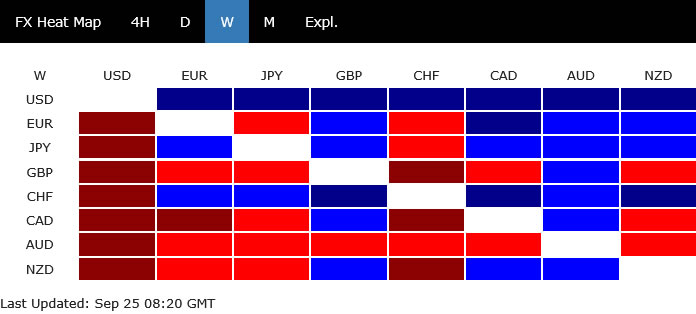
The Australian Dollar is heading into next Tuesday’s RBA meeting as the worst-performing major currency of the week, down around -1.4% against the Dollar and underperforming even NZD. Broad Dollar strength and rising US yields explain much of the move: every major currency has weakened against USD, with lower-beta currencies generally holding up better than their more risk-sensitive peers. But AUD’s additional weakness points to something more specific. With a 25bp RBA hike to 4.60% essentially fully priced, the market has little remaining upside to capture from the headline decision itself while still facing uncertainty over the vote, statement tone, and guidance on what comes next.
That makes the current move best read as position lightening ahead of asymmetric event risk, rather than evidence traders already expect a divided or dovish board. The distinction matters. Investors can remain convinced the RBA will hike on Tuesday and still reduce long-AUD exposure because the information attached to that hike is far less certain. A clean, unanimous decision with firm guidance may merely validate what’s already priced. A split vote or softer language on further tightening, however, could force a much larger repricing.
The Hike Is Priced. The Event Risk Isn’t.
That uncertainty is visible further along the rates curve. While the September hike is priced at essentially 100%, the implied probability of another move drops sharply to around 40.8% for November and 26.4% for December, before recovering only partially by February. The market is therefore not pricing a smooth continuation of tightening. It’s pricing one highly probable hike followed by a much more uncertain path.
The sell-side divide reinforces that distinction. Commonwealth Bank expects a unanimous decision with hawkish statement language, while Westpac expects a split vote, despite both arriving at the same 4.60% cash-rate forecast. August’s hold was unanimous on the rate itself, but the minutes already showed differing assessments beneath that decision, with some members emphasizing the possibility upside inflation risks could crystallize while others placed greater weight on offsetting downside risks.
RBA Monetary Policy Board member Iain Ross added another layer this week, saying there was “no evidence of the emergence of a wage-price spiral” and that recent data suggested such an outcome was unlikely. That weakens the case for treating wages themselves as an accelerating inflation engine, but it doesn’t remove the broader tightening argument. Above-target underlying inflation, excess-demand concerns, and the possibility that imported energy shocks generate second-round effects remain central to the hawkish case.
Domestic Data Give Both Sides Something to Use
The latest labor data illustrate why the Board’s internal debate could remain difficult even if the rate decision itself is straightforward. August employment rebounded by 39.5k, but all of the net increase came from part-time work, while full-time employment fell by around -6k and unemployment rose from 4.5% to 4.6%. The message isn’t that labor demand has collapsed, but that spare capacity is continuing to build at the margin even as employment still grows.
Wages point in a similar direction. The Q2 Wage Price Index held at 3.2% y/y, down from 3.4% a year earlier, with private-sector wages at 3.1% and public-sector wages at 3.4%. Against headline CPI of 3.5% and trimmed-mean inflation of 3.6%, households aren’t receiving a meaningful real-income cushion from wages. That’s consistent with Ross’s rejection of a wage-price spiral and complicates the argument for repeated tightening based on domestic wage pressure alone.
Financial markets are also increasingly discounting a weaker household backdrop. Australian consumer discretionary shares have fallen sharply over the past year, while housing prices have retreated from their April peak. Those moves aren’t direct measures of consumption, but they do show investors becoming more cautious about the earnings and growth consequences of higher rates. HSBC’s Paul Bloxham has gone further, putting the probability of a technical recession near 50% if both September and November hikes materialize, well above the roughly 20% consensus. That remains a minority view, but it illustrates how much more contentious the second hike is than the first.
The RBA Must Decide Before the Next CPI Print
Another complication is timing. The RBA will make Tuesday’s decision one day before the August CPI release, meaning policymakers won’t have the freshest inflation reading when they vote.
That helps explain why the market can be nearly certain about September while remaining much less confident about November. The Board already has enough inflation evidence to justify another increase if it chooses, but guidance beyond Tuesday may need to remain conditional because the next inflation print could either reinforce or soften the case for follow-through.
The asymmetry for AUD is therefore clear. The expected 25bp hike itself offers limited new information. The market will instead focus on whether the vote is unanimous, whether the statement retains language signaling willingness to tighten further, and whether the Board presents September as another step in a sequence or as a more cautious insurance move.
ActionForex’s Technical View on AUD/USD: Testing the 0.7000 Decision Zone
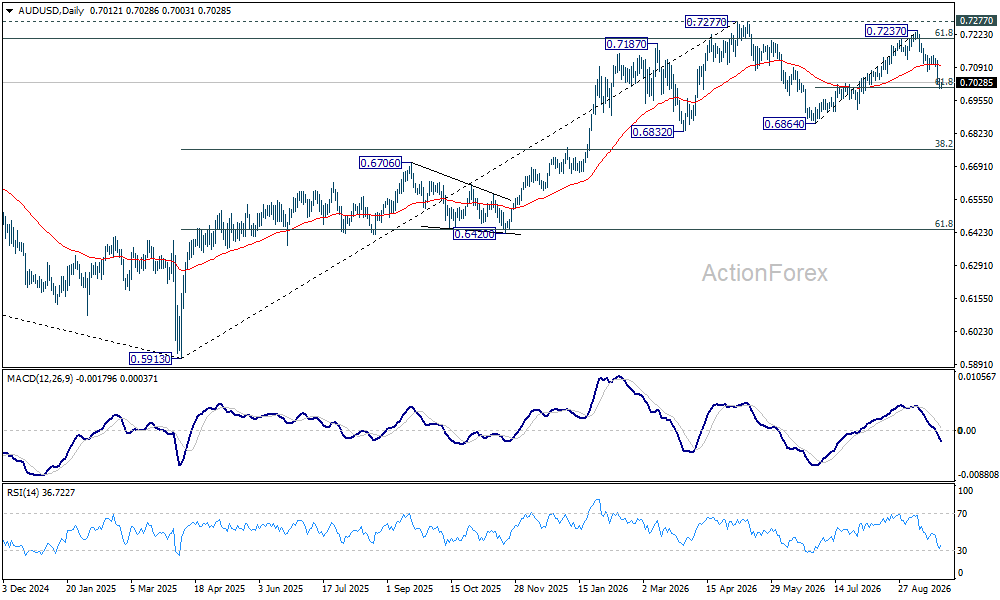
That positioning risk is already visible in AUD/USD, which has extended its decline from 0.7237 and broken decisively below the daily 55 EMA as well as former 0.7074 support. The pair is now pressing the 0.7006 level, the 61.8% retracement of the rise from 0.6864 to 0.7237.
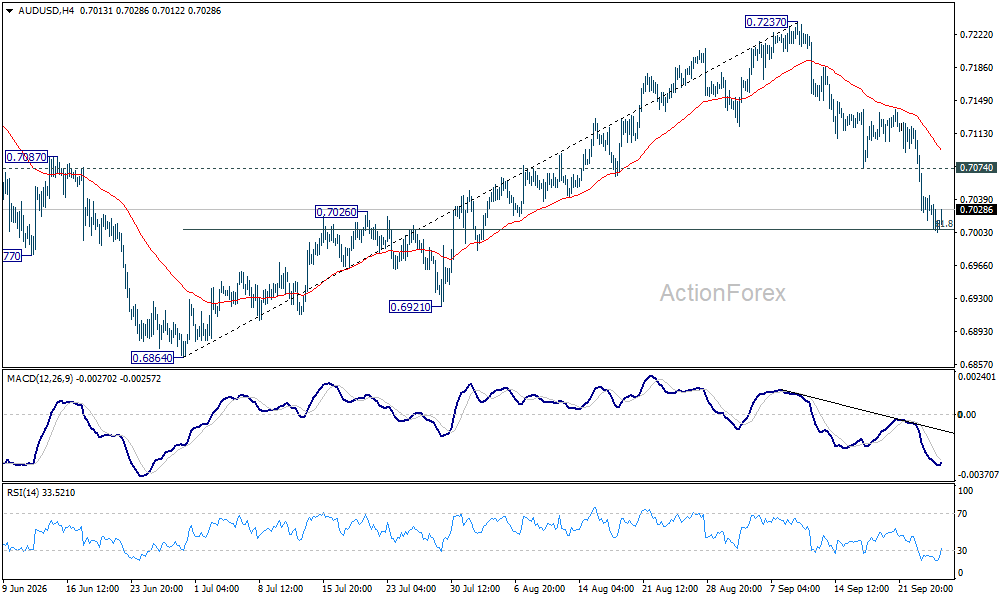
The decline is currently viewed as the third leg of the corrective pattern from the 0.7277 high. A sustained break below 0.7006 would expose 0.6864, with the larger 0.6756 area—38.2% retracement of the rise from 0.5913 to 0.7277—becoming the next major medium-term support. Unless AUD/USD is undergoing a broader bearish trend reversal, stronger buying interest should emerge around that 0.6756 zone.
On the upside, 0.7074 has become the first meaningful resistance. Reclaiming it would suggest near-term stabilization, although a more convincing recovery would still require the pair to rebuild above its falling short-term moving averages.
Tuesday Is About the Information Around the Hike
The key point is that AUD weakness doesn’t necessarily mean markets expect the RBA to disappoint. It’s more consistent with investors reducing long exposure because the headline hike is already known while the accompanying information remains uncertain.
A unanimous 25bp increase with clearly hawkish guidance would remove some of that uncertainty and could stabilize AUD. A split vote or softer language around further tightening would be the more obvious downside surprise and could accelerate a break below 0.7006.
Perhaps the most revealing outcome would be a clean, hawkish hike that still fails to lift the currency. That would suggest the broader Dollar backdrop, domestic growth concerns, and positioning are overpowering the rate differential. For now, the market isn’t really debating whether the RBA hikes on Tuesday. It’s deciding how much AUD exposure it wants to carry into an announcement whose tone may matter far more than the rate move itself.
Key Takeaways
- AUD is the week’s worst-performing major currency (-1.4%) despite a September RBA hike being essentially 100% priced, reflecting position lightening ahead of uncertain vote and guidance.
- Sell-side banks disagree on vote composition even while agreeing on the 4.60% outcome: CBA expects a unanimous hawkish decision, Westpac expects a split vote.
- November hike odds sit at just 40.8%, well below September’s near-certainty, showing markets are pricing one confident move followed by real uncertainty.
- Weak full-time employment (-6k) and wages holding at 3.2% y/y, below both headline and trimmed-mean CPI, complicate the case for aggressive follow-through tightening.
- AUD/USD is testing 0.7006 support; a break opens 0.6864 and then the major 0.6756 medium-term support, while reclaiming 0.7074 would suggest near-term stabilization.