A Lack of Headroom: The RBNZ, Oil Prices and Administered Costs
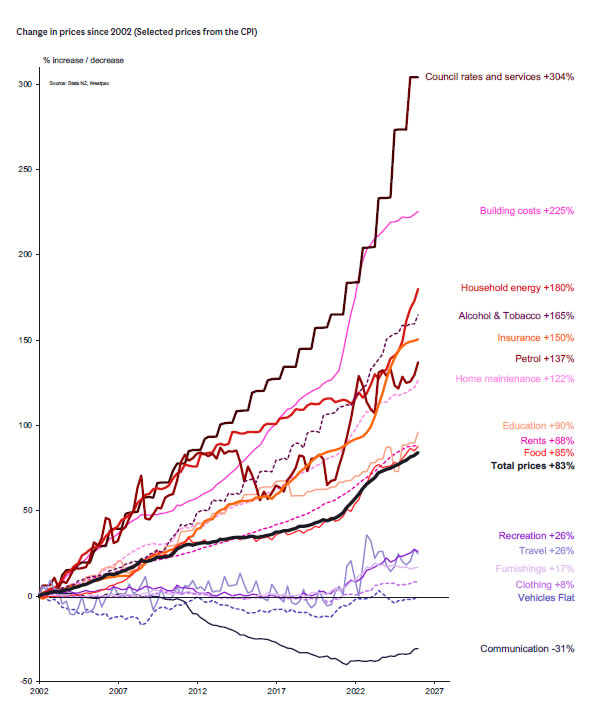
- New Zealand households have faced a run of large cost increases in recent years related to administered charges and parts of the economy that are less exposed to competition, such as electricity charges and local council rates.
- Those cost increases have continued for an extended period, making them hard for the RBNZ to look through.
- This has also meant that the RBNZ had little headroom to absorb upside inflation surprises even before the recent spike in oil prices.
- We expect that there will be ongoing sizeable increases in many of these costs. That is a key reason why we expect domestic (non-tradables) inflation will be higher than the RBNZ expects over the longer-term.
- That ongoing firmness in domestic inflation is also a reason why we expect the RBNZ will ultimately need to raise the OCR by more than they assumed in their September policy Statement.
- But getting inflation down to target levels in the face of an oil price spike and high administered prices won’t be easy and involves some tough trade-offs. Administered prices tend to be less responsive to changes in economic conditions. As a result, interest rate hikes are likely to have a bigger impact on parts of the economy that are not the main drivers of inflation.
Inflation Is High for Reasons Beyond Oil Prices
Inflation in New Zealand rose to 4.1% in the year to June, the highest it’s been in three years. And it’s set to remain above 3% until at least mid-2027.
Much of the recent strength in inflation has been due to the spike in oil prices since the outbreak of war in the Middle East. However, even before the spike in fuel costs, inflation had been running hot for an extended period: inflation has been above 3% since mid-2025, and it’s now been above the RBNZ’s 2% target midpoint for five years.
That persistent firmness in inflation is particularly notable as, based on RBNZ estimates, the New Zealand economy has had a negative output gap since September 2024, with softness in economic growth and a weak labour market. Those conditions would typically be associated with more moderate inflation than we’ve seen.
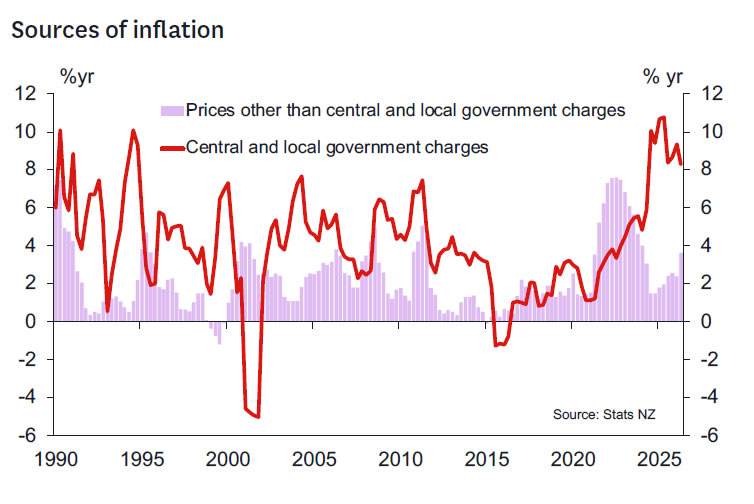
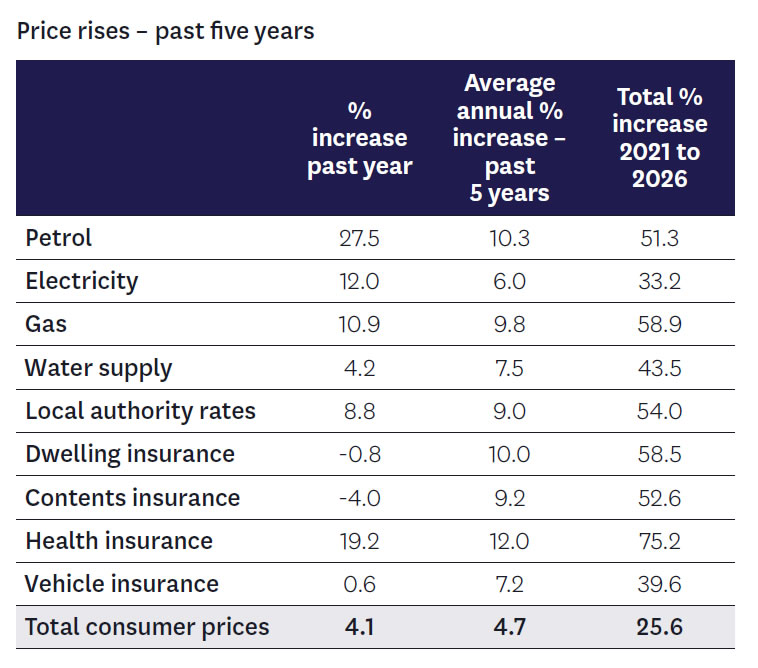
Looking beneath the surface, much of the strength in inflation over the past year has been related to administered costs, such as government charges, and price increases in parts of the economy that are less exposed to competitive pressures. For instance, over the past year, local council rates rose nearly 9%, electricity prices rose by 12% and health insurance premiums rose by 19%.
The less competitive nature of some of these sectors means they aren’t very responsive to changes in interest rates. Instead, they are most likely to behave in a “cost-plus” manner. And in some cases, recent years have seen large increases in operating costs that are now being passed on to consumers.
These Aren’t One-Off Cost Rises the RBNZ Can Look Through
Just as the RBNZ might look through a one-off spike in oil prices, there’s a reasonable argument for looking through a one-off rise in administered prices that pushes up inflation. For instance, a one-off increase in vehicle registration costs might boost inflation temporarily, but isn’t something the RBNZ would respond to.
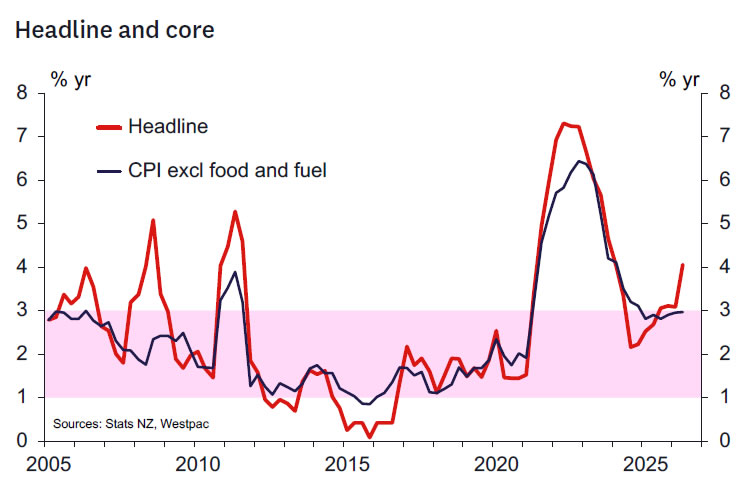
However, the issue here is that the increases we’re seeing are not one-off price rises. We’ve seen large increases spread across a range of administered costs for several years now (see chart on page 4). That’s been reflected in measures of core inflation, which strip out swings in volatile items like fuel and instead track the underlying trend in prices. For example, excluding the rise in food and fuel prices, inflation in the year to June was 2.9%, and it’s been running close to or above 3% for five years now. That’s meant that the RBNZ had little headroom to absorb upside inflation surprises even before the recent spike in fuel costs.
We expect that there will be continued large increases in some administered costs. For instance, in the case of local council rates, many councils will need to fund significant infrastructure spending over the coming years. There have been efforts to limit the extent of those increases, such as the Government’s cap on council rates. However, that doesn’t change the underlying reason for the large rates increases in recent years, such as increased spending on essential infrastructure. And if councils can’t raise the required revenue through rates, they may have to look at other approaches like user pays. That could shift costs for households, rather than reducing them.
Why Does This Matter?
It’s important to remember that the RBNZ’s focus is not individual prices in the CPI (like fuel prices or council rates), but the overall level of inflation. In essence, it doesn’t matter why inflation is elevated — all that matters is that it is elevated and how persistent inflation will be.
Right now, with core inflation already elevated, it’s hard for the RBNZ to look through the large and continuing cost increases that we’ve seen across a range of areas that are less exposed to competition. And given the risk of ongoing large increases in these costs, we expect that domestic (non-tradables) inflation will be higher than the RBNZ has assumed over the longer-term.
That’s part of the reason why we continue to expect that the RBNZ will need to raise the Official Cash Rate by more than they had assumed in their September policy Statement. We’re forecasting a 25bp rate rise at the RBNZ’s December meeting and expect the OCR will peak at 4% next year. That risk is being compounded by the protracted nature of the current rise in oil prices, along with other risks such as El Nino which could boost food prices over the coming year.
However, costs like oil prices, electricity charges, and administered charges like council rates are not responsive to changes in interest rates. As a result, when inflation pressures are centred on such areas, the RBNZ needs to work harder to keep overall inflation in check. It does this by leaning against inflation in areas of the economy that are more responsive to interest rates to bring aggregate inflation pressures down towards target in a timely manner. But rather than leaning against the source of inflation pressures, the impact of tighter policy will be to dampen demand and price-setting in other more interest rate-sensitive parts of the economy such as the construction sector or discretionary retail spending.
This is an uncomfortable but necessary trade-off. Tighter policy will weigh on discretionary spending, the labour market and near-term growth, and would affect prices in parts of the economy that are not the drivers of inflation. A higher OCR also means increases in households’ debt-servicing costs, and for some households, that will be very challenging.
However, looking through or not responding to these sorts of ongoing large cost increases would still leave households dealing with significant increases in overall living costs. In the long run, that could be more damaging for households and the economy.
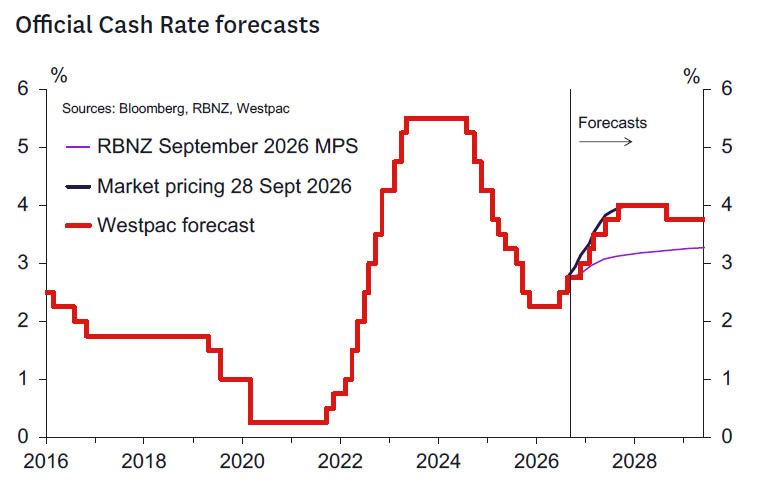
Adding to the RBNZ’s concerns about both the oil price shock and continued large increases in administered prices, inflation expectations are relatively elevated. In fact, long-term inflation expectations in business and consumer surveys are close to where they were in 2022 when inflation was much higher than today. Similarly, firms consistently signal in business surveys that cost pressures are strong and margins have been squeezed.
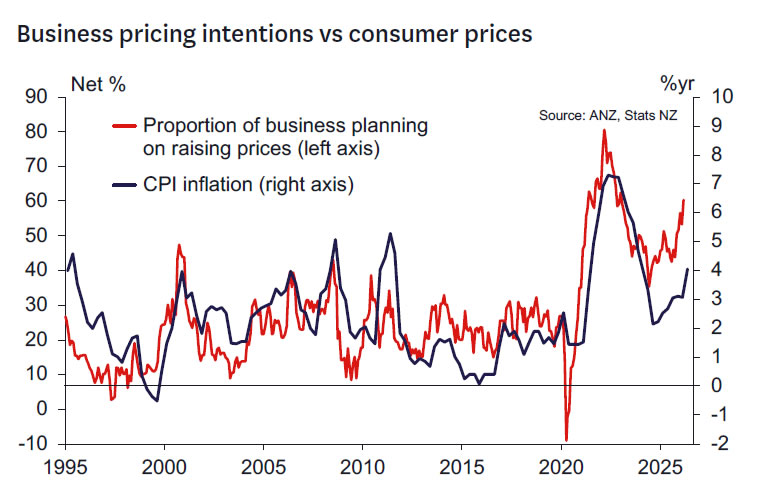
Softness in demand might be limiting some firms’ ability to lift prices at the current time. However, when demand eventually firms again, there’s a risk that businesses expect continued high levels of inflation and try to push through larger price rises (sometimes referred to as high inflation expectations becoming ’embedded’). That means inflation could remain high even when the immediate impact of temporary boosts to inflation, like an oil price spike, fades. This is a key reason why it’s important to get inflation back to 2% on a consistent basis, rather than allowing inflation to run at levels closer to the top of the RBNZ’s target band.
The RBNZ does have discretion in how aggressively it responds to inflation, and that is where the source of inflation matters. The RBNZ is likely to adjust the OCR more gradually when inflation is related to less interest rate-sensitive areas, like oil costs or government charges. And when doing so, it does account for how changes in the Official Cash Rate could affect the labour market and economic activity. But even if the RBNZ responds more gradually to inflation, it can’t ignore ongoing large cost increases indefinitely. Eventually inflation needs to be brought back to target.