- Fed’s hawkish hike adds fuel to dollar’s engines.
- US, Eurozone and UK flash PMIs to test inflation and growth outlooks.
- SNB set to stand pat amid low inflation and still-strong franc.
- Trump–Xi talks could impact aussie, kiwi and risk sentiment.
Fed Satisfies Hawkish Market Bets
The US dollar outperformed all its major peers this week, putting it on the front foot in anticipation of a hawkish Fed before Wednesday, and accelerating its advance after the central bank satisfied the hawkish market bets.
The Committee decided to press the hike button for the first time since 2023 via a unanimous vote, citing elevated inflation and upside risks, resilient domestic demand, employment and investment. Officials upgraded their GDP and inflation forecast for 2026, while the new dot plot pointed to another rate hike by the end of the year.
Although the median dot for 2027 did not indicate any additional increases, eight members voted for another hike next year, while one believed two could be warranted. This allowed investors to maintain their hawkish bets, assigning a 50% chance of a back-to-back increase in October, and fully factoring it in for December. As for 2027, another two quarter-point hikes are nearly fully priced in.
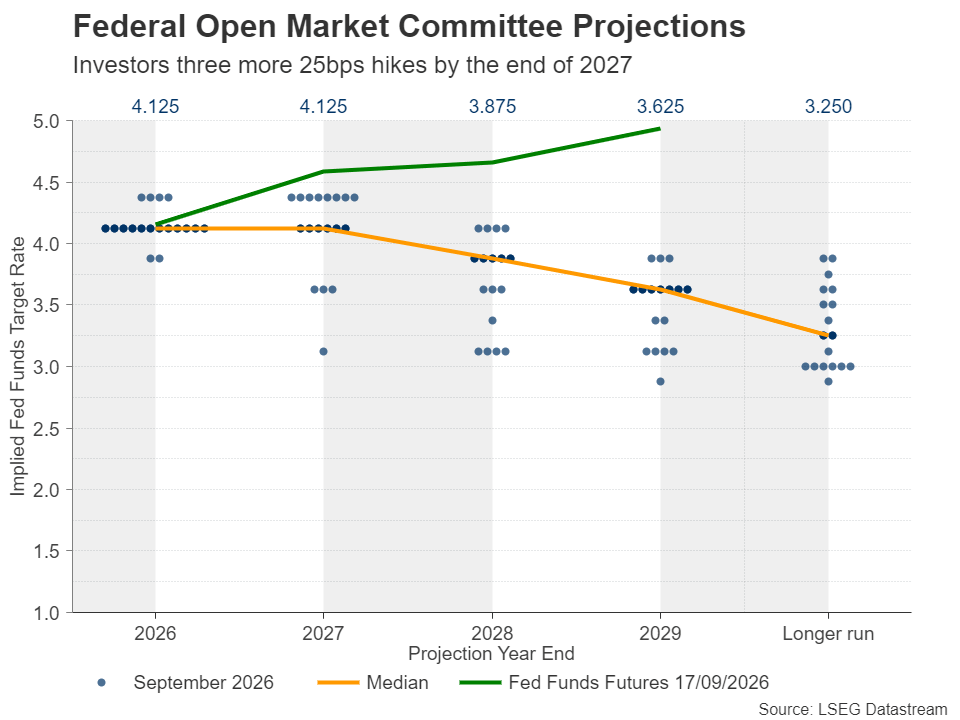
Although Fed Chair Warsh did not submit rate or other economic projections again, he supported Wednesday’s rate hike, while at the press conference, he stressed the need for higher interest rates due to an accelerating economy, which alongside jobs growth is adding to price pressures that are not solely driven by oil prices and import tariffs anymore.
Given that Warsh was appointed by US President Trump likely on the premise that he will be more dovish than his predecessor, Jerome Powell, Trump was quick to react and note that US interest rates should be slashed to around 1%. The big question now is whether Trump will initiate a new confrontation with Warsh, similar to the one he had with Powell, or whether Warsh will, at some point, begin accommodating Trump’s wishes.
Fed Speakers and S&P Flash PMIs Enter the Spotlight
However, Warsh alone cannot change the path of monetary policy. More members may need to be convinced that aggressive rate cuts are not needed. With that in mind, investors may pay extra attention to Fed speeches next week. Chicago Fed President Austan Goolsbee will step up to the rostrum on Monday, while Vice Chair Philip Jefferson and New York President John Williams will follow on Tuesday.
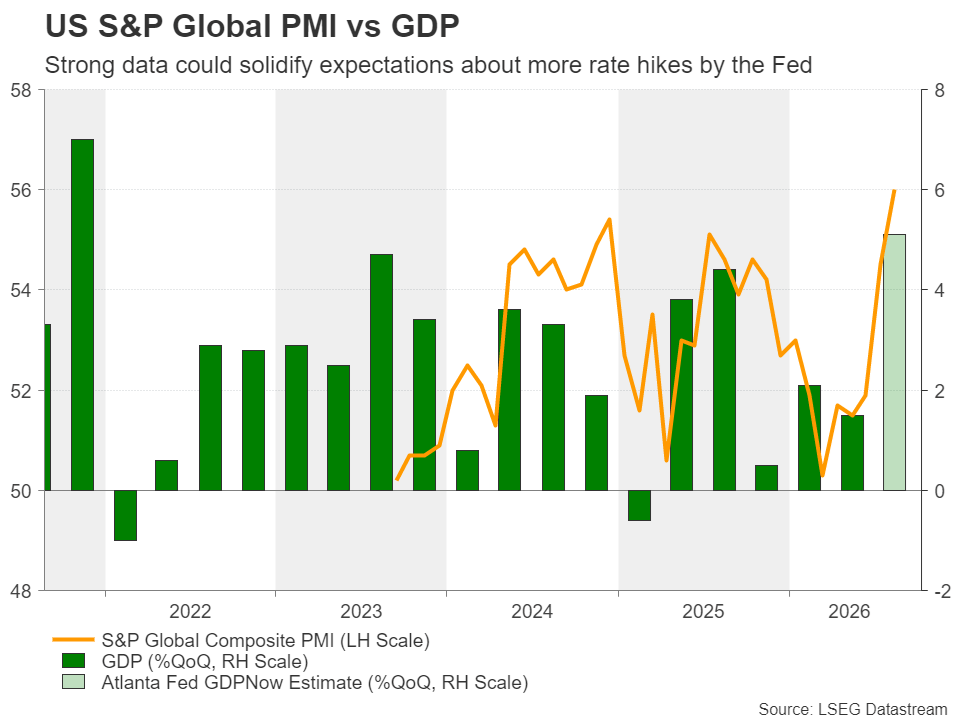
If they reiterate concerns about elevated inflation and the upside risks stemming from the Middle East conflict, investors are likely to maintain their hawkish Fed hike bets, especially if Wednesday’s S&P flash PMIs for September support the notion that the US economy is faring well. Given the anxiety surrounding the inflation risks, the price subcomponents of the PMI reports may be scrutinized more. After the acceleration revealed in the August PPI figures, investors will be eager to find out whether the upside pressure in producer prices was passed on to consumers. The new estimate of the Atlanta Fed GDPNow model for Q3, due out on Friday, could also attract attention.
Eurozone and UK Flash PMIs Also in Focus
The Eurozone and UK flash PMIs for September will also be released on Wednesday, ahead of the US prints.
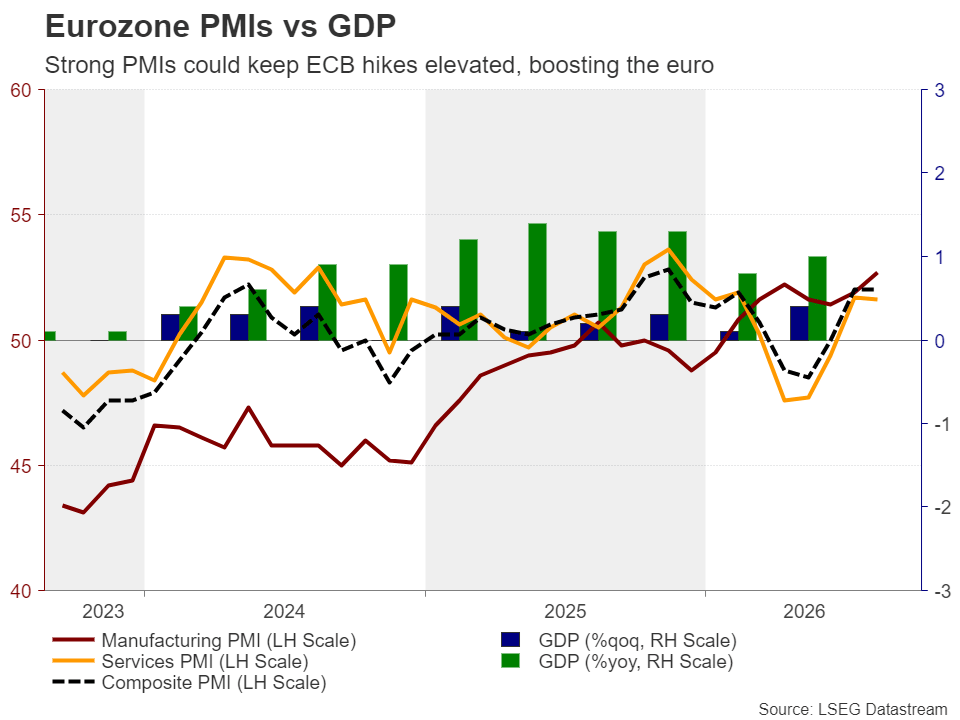
Getting the ball rolling with the Eurozone, at its September 10 decision, the European Central Bank (ECB) raised interest rates by 25bps, also citing renewed inflation pressures, with reports hitting the wires after the meeting that policymakers believe further tightening may be necessary should energy prices create more inflation-related problems.
With Eurozone money markets pointing to three more quarter-point hikes by the end of next year, strong PMIs may be needed for the euro to flex some muscles. Similarly to the US data, details about prices charged could also be closely monitored.
As for the UK, the Bank of England (BoE) decided to keep interest rates unchanged via a 6-3 vote, with the three dissenters favoring a 25bps rate increase. Although officials believed that second-round effects from the Iran-related energy shock remain limited for now, they warned that prolonged energy volatility could distort inflation expectations. However, they also acknowledged that labor-market conditions remain relatively weak, suggesting that future decisions will be difficult balancing acts between inflation and economic growth. Thus, when it comes to the UK PMIs, pound traders may focus, not only on prices, but on employment information as well.
SNB Decides on Monetary Policy Amid Controlled Inflation
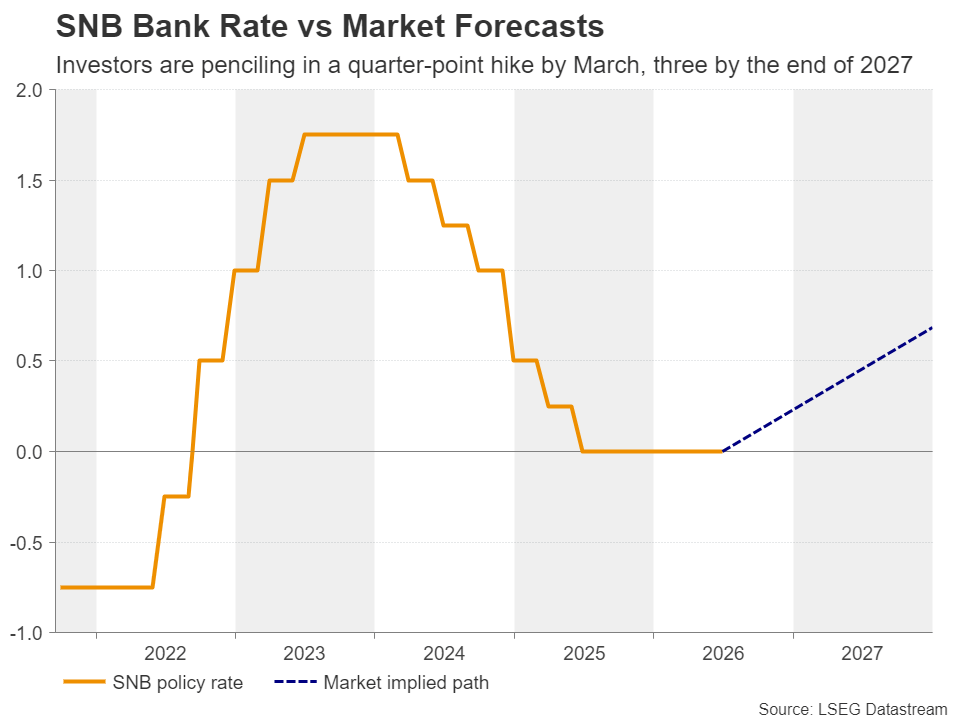
On Thursday, the Swiss National Bank (SNB) will decide on interest rates. Despite other major economies facing upside inflation-related risks, Switzerland’s price pressures have remained low. Consumer prices accelerated to 0.8% year-on-year in August, the fastest pace in almost two years, but inflation remains comfortably within the SNB’s price stability range of 0-2%.
Therefore, Swiss policymakers are likely to keep interest rates untouched at 0.0% and perhaps reiterate their willingness to intervene in the FX market should the franc appreciate excessively. A strong franc helps contain imported inflation but hurts exporters and economic growth. And despite entering a downtrend against its European counterpart, the franc remains relatively elevated by historical standards, which corroborates the idea that policymakers are unlikely to drop warnings about potential intervention, should it be deemed necessary.
Now, how the franc will react to the outcome may depend on the updated inflation projections. Should there be noticeable upward revisions amid the risks stemming from the Middle East, traders may bring forward the timing of when they expect a rate hike by the SNB, thereby allowing some room for recovery to the franc. For now, a 25bps rate increase is fully factored in for March.
Traders Eye Trump-Xi Meeting for Clues on Trade and AI
Elsewhere, the Australian employment report could prove whether aussie traders are right in assigning a strong 80% chance of another rate hike later this month, while when it comes to politics, US President Trump is scheduled to meet Chinese President Xi Jinping at the White House on Thursday. Trade, tariffs, rare-earth exports and AI will be among the issues that will be discussed. Treasury Secretary Scott Bessent will also meet Vice Premier He Lifeng ahead of the summit and thus, markets may start receiving interesting headlines earlier than the Trump-Xi meeting.
Investors may focus on whether the world’s two largest economies are willing to extend their existing trade truce and potentially reduce some trade levies. Should this be the case, global risk appetite could improve, with aussie and kiwi perhaps being among the main beneficiaries. Discussions related to the nations’ AI rivalry could also be scrutinized.