- US CPI and retail sales will shape Fed hike expectations.
- France’s fiscal crisis adds pressure on the euro and ECB.
- Australian jobs figures and UK data to test RBA and BoE hike bets.
- IMF-World Bank meetings and Q3 bank earnings may enhance volatility.
Dollar Flexes Muscles Despite October Hike Fading
The US dollar held relatively strong this week, despite the disappointing US jobs report on October 2, which further decreased the probability of a back-to-back rate hike by the Fed at the upcoming gathering on October 28.
Just after the latest meeting, where officials decided to raise interest rates by 25bps and appeared hawkish enough to satisfy market expectations of around 100bps worth of additional rate increases by the end of 2027, an October rate increase received a strong 70-75% probability.
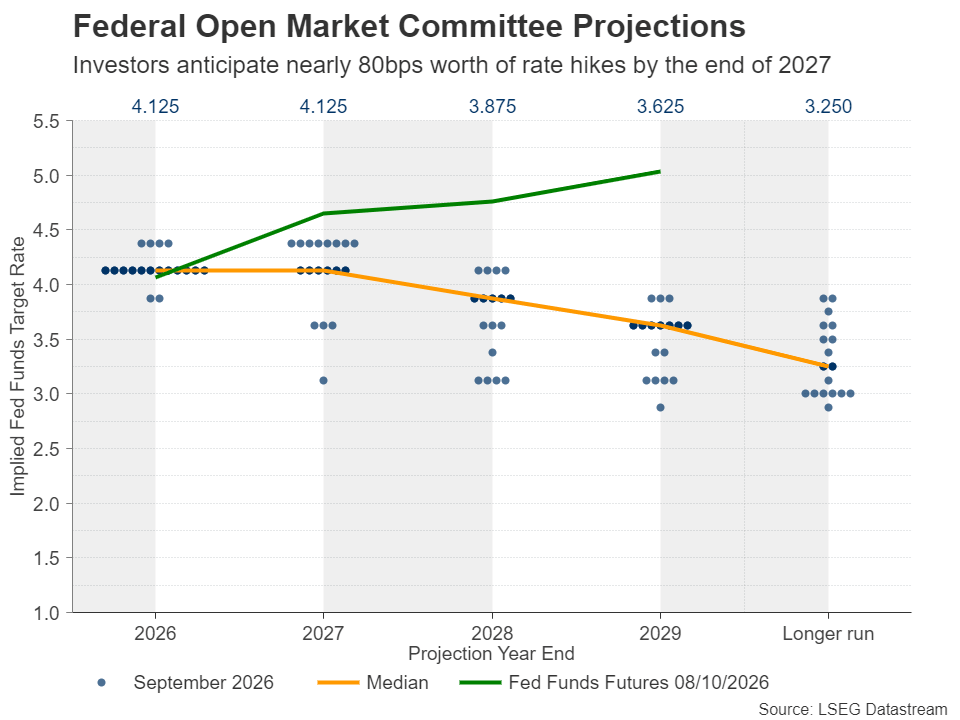
However, remarks by Fed Vice Chair Jefferson and New York Fed President Williams that the Committee should not rush into pressing the hike button again, combined with the soft labor market data, brought that probability down to around 20%. Yet, a quarter-point increase is fully penciled in for December, while a total of 80bps worth of rate hikes are still baked into the cake by the end of 2027.
Perhaps investors remained convinced that the Fed may need to proceed with more hikes, even if an October hike nearly dropped off the table, as the ISM services PMI for September, albeit slowing somewhat, remained well into expansionary territory and most importantly, showed that prices paid accelerated to the highest since July 2022.
US CPI Inflation Could Reshape Fed Rate Expectations
With all that in mind, next week’s US CPI data for September may attract high interest as another round of sticky figures may revive speculation about faster rate hikes. Besides the ISM services PMI, the flash S&P Global PMIs for September also suggested upside risks to the CPI data as input-price inflation rose to its highest since October 2022. On top of that, the University of Michigan 1-year inflation expectations accelerated to 4.6% from 4.0%.
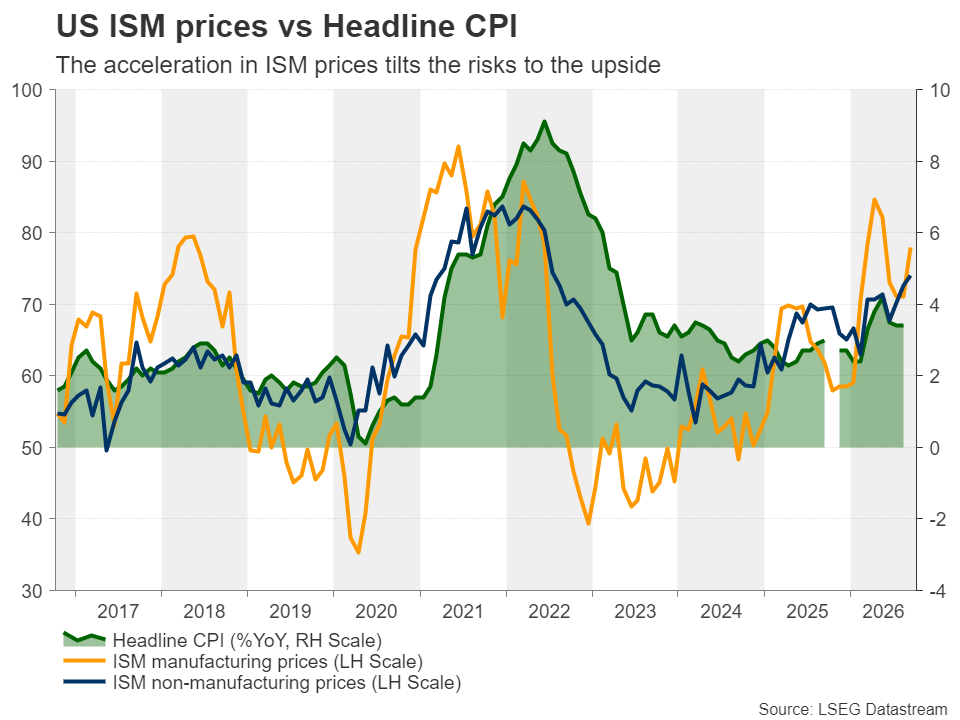
Even if the October hike probability remains low, more basis points worth of increases could be added for next year. This could add more fuel to the dollar’s engines and perhaps push long-dated Treasury yields to new multi-decade highs.
The PPI numbers and retail sales for September will be released on Thursday, while US industrial production figures for the same month will be available on Friday. More data pointing to hot inflation and potentially healthy economic growth could further solidify the notion of more rate hikes by the Fed in 2027.
Euro at the Mercy of French Politics
Euro/dollar traders are in for a very difficult week as besides the US CPI numbers, they will have to navigate France’s political uncertainty as well.
Prime Minister Sébastien Lecornu’s minority government presented the 2027 budget bill to parliament, with the proposal including roughly 43 billion euros in new savings, with the aim of reducing the budget deficit from 5.4% of GDP in 2026 to 5.0% in 2027. However, the proposal is facing major obstacles, with reports noting that opposition parties could demand concessions or threaten a no-confidence vote. On Tuesday, a detailed debate in the National Assembly will begin.
With investors doubting whether the proposal will pass, French government bond yields extended their rally, with the 10-year French-German yield spread briefly surpassing 140bps, the widest since the Eurozone debt crisis in 2012. It is also worth mentioning that French credit default swaps also soared, as traders are likely pricing in a fiscal contagion across other Eurozone nations as well.
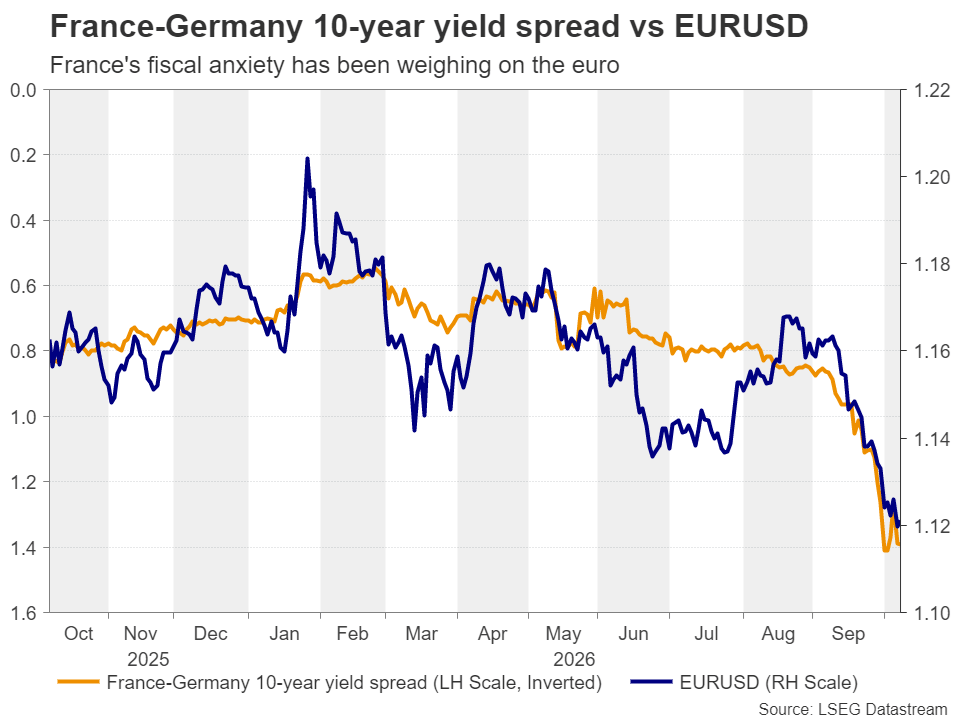
This leaves the European Central Bank (ECB) standing between a rock and a hard place. On the one hand, it needs to continue raising interest rates to fight stubbornly sticky inflation, but on the other hand, aggressive tightening may result in weaker growth and prompt investors to demand even higher yields for financing France’s debt. That’s maybe why Eurozone money markets are now factoring in 70bps worth of additional rate hikes by the end of 2027, compared to 100bps a few days ago.
What’s more, intervention by the ECB through its Transmission Protection Instrument (TPI) is widely discussed, but it remains an unlikely scenario for now. Bank of France Governor Emmanuel Moulin said on October 7 that France does not currently need ECB assistance, stressing that fiscal consolidation and a credible budget are the appropriate solutions.
AU and UK Data to Test RBA and BoE Rate Hike Bets
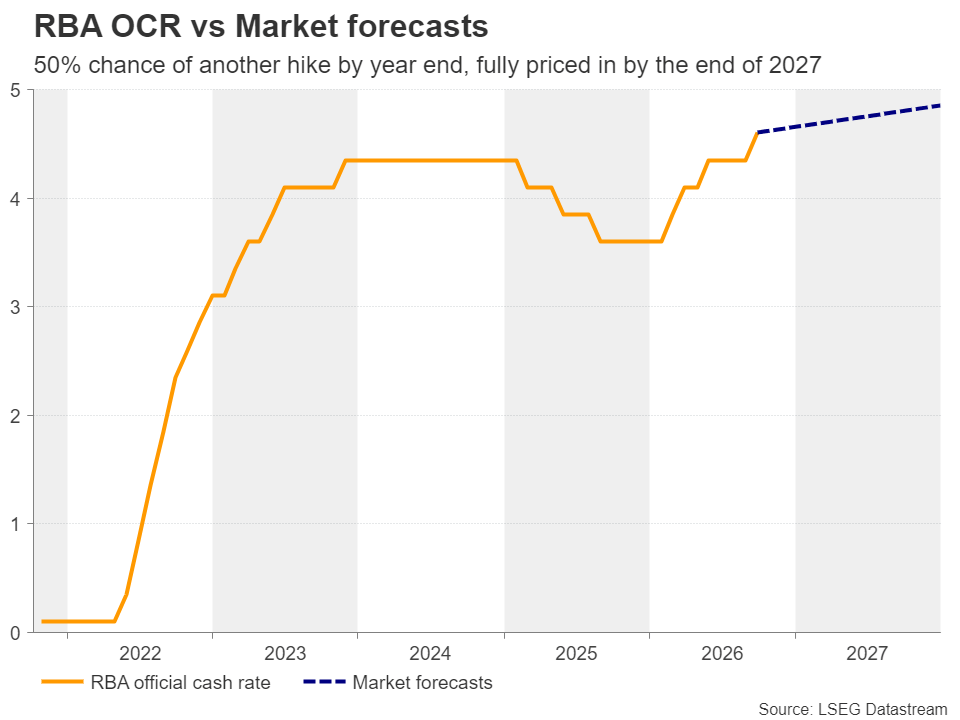
Elsewhere, the minutes of the latest RBA decision on Tuesday and Australia’s employment report on Thursday could prove decisive on whether Australian rate setters will press the hike button once more before the turn of the year. Currently, following the fourth hike of 2026 on September 29, investors are assigning a 50% chance of a fifth one before the turn of the year. Should rate hike expectations edge higher, the aussie may benefit. China’s CPI and PPI data for September, due out on Wednesday, may be also closely watched by aussie traders as China is Australia’s main trading partner.
From the UK, the monthly GDP for August will be released alongside the industrial production and trade data for the same month. At its latest gathering, the BoE held interest rates unchanged, but three members voted for an immediate hike. The overall tone was hawkish amid persistently high energy prices, with investors now assigning a strong 85% chance of a hike at the upcoming gathering on November 5. Although oil prices pulled back somewhat since September 15, encouraging data may solidify the case of an imminent hike, even if officials make it clear that they will evaluate incoming data for their future decisions.
IMF-World Bank Meetings and Q3 Earnings Also on Tap
It is also worth mentioning that the IMF and World Bank Annual meetings will take place in Bangkok running through the whole week. The most important releases will be on Tuesday, when the IMF publishes its World Economic Outlook and Global Financial Stability Report, associated with press briefings.
Tuesday will also mark the beginning of the Q3 earnings season, with the major banks taking centre stage. JPMorgan, Goldman Sachs, Citigroup and Wells Fargo are all due to report on Tuesday, followed by Bank of America and Morgan Stanley on Wednesday. The big question for the bank earnings may be how severely did tightening financial conditions amid rising yields have weighed on credit demand.